⭐ EXPERT-REVIEWED  |  ✅ UPDATED 2026  |  🔒 NO SPONSORED BIAS  |  📚 EVIDENCE-BASED

Category: Saving Money

  • HSA Contribution Limits 2026: How to Maximize Your Wealth

    HSA Contribution Limits 2026: How to Maximize Your Wealth

    Key Takeaways

    • Understanding the 2026 HSA contribution limits is the first step toward effective long-term wealth building.
    • The HSA’s triple-tax advantage makes it arguably the most powerful retirement vehicle available today.
    • Strategic contribution methods, such as payroll deduction or catch-up contributions, can significantly accelerate your wealth goals.
    • Treating your HSA as an investment account rather than a checking account is vital for capturing compound growth.
    • Employer contributions act as an immediate return on investment that should be prioritized in every financial plan.

    For many individuals, the health savings account is often relegated to the status of a simple medical debit card—a place to set aside funds for a co-pay or an urgent pharmacy trip. However, those who look closely at the mechanics of these accounts realize that they are actually one of the most sophisticated wealth-building engines in the modern tax code. By aligning your financial planning with the current HSA contribution limits 2026, you can shift your perspective from short-term medical savings to long-term financial security. This guide, provided by the wealthsimplyput Editorial Team, explores how to harness the full potential of your HSA, transforming it from a healthcare expense tool into a formidable pillar of your overarching wealth strategy.

    Understanding the 2026 HSA Contribution Limits

    The landscape of tax-advantaged accounts is constantly shifting, and staying current with the HSA contribution limits 2026 is a prerequisite for any serious wealth-building strategy. Because these limits are adjusted periodically by the Internal Revenue Service to account for cost-of-living increases, failing to update your contribution automation at the start of each calendar year can result in missed opportunities to shelter your income from taxes. When we talk about these limits, we are defining the maximum total amount—including both your own personal contributions and any funds provided by your employer—that can be deposited into your account within the tax year.

    For individuals enrolled in a High-Deductible Health Plan (HDHP), understanding these thresholds is critical. If you are filing as an individual, there is a distinct limit, while those with family coverage are granted a significantly higher ceiling to reflect the broader scope of healthcare risks associated with multiple dependents. Furthermore, the IRS provides a generous “catch-up” contribution provision for individuals who have reached age 55. This feature is particularly valuable for those who may have started their wealth-building journey later in life, allowing them to accelerate their savings in the decade leading up to the typical retirement window. It is important to note that these catch-up contributions can be made regardless of whether your employer contributes to the account, provided you meet the minimum age requirement by the end of the tax year.

    To optimize your wealth, you must view these limits not as goals, but as boundaries to be pushed. Many savers find it beneficial to adjust their payroll deductions early in the year to ensure they hit these caps without over-contributing. Exceeding these limits can lead to complex tax filings and potential penalties, so precision is key. By aligning your contribution schedule with the 2026 limits, you ensure that your money is working as efficiently as possible within the regulatory environment. This disciplined approach to funding is the foundation upon which larger investment strategies are built, ensuring that every dollar contributed is shielded from current taxes, thereby increasing the total amount available to be invested in the market over time.

    Why Your HSA Is Your Most Powerful Wealth-Building Tool

    If you were to rank the various tax-advantaged accounts available to the average investor, the health savings account would frequently rise to the top of the list for its sheer versatility. While traditional and Roth IRAs are powerful, the HSA offers a unique combination of features that essentially creates a “best of both worlds” scenario. The central pillar of this strength is the triple-tax advantage: your contributions are tax-deductible, your investment growth is tax-deferred, and your withdrawals are tax-free when used for qualified medical expenses. This trifecta is essentially unseen in any other financial instrument, making it a cornerstone for those focused on accumulating long-term wealth.

    When you shift your mindset from using an HSA for immediate bills to using it as a long-term investment vehicle, you unlock the power of compounding interest. Many people treat their health savings account as a pass-through entity—money goes in for a bill, and money goes out for a bill. However, when you instead fund your medical expenses out of your liquid emergency savings or current income, you allow the balance in your HSA to remain invested in equities, bonds, or other growth-oriented assets. Over twenty or thirty years, this strategy can turn a few thousand dollars of annual savings into a six-figure retirement asset. This is why HSA wealth building is so highly regarded by financial planners; it allows you to hedge against the rising costs of healthcare in retirement while simultaneously serving as a secondary, highly tax-efficient retirement account.

    Furthermore, the HSA acts as a unique shield during your later years. As you grow older, the statistical likelihood of requiring medical care increases, and these costs can quickly erode the principal of a standard retirement portfolio. By having a separate, dedicated “health-wealth” bucket, you ensure that your other investments (such as a 401k or traditional brokerage account) can continue to provide for your lifestyle and legacy without being cannibalized by chronic care costs. By prioritizing your HSA contributions today, you are essentially buying a high-yield insurance policy against the financial risks of aging. It is not merely a tool for saving money; it is a mechanism for protecting the wealth you have spent a lifetime constructing, ensuring that your financial freedom is not compromised by the inevitable realities of physical health in one’s golden years.

    How to Maximize HSA Contributions on Any Budget

    Achieving the maximum contribution limit might feel daunting if you are in the early stages of your career, but maximizing your HSA is rarely about a single lump-sum deposit. Instead, it is about creating a sustainable system of incremental contributions that integrate into your monthly budget. Most successful savers start by automating their contributions directly from their paycheck. This “set it and forget it” mentality is effective because it reduces the friction between receiving your income and saving it. When the money never hits your primary checking account, you are less likely to miss it, allowing you to live on a budget that already accounts for your health savings goals.

    If you find that your current budget is too tight to reach the maximum limits, look for “found money” opportunities. Many people allocate their annual tax refunds, performance bonuses, or even small cash gifts directly to their HSA rather than spending them on consumer goods. This strategy allows you to reach the maximum capacity without feeling an immediate pinch in your day-to-day cash flow. Additionally, if you are struggling to bridge the gap between your current savings rate and the annual limit, consider the “micro-contribution” strategy—increasing your payroll deduction by even one percent of your salary. Over time, these small adjustments have a compounding effect, not just in the principal saved, but in the habit of financial discipline they foster.

    Strategy Implementation Best For
    Payroll Deduction Automated pre-tax reduction Consistency and simplicity
    Windfall Allocation Directing bonuses/refunds Aggressive savers
    Catch-up Deposits Age 55+ additional funding Late-stage wealth building

    Finally, remember that maximizing your contributions is only half the battle; how you manage that capital matters just as much. Once your HSA reaches a certain threshold, many providers allow you to transition the funds from a low-interest cash account into a curated list of investment funds. You should actively manage this aspect of your account. If you treat your HSA as a pure savings account earning negligible interest, inflation will eventually erode the real value of your contributions. By investing the balance, you align the growth of your healthcare fund with the growth of your total net worth. This transition from “saver” to “investor” is the final step in truly maximizing your HSA, turning it from a stagnant pool of cash into a dynamic engine for long-term growth.

    The Triple-Tax Advantage: Why You Should Never Withdraw Early

    The “triple-tax advantage” is the siren song of the HSA, yet it is frequently misunderstood or ignored by those who treat their account as a simple medical reimbursement fund. To recap, this advantage consists of: tax-deductible contributions, tax-deferred growth, and tax-free withdrawals for qualified medical expenses. When you view these benefits in aggregate, it becomes clear that withdrawing your money for current medical needs is often the least efficient way to use the account. By paying for current out-of-pocket medical expenses with post-tax money from your regular checking account, you allow your HSA balance to remain invested and grow, compounding over decades. This is a subtle but profound shift in financial philosophy.

    Think of it as an arbitrage play against your own future. If you pay a $200 doctor’s bill today using your HSA card, that $200 is gone and ceases to grow. If you pay that same $200 bill with your credit card—and then pay off your credit card from your normal budget—that original $200 in your HSA continues to sit in an investment account. Assuming a reasonable rate of return over twenty years, that initial investment could potentially double or triple. Meanwhile, the IRS does not mandate that you withdraw your HSA funds in the same year you incur the medical expense. You can hold onto your receipts and reimburse yourself at any point in the future—even decades later—provided the expense occurred after you opened your account.

    This creates a massive opportunity for tax-free wealth building. By storing your receipts in a digital folder or a dedicated physical file, you are essentially creating a “deferred tax-free withdrawal” option. When you reach retirement, you can use these accumulated receipts to withdraw thousands of dollars from your HSA completely tax-free, effectively providing yourself with a tax-free bridge to fund your lifestyle. This strategy turns your medical expenses into a mechanism for tax-efficient cash flow management. It requires organization and the discipline to pay for today’s costs out of your current pocket, but the long-term payoff is a significantly larger retirement nest egg. Avoiding early, unnecessary withdrawals is one of the most effective, yet underutilized, health savings account strategies available to the average taxpayer.

    Employer Contributions: Are You Leaving Free Money on the Table?

    In the world of corporate compensation, employer contributions to an HSA are often one of the most undervalued benefits offered. Unlike a 401k match, which requires you to contribute your own money to receive a portion of the benefit, many employers provide an immediate, flat contribution to your HSA just for enrolling in a high-deductible health plan. This is essentially free money added to your account by your employer, and it is a critical component of your annual contribution limit. Ignoring this or failing to factor it into your total wealth strategy means you are likely missing out on an immediate return on investment that could be working for you from day one.

    When you sit down to calculate how much you need to save to hit the 2026 maximums, your first step should be to confirm exactly how much your employer plans to contribute. Since these employer contributions count toward your total annual limit, you must adjust your own personal contribution rate accordingly. For example, if the limit is set at a specific level and your employer provides a generous seed amount, your own personal savings requirement to hit that limit is lowered. This provides you with extra liquidity in your monthly budget that can be redirected toward other investments, such as a Roth IRA or a traditional brokerage account. The goal is to ensure you hit the maximum allowed by law, regardless of the source of the funds.

    Beyond the simple math, consider the employer contribution as a foundational boost. If you are starting a new job, evaluating health insurance options, or reconsidering your benefits during an open enrollment period, the generosity of the employer HSA contribution should be a major weighting factor. A robust employer contribution can effectively lower your insurance premium costs and significantly accelerate your wealth building. If your employer provides a matching program, ensure you are contributing enough of your own money to capture the full match—this is a “no-brainer” financial decision. By treating employer contributions with the same level of attention as your own salary, you ensure that your total compensation package is working as hard as possible to grow your net worth. It is a simple step, yet one that highlights the difference between those who passively participate in benefits and those who strategically leverage them to build lasting wealth.

    Strategies for Investing Your HSA Funds for Growth

    Many individuals mistakenly view a Health Savings Account (HSA) as a simple transactional vehicle for immediate medical expenses. However, for those focused on long-term wealth, the true power of an HSA lies in its triple-tax advantage, which acts as a force multiplier for investment growth. Once your HSA balance crosses a certain threshold—often suggested by experts to be around $2,000 to $5,000—you should consider transitioning those funds from cash to diversified investment assets.

    To maximize wealth building, you must treat your HSA as a shadow retirement account. Because HSA funds are exempt from federal income taxes on both contributions and qualified withdrawals, your investments compound in a tax-sheltered environment similar to a Roth IRA. The key strategy here is to select low-cost, broad-market index funds or exchange-traded funds (ETFs) that align with your risk tolerance and time horizon. By keeping your HSA funds invested in the market for decades rather than spending them on routine pharmacy visits, you allow the principle of compound interest to work in your favor.

    Furthermore, it is advisable to view your HSA as a “last resort” for healthcare funding during your working years. If you can afford to pay for current medical expenses out-of-pocket, you should do so, allowing your HSA investments to grow undisturbed. By saving your itemized receipts for medical procedures, you maintain the flexibility to reimburse yourself tax-free at any point in the future—even years or decades later—providing you with a powerful liquid wealth tool for unexpected life events or retirement needs.

    Managing HSA Catch-Up Contributions for Those Over 55

    As you approach retirement, the financial landscape changes, and the IRS provides specific provisions to help you bolster your health savings. If you are age 55 or older, you are eligible to contribute an additional $1,000 beyond the standard annual HSA contribution limit. These catch-up contributions are an essential lever for wealth management, as they allow for a significantly higher total contribution limit, effectively accelerating your savings rate during your peak earning years.

    There is a specific nuance regarding spousal contributions that every couple should understand. If both spouses are 55 or older and both are covered under an HSA-eligible High Deductible Health Plan (HDHP), each individual can contribute their own catch-up amount. However, these contributions must be made into separate HSA accounts, as a single HSA cannot be held jointly. This strategy enables a household to maximize their tax-advantaged savings significantly, providing a robust buffer for the high healthcare costs typically associated with aging.

    For those still working in their late 50s and 60s, these catch-up contributions serve as a vital hedge against medical inflation. By maxing out both standard and catch-up contributions, you are essentially pre-funding your retirement healthcare expenses, ensuring that you do not have to dip into your 401(k) or IRA funds to cover premiums or deductibles later in life. This preserves your other retirement assets for living expenses and lifestyle choices.

    Common HSA Contribution Mistakes That Could Cost You Wealth

    Even seasoned investors occasionally stumble when managing their HSAs. One of the most frequent errors is failing to synchronize contributions with eligibility. If you switch from an HDHP to a standard plan midway through the year, your contribution limit is prorated. Failing to adjust your payroll deductions to reflect this change can lead to excess contributions, which are subject to excise taxes if not corrected before the tax filing deadline.

    Another common mistake is neglecting to invest the funds. Keeping a large portion of your HSA in a low-interest cash sweep account creates a significant opportunity cost. Inflation can erode the purchasing power of your medical savings if they aren’t positioned to earn market returns. While liquidity is necessary for the next few months of medical expenses, the remainder should be invested in assets that align with your long-term wealth strategy.

    Lastly, many taxpayers fail to maximize their contributions during years when they have unexpected medical windfalls. Some assume that if they have already paid their expenses, they no longer “need” to contribute. This ignores the goal of wealth building. Always contribute the maximum amount allowed by law, regardless of your current health status, to secure the tax deduction and the long-term investment runway.

    Strategy Wealth Impact Best For
    Pay out-of-pocket Highest Those with strong cash flow
    Invest in Index Funds High Long-term wealth builders
    Max out catch-up Moderate Ages 55+
    Cash-only balance Low Short-term expense coverage

    How to Balance HSA Contributions With Other Retirement Accounts

    Determining where to allocate your next dollar involves understanding the hierarchy of tax efficiency. Because the HSA offers triple-tax advantages—deductible contributions, tax-free growth, and tax-free withdrawals for medical costs—it is often considered one of the most efficient wealth-building vehicles available. Many financial professionals suggest a specific order of operations to maximize the efficiency of your retirement savings.

    A common approach is to first contribute enough to your employer’s 401(k) to capture the full company match, as this is an immediate 100% return on your money. After securing the match, many turn their focus to the HSA. By maxing out the HSA contribution, you reduce your taxable income and create a fund that is effectively better than an IRA, because it avoids taxes on both the way in and the way out. Once the HSA is maxed, you can return to contributing to your 401(k) or a Roth IRA to round out your portfolio.

    This balance requires ongoing monitoring. As your income grows, your ability to contribute to various accounts may shift, particularly if you reach income limits for certain types of IRAs. However, the HSA remains a constant. By treating your HSA contributions as a non-negotiable expense in your monthly budget, you ensure steady progress toward a more secure financial future, balancing immediate tax savings with long-term capital accumulation.

    Tracking Your Healthcare Expenses for Long-Term Reimbursement

    One of the most underutilized strategies for building long-term wealth via your HSA is the ability to reimburse yourself for medical expenses incurred in previous years. There is no “statute of limitations” on when you must withdraw funds from an HSA for a qualified medical expense, provided the expense occurred after your HSA was established. This creates a “stealth” investment account that can grow for decades while you keep a ledger of your out-of-pocket costs.

    To implement this, keep a digital folder or a spreadsheet of all medical receipts, prescriptions, and co-pays. When you visit the doctor, pay with a personal credit card to gain rewards points or cash back, then upload the receipt to a secure cloud-based storage system. By keeping a detailed log, you preserve the option to withdraw tax-free cash from your HSA later in life, perhaps when you need to cover a major life expense or a sudden gap in retirement income.

    This method effectively turns your HSA into a secondary emergency fund that grows tax-free. If you never have a medical emergency, those funds remain invested. If you do have an emergency, you have a deep reserve of “receipts” that allow you to access your HSA wealth without triggering tax consequences, providing you with immense financial flexibility throughout your retirement years.

    Frequently Asked Questions

    Can I invest my HSA money in stocks and bonds?

    Yes, most HSA providers offer an investment portal that allows you to purchase a variety of mutual funds, ETFs, and individual stocks. You are not required to keep your funds in a cash-based savings account.

    What happens to my HSA funds if I change jobs?

    Your HSA is individually owned, not tied to your employer. If you change jobs or retire, the account remains yours. You can keep it with your current provider or roll it over to a new HSA custodian without any tax penalties.

    Are HSA contributions tax-deductible if I don’t itemize?

    Yes, HSA contributions made through payroll deductions are excluded from your gross income, and contributions made directly are “above-the-line” deductions, meaning you can deduct them regardless of whether you itemize or take the standard deduction.

    Can I use my HSA to pay for Medicare premiums?

    Once you reach age 65, you can use your HSA funds to pay for Medicare Part B, Part D, and Medicare Advantage premiums tax-free. Note that you cannot use HSA funds to pay for Medigap (Medicare Supplement) premiums.

    What counts as a “qualified medical expense”?

    Qualified medical expenses are defined by the IRS and include a wide range of services and products, such as doctor visits, dental work, vision care, prescription medications, and certain medical equipment. You can find the full list in IRS Publication 502.

    What is the penalty for using HSA funds for non-medical expenses?

    If you use HSA funds for non-qualified expenses, you must pay income tax on the amount, plus a 20% penalty. If you are age 65 or older, the 20% penalty is waived, though you will still owe standard income tax on the withdrawal.

    Conclusion

    Maximizing your wealth through an HSA is about shifting your perspective: stop viewing it as a short-term medical savings bucket and start treating it as a long-term investment engine. By consistently reaching your annual contribution limits, investing in diversified assets, and carefully tracking your out-of-pocket expenses for future tax-free reimbursement, you create a powerful financial foundation that supports both your health and your broader wealth goals. The combination of tax-deductible contributions, tax-free market growth, and tax-free withdrawals is an advantage that few other financial instruments can match.

    The best time to refine your strategy was years ago, but the second best time is today. Review your current contribution rates, log into your HSA provider portal to ensure your assets are invested, and start digitizing your medical receipts. Building wealth requires discipline, and the HSA is one of the most efficient tools at your disposal to reach your goals. Take action today to secure your future tomorrow.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • HSA Investing: How to Turn Your Health Account Into a Wealth Engine

    HSA Investing: How to Turn Your Health Account Into a Wealth Engine

    Key Takeaways

    • The HSA triple tax advantage allows for tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.
    • Many savers treat their HSA like a simple checking account, missing out on the massive potential of long-term market exposure.
    • Investing HSA funds in diversified assets allows your account to evolve into a powerful, tax-advantaged engine for your overall wealth.
    • By paying out-of-pocket for current medical needs and allowing your HSA balance to grow, you maximize the impact of compound interest.
    • Treating your HSA as a dedicated retirement vehicle can provide a significant secondary safety net once you reach age 65.

    For many, the Health Savings Account (HSA) is seen merely as a way to pay for a flu shot, a routine prescription, or a deductible after a trip to the urgent care clinic. However, for the financially savvy, the HSA is one of the most potent, underutilized tools in the modern financial toolkit. When viewed through the lens of long-term wealth building, the HSA is not just a health account; it is a tax-advantaged powerhouse that can significantly supplement your retirement strategy. By understanding the mechanics of how to optimize these funds, you can shift from simply “spending” your health savings to intentionally growing your personal wealth, creating a resilient financial foundation that stretches far beyond the doctor’s office.

    Understanding the Triple Tax Advantage of HSAs

    The primary reason financial experts often categorize the HSA as the single best savings vehicle available today is its unique “triple tax advantage.” While other retirement accounts like the 401(k) or the Traditional IRA offer tax-deferred growth, they typically require you to pay income taxes upon withdrawal. The HSA, when used correctly, provides a trifecta of tax benefits that are virtually unmatched in the financial world.

    First, contributions to your HSA are 100% tax-deductible. If you are enrolled in a High Deductible Health Plan (HDHP), the money you contribute directly from your paycheck or via individual contributions lowers your taxable income for the year. This effectively gives you a “discount” on your healthcare savings, as you are shielding that money from the IRS before it is even taxed.

    Second, the funds inside your account enjoy tax-free growth. Unlike a standard brokerage account where you must pay capital gains taxes on your investment dividends or asset appreciation, everything inside an HSA grows entirely tax-free. Whether your investments gain 5% or 50% in a given year, you do not owe the government a single cent in taxes on that growth. This allows your wealth to compound significantly faster than it would in a traditional investment account.

    Third, and perhaps most importantly, withdrawals are tax-free when used for qualified medical expenses. This covers a wide range of costs—from co-pays and prescriptions to specialized surgeries and even certain long-term care services. When you consider these three benefits in tandem, you realize that the HSA is the only account where money goes in tax-free, grows tax-free, and comes out tax-free.

    To maximize this, it is essential to distinguish between “spending” your HSA and “investing” your HSA. If you use your funds for immediate, small medical costs, you are essentially liquidating a high-growth tax-sheltered vehicle to pay for a low-cost expense. By allowing these funds to remain in the account, you allow them to benefit from long-term market exposure. Many investors choose to view the HSA as a “stealth IRA,” aiming to keep the balance invested for as long as possible. The triple tax advantage serves as the bedrock of your wealth-building strategy, providing an environment where your assets are shielded from the “tax drag” that typically erodes the value of standard investment portfolios over decades.

    Why Most People Underutilize Their HSA for Wealth Building

    Despite the profound benefits, a vast majority of HSA holders treat their accounts as simple transaction wallets. They view the balance as a “use it or lose it” fund, similar to a Flexible Spending Account (FSA). This is a critical misconception. Unlike FSAs, which often expire at the end of the calendar year, HSA funds roll over indefinitely. They belong to you, not your employer, and they remain in your possession even if you change jobs, retire, or switch health insurance plans.

    The primary reason for this underutilization is a lack of financial literacy regarding the investment potential of these accounts. Many HSA providers default your contributions into a low-interest cash savings account. While this provides stability, it also guarantees that your money will lose purchasing power over time due to inflation. If your HSA is sitting in a cash account earning negligible interest, you are essentially paying an “inflation tax” on your medical savings.

    Furthermore, there is a psychological barrier: the fear of medical debt. Many people feel compelled to spend their HSA funds on minor medical expenses because they want to avoid out-of-pocket costs at the moment of service. While this is understandable for those on tight budgets, for those with the ability to cover small medical costs with their current cash flow, this approach is a significant missed opportunity. By spending the HSA balance, you are destroying the opportunity for that capital to grow over 20 or 30 years.

    Another factor is the complexity of investment options. Some people find the prospect of managing a separate investment portfolio daunting. They may feel that investment decisions belong strictly in their 401(k) or brokerage accounts. However, the HSA is fundamentally an investment account if you choose to make it one. When you neglect to move your HSA cash into a diversified portfolio of index funds or ETFs, you are ignoring a core component of your overall net worth. The goal of wealth building is to maximize tax-efficient growth; by leaving your HSA stagnant, you are leaving thousands of dollars in potential growth on the table. Recognizing that your HSA is a long-term asset, rather than a short-term expense fund, is the first step toward transforming it into a true engine for your financial future.

    How to Transition Your HSA From a Savings Account to an Investment Portfolio

    Transitioning your HSA from a static savings account to an active investment portfolio is easier than most people realize. The process generally involves three distinct steps: evaluating your provider, selecting your investment strategy, and committing to a long-term mindset.

    First, check if your current HSA provider offers an investment platform. Most major financial institutions that manage HSAs now provide the ability to invest funds once a certain threshold is reached—usually $1,000 or $2,000. If your current provider does not offer an investment option or charges excessive fees to do so, you have the right to transfer your funds to a different, more favorable HSA provider. You can typically initiate a trustee-to-trustee transfer, which ensures the process is smooth and tax-efficient.

    Once you have access to an investment portal, you should treat it as you would any other retirement portfolio. Most providers offer a selection of mutual funds and ETFs. For most long-term wealth builders, a low-cost, diversified approach is best. This often involves selecting index funds that track the S&P 500 or a Total Stock Market index, alongside some international exposure. By mimicking the structure of a diversified retirement account, you ensure that your health savings benefit from the same growth trajectory as your traditional wealth-building assets.

    The following table summarizes the different approaches to managing an HSA, highlighting how each fits into a broader wealth-building strategy:

    Approach Primary Focus Risk Level Best For
    Cash Reserve Immediate liquidity for medical bills Very Low Those needing funds for frequent, predictable health costs
    Core Investment Broad-market growth through Index Funds Moderate Savers with a 10+ year time horizon
    Aggressive Allocation Maximizing long-term appreciation via ETFs Moderate to High Investors comfortable with volatility for higher returns

    When setting up your portfolio, be mindful of the fee structure. Some providers charge monthly maintenance fees or trading commissions that can eat into your gains. Opt for providers that offer commission-free trading or low-expense-ratio funds. Once you have moved your funds into these vehicles, set your contributions to auto-invest. This “set it and forget it” approach ensures that every dollar you contribute is immediately put to work. Over time, as your contributions accumulate, your HSA will move from a minor account to a significant piece of your total wealth pie, functioning effectively as a tax-advantaged brokerage account that you can tap into for healthcare later in life.

    The Power of Compound Interest in Tax-Free Healthcare Accounts

    Compound interest is often called the eighth wonder of the world, and there is nowhere it works harder than inside an HSA. Because the growth is entirely tax-free, you are effectively compounding your returns on the *entire* amount of the investment, without the government taking a “slice” each year. In a standard brokerage account, you might pay taxes on dividends or capital gains, which reduces the amount of capital available to reinvest. In an HSA, 100% of your earnings stay in the account to compound further.

    To understand the scale of this, imagine a scenario where you contribute the annual maximum to your HSA over 20 years. If you leave that money in a cash account, you might earn a very small amount of interest, barely outpacing inflation. However, if you invest that money into a diversified growth fund, you benefit from the power of compounding annual returns. Over two decades, the difference between a cash-based approach and an investment-based approach can result in a six-figure disparity in your total balance.

    The power of compound interest becomes even more apparent when you allow your funds to grow untouched during your peak earning years. Because medical expenses often increase as we age, having a large, tax-free pool of capital in your 60s and 70s is a game-changer. It can cover high-deductible health insurance premiums, dental work, vision care, and even long-term care insurance premiums, all without triggering a tax event.

    Moreover, the tax-free status of the withdrawals means that your “purchasing power” is significantly higher than it would be from a traditional 401(k) or IRA. If you withdraw $10,000 from a 401(k) in retirement, you might actually only have $7,500 after income taxes to spend. If you withdraw $10,000 from an HSA, you get the full $10,000. This efficiency makes your HSA dollars arguably more valuable than your other retirement dollars. By prioritizing HSA contributions early in your career, you are essentially creating a “wealth reserve” that serves as a hedge against the rising costs of healthcare, ensuring that your lifestyle in retirement is not compromised by unexpected medical bills. It is a strategic move that requires discipline today but yields immense flexibility and security tomorrow.

    Strategic Ways to Cover Current Medical Expenses Without Tapping HSA Funds

    If the goal is to allow your HSA to grow through long-term investing, you might wonder: “How do I pay for the doctor visit today?” The most effective strategy for the dedicated wealth builder is to pay for current out-of-pocket medical expenses using cash flow from your regular checking or savings accounts, while keeping your receipts.

    This approach is highly beneficial because it allows your HSA investments to stay in the market for as long as possible. By paying out-of-pocket, you treat the HSA as a long-term “emergency fund” for health-related costs that you can tap into decades down the line. The crucial step here is documentation. You do not need to withdraw the money from your HSA immediately to reimburse yourself. The IRS does not impose a “statute of limitations” on when you can reimburse yourself for qualified medical expenses, as long as those expenses were incurred after the HSA was opened.

    You can save your receipts in a digital folder—many apps and cloud storage services make this easy—and simply let the HSA account grow. Then, if you ever face a genuine financial emergency ten, twenty, or thirty years later, you can retroactively reimburse yourself for those past expenses. This provides you with an “on-demand” tax-free withdrawal that can serve as a massive safety net if needed.

    Additionally, this strategy turns your HSA into a flexible planning tool. If you are a high earner, you might prioritize maxing out your HSA contributions because of the immediate tax deduction, while simultaneously paying for day-to-day medical costs using your monthly salary. This preserves your HSA as a pure wealth-building vehicle. If you do not have the cash flow to pay out-of-pocket, that is perfectly fine; you can use the HSA for its intended purpose. But for those aiming to optimize for wealth, treating the HSA as a “last resort” account while investing as much as possible is the gold standard for long-term planning. Over time, you will find that you have a significant balance that serves as a hybrid retirement and medical fund, providing you with incredible peace of mind and financial leverage that most individuals never tap into.

    The Role of HSA Contributions in Tax Planning and Wealth Preservation

    For high-earners and diligent savers, an Health Savings Account (HSA) often functions less like a medical piggy bank and more like a sophisticated tool for long-term wealth preservation. Integrating an HSA into your broader tax planning strategy allows you to lower your adjusted gross income (AGI) while concurrently building a tax-sheltered nest egg. Because contributions are made with pre-tax dollars, every dollar you funnel into your account effectively provides an immediate tax deduction, reducing your taxable income for the current year. This mechanism is particularly powerful for individuals in higher tax brackets, as it creates a direct offset against their highest marginal tax rate.

    Beyond the initial deduction, the wealth preservation aspect of an HSA stems from the ability to keep your capital invested for decades. Unlike a Flexible Spending Account (FSA), which operates on a “use it or lose it” basis, an HSA offers portability and permanence. By covering medical expenses out-of-pocket during your working years and allowing the HSA balance to compound, you are essentially creating a tax-efficient reserve that can be utilized to protect your portfolio during market downturns. Instead of selling taxable assets when you need cash for an unexpected health cost, you can tap into the HSA, preserving your retirement investments for their intended growth trajectory.

    Wealth preservation also involves strategic asset location. By prioritizing HSA contributions, you are parking funds in one of the most tax-advantaged vehicles available in the United States tax code. This creates a defensive layer in your overall financial plan, shielding those assets from the “tax drag” that typically eats into returns in a standard brokerage account. When you consider that money within an HSA grows tax-deferred, and is never taxed upon withdrawal for qualified medical expenses, the long-term impact on your net worth is substantial.

    Comparing HSA Investment Growth to Traditional Retirement Accounts

    To understand why the HSA is often cited by experts as the ultimate retirement account, it is helpful to contrast it with traditional vehicles like the 401(k) and the Traditional IRA. While the 401(k) and IRA are excellent, they have specific limitations regarding taxation. With a 401(k), you benefit from tax-deferred growth, but your withdrawals during retirement are taxed as ordinary income. In contrast, the HSA provides a triple tax advantage that no other account type can replicate: tax-deductible contributions, tax-free investment growth, and tax-free withdrawals for medical costs.

    The following table illustrates how the HSA stacks up against other common investment vehicles in terms of tax structure and flexibility.

    Account Type Tax Deduction Tax Growth Tax-Free Withdrawal Best For
    HSA Yes Yes Yes (Medical) Triple-Tax Advantage & Healthcare
    Traditional 401(k) Yes Yes No (Taxed as income) High-earner employer matching
    Roth IRA No Yes Yes (General) Long-term wealth building
    Brokerage Account No No Capital Gains Tax Short to medium-term liquidity

    The flexibility of the HSA is a key differentiator. While a 401(k) or IRA forces you into a specific distribution strategy at age 73 (required minimum distributions), the HSA has no such mandate. You can allow the funds to grow indefinitely, or you can leverage them to cover medical expenses during retirement—a period when healthcare costs are typically the single largest expenditure for retirees. By maximizing your HSA, you are effectively creating a private “healthcare pension” that subsidizes your retirement lifestyle, allowing your other taxable retirement accounts to remain untouched for longer.

    Maximizing Long-Term Returns Through Low-Cost Index Fund Allocation

    Once you have moved your HSA balance beyond the cash-reserve threshold—typically keeping three to six months of medical costs in liquid savings—you should pivot toward an investment-focused strategy. The primary engine for HSA wealth building is the consistent, long-term compounding of market-based assets. Given the multi-decade time horizon associated with HSA investing, a diversified portfolio of low-cost index funds is often the most prudent choice for many investors.

    Investors should prioritize funds with low expense ratios, such as total stock market index funds or broad-market ETFs. Because HSAs are meant to be held for long periods, high fees can create a significant headwind against your total returns. Even a one-percent difference in annual fees can equate to thousands of dollars in “lost” potential growth over a twenty-year period. By sticking to passive, low-cost instruments, you ensure that the bulk of your investment returns remain in your account rather than going toward fund management fees.

    Furthermore, consider your asset allocation based on your personal risk tolerance and your “HSA horizon.” If you do not intend to touch the funds until age 65, you can afford to hold a higher concentration of equities. As you approach your actual retirement date, you may choose to shift toward a more conservative allocation, incorporating bonds or money market funds to preserve the principal you have painstakingly built over the years. This cycle of aggressive growth in the early years followed by capital preservation in the later years is the blueprint for successful long-term wealth creation.

    Critical Rules for HSA Distributions and Penalty-Free Withdrawal Strategies

    Understanding the rules of the HSA is essential to avoiding costly penalties. The most critical rule to remember is that withdrawals are only tax-free when used for “qualified medical expenses” as defined by the IRS. These can include everything from doctor’s visits and prescription medications to vision and dental care, and even certain over-the-counter items. Keep meticulous digital records of these receipts; even if you do not reimburse yourself immediately, these receipts create a permanent “bank” of expenses that you can draw against years later.

    One of the most powerful strategies for wealth building involves the concept of “deferred reimbursement.” Instead of paying for medical bills using HSA funds immediately, many high-net-worth investors pay out-of-pocket using taxable funds. They save the receipts in a cloud-based folder. This allows their HSA to remain fully invested and growing. Because the IRS does not set a deadline for when you must reimburse yourself for a medical expense, you could theoretically pay for a surgery in 2024 and withdraw the funds from your HSA in 2044. This strategy allows your HSA to function as a tax-free investment account that you can tap into for non-medical reasons—if you have the documentation to prove the expenses occurred years prior.

    If you withdraw funds from an HSA for non-medical reasons before age 65, you will typically be subject to both income tax and a 20% penalty. However, after age 65, the penalty disappears. At that point, you can withdraw funds for any purpose—medical or otherwise—and simply pay ordinary income tax on the distribution. In this scenario, the HSA effectively becomes a traditional IRA. The foresight to avoid non-medical withdrawals during your younger years is what separates the casual HSA holder from the wealth-builder.

    Frequently Asked Questions

    Can I invest my HSA funds in individual stocks?

    Most HSA providers allow you to invest your funds in a variety of assets, including stocks, bonds, and mutual funds, once your account reaches a specific balance threshold. While individual stocks are an option, financial experts generally suggest focusing on diversified index funds to manage risk over the long term.

    What happens to my HSA if I change employers?

    The HSA is your account, not your employer’s. If you leave your job, your HSA stays with you. You can roll it over to a new provider, maintain it with your current one, or transfer it to an institution of your choice. You never lose the funds you have contributed, regardless of your employment status.

    Do I have to reimburse myself for medical expenses in the same year they occur?

    No, there is no IRS time limit on when you must reimburse yourself for qualified medical expenses. As long as you have the receipt and proof that the expense was incurred after your HSA was opened, you can keep the money invested and reimburse yourself at any point in the future, even decades later.

    What are considered qualified medical expenses?

    Qualified medical expenses generally cover costs related to the diagnosis, cure, mitigation, treatment, or prevention of disease. This includes medical, dental, and vision services, prescription drugs, and even certain medical equipment. You can find a comprehensive list of eligible expenses in the IRS Publication 502.

    Can I use my HSA funds for my spouse or dependents?

    Yes, you can use your HSA funds tax-free to cover the qualified medical expenses of your spouse and any dependents you claim on your tax return, even if they are not covered by your specific High Deductible Health Plan. This makes the HSA an excellent tool for managing family healthcare costs.

    Is there a maximum amount I can contribute to my HSA annually?

    Yes, the IRS sets annual contribution limits for both individual and family coverage, which are adjusted periodically for inflation. Individuals age 55 and older are also eligible to make an additional “catch-up” contribution each year, which further accelerates your ability to build significant wealth within the account.

    Conclusion

    Building wealth through an HSA is one of the most effective, yet often underutilized, strategies available to modern savers. By viewing your health account not merely as a tool for today’s medical bills, but as a long-term engine for tax-advantaged growth, you can secure a significantly more stable financial future. The combination of immediate tax deductions, tax-free compounding, and tax-free withdrawals for future healthcare costs creates a unique value proposition that is difficult to find elsewhere.

    The path to success is straightforward: contribute as much as possible, keep your funds invested in low-cost assets, and hold your receipts for long-term flexibility. Start optimizing your HSA contributions today and treat your healthcare savings as a critical cornerstone of your holistic wealth strategy. Your future self will thank you for the diligence and discipline you apply now.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Can You Tax-Loss Harvest in IRAs and 401ks? The Truth

    Can You Tax-Loss Harvest in IRAs and 401ks? The Truth

    Key Takeaways

    • Tax-loss harvesting is exclusively a strategy for taxable brokerage accounts, not tax-advantaged retirement accounts.
    • IRAs and 401ks operate under different tax rules that negate the concept of capital losses.
    • The IRS Wash Sale Rule prohibits claiming a loss if you buy a “substantially identical” security within 30 days.
    • Attempting to claim losses within tax-advantaged accounts is not only ineffective but can result in audit triggers.
    • Focusing on asset allocation and long-term wealth building is the most effective approach for retirement portfolios.

    When investors begin to master the art of investment tax planning, they often encounter the powerful strategy of tax-loss harvesting. It is a common point of confusion for many—especially those new to personal finance—whether this strategy can be applied across all investment vehicles. If you are looking to maximize your wealth, you might wonder if you can harvest losses in your IRA or 401k to offset gains elsewhere. The short answer is no, but understanding the “why” behind this rule is essential for any disciplined investor. In this guide, the wealthsimplyput editorial team breaks down the mechanics of tax-advantaged accounts and why the IRS draws a firm line between taxable and tax-deferred investment strategies.

    How Tax-Loss Harvesting Works in Taxable Brokerage Accounts

    Tax-loss harvesting is a fundamental tool for investors seeking to optimize their after-tax returns. At its core, the strategy involves selling an investment that has declined in value to realize a capital loss. You can then use this realized loss to offset capital gains realized during the same tax year. If your losses exceed your gains, you may be able to use the excess loss to offset a limited amount of your ordinary income, providing a meaningful boost to your overall tax efficiency.

    In a standard, taxable brokerage account, the IRS views every sale of an asset as a taxable event. When you buy a stock for $1,000 and sell it for $800, you have a $200 capital loss. Under current investment tax planning guidelines, that $200 can be used to “cancel out” $200 of capital gains from other successful trades. If you have no gains to offset, you can apply up to a specific annual limit of those losses against your ordinary income, such as your salary. Any remaining losses can typically be carried forward to future tax years, acting as a permanent asset that helps manage your future tax bill.

    The beauty of this process in a taxable account is that it does not necessarily mean you have to abandon your market position. After selling a losing security to lock in the tax benefit, many investors immediately reinvest the proceeds into a similar—though not “substantially identical”—asset. This allows you to stay invested in the market while simultaneously lowering your tax liability. This strategy requires careful monitoring, as failing to adhere to the nuances of market timing and the wash sale rule can undermine the entire effort.

    For high-net-worth individuals or those simply focused on efficient wealth building, tax-loss harvesting acts as a drag-reduction mechanism. Over several years, the cumulative tax savings can be reinvested, compounding over time to enhance the growth of your portfolio. It is not about “gaming” the system, but rather about using the inherent rules of the tax code to keep more of your investment earnings. However, this strategy is entirely dependent on the existence of a taxable event. When we transition into the world of tax-advantaged accounts, the entire premise changes, as the “taxable event” definition disappears entirely. Understanding this distinction is the single most important step in protecting your retirement savings from unintentional tax errors.

    Understanding the Tax Structure of IRAs and 401ks

    To grasp why tax-loss harvesting does not apply to IRAs and 401ks, one must first understand the purpose and tax structure of these vehicles. These accounts were designed by the government to incentivize long-term savings by providing a “tax-advantaged” environment. The trade-off for these benefits is that the rules governing these accounts are distinct from those governing a personal brokerage account.

    In a traditional 401k or Traditional IRA, contributions are typically made with pre-tax dollars, and the investments grow tax-deferred. You do not pay capital gains tax on the dividends or the appreciation of assets within the account as you trade them. Because there is no capital gains tax on the growth within the account, there is—by extension—no capital loss to harvest. You cannot offset a gain that was never taxed in the first place. The IRS does not view the buying and selling of funds inside your 401k as a taxable event; instead, the tax obligation is deferred entirely until you withdraw the funds in retirement.

    Roth IRAs and Roth 401ks operate differently, where contributions are made with after-tax dollars, but qualified withdrawals are tax-free. In this structure, the IRS essentially removes the concept of capital gains taxation from the equation altogether. Because the growth is never taxed, the government does not allow investors to claim losses on investments that happen to decline in value within these accounts. The tax benefits of these accounts are meant to be a permanent “shield” for your wealth, but that shield works in both directions: it protects your gains from taxation, but it also prevents you from utilizing losses to lower your tax bill elsewhere.

    When you look at your 401k investment strategy, your focus should shift away from tax efficiency through harvesting and toward asset allocation and compounding. Because you are not paying taxes on the internal turnover of your retirement funds, you can rebalance your portfolio as often as you like without triggering a tax bill. This is a massive advantage that is often overlooked. While you cannot harvest losses, you are granted the freedom to manage your retirement assets aggressively to suit your risk tolerance and long-term wealth building goals without the constant “tax friction” found in personal brokerage accounts.

    Account Type Taxation on Gains Loss Harvesting Possible? Best For
    Taxable Brokerage Capital gains taxed annually Yes Short-term and long-term liquidity
    Traditional IRA/401k Taxed upon withdrawal No Tax-deferred wealth growth
    Roth IRA/401k Tax-free upon withdrawal No Long-term tax-free compounding

    Why You Cannot Apply Tax-Loss Harvesting to Retirement Accounts

    The primary reason you cannot apply tax-loss harvesting to retirement accounts is that capital gains and losses are fundamentally non-existent within the eyes of the IRS when they occur inside those tax-advantaged walls. In a taxable brokerage account, the government is a silent partner that takes a cut of your profits and, in exchange, shares a portion of your losses. In an IRA or 401k, the government is not your partner; it is either a creditor (in the case of Traditional accounts) or it is entirely absent (in the case of Roth accounts).

    When you hold a volatile asset in an IRA and it drops in value, that drop is simply a decrease in your account balance. Because you never paid capital gains tax on that investment, there is no corresponding tax credit to claim. Trying to “harvest” that loss would essentially be a request for a tax deduction on money that was never taxed in the first place. The IRS code is built on the principle of symmetry: if they don’t tax the upside, they won’t grant a deduction on the downside.

    Furthermore, the administrative structure of retirement accounts is designed to simplify tax reporting. If the IRS allowed individual investors to report capital gains and losses on every single transaction within their 401k, the compliance and reporting burden would be astronomical. By keeping these accounts “tax-neutral” during the accumulation phase, the government ensures that retirement saving remains an accessible vehicle for the general population. If you were permitted to harvest losses in your 401k, you would essentially be creating a “double benefit” where you already received a deduction for the contribution, and then you would be asking for another deduction for the loss of the investment itself.

    Most experts emphasize that once you fund your retirement accounts, you should view them through the lens of long-term wealth building rather than immediate tax mitigation. The loss of a tax-harvesting strategy is not a “penalty” for using an IRA; it is a trade-off for the decades of tax-deferred or tax-free growth that those accounts provide. If you are experiencing significant losses in your retirement account, the solution is not to look for tax harvesting, but rather to evaluate your 401k investment strategy to ensure your current risk level matches your retirement timeline.

    The IRS Wash Sale Rule Explained for Investors

    To truly understand why you cannot harvest losses in IRAs or 401ks, you must also understand the IRS Wash Sale Rule. This rule was established to prevent investors from selling a security just to claim a tax loss and then immediately buying it back to maintain their market position. The rule states that if you sell a security at a loss and purchase a “substantially identical” security within 30 days before or after the sale, the loss is disallowed for tax purposes.

    This rule extends to all accounts you own, including your spouse’s accounts and your IRAs. This is a critical area where many well-intentioned investors accidentally run into trouble. If you sell a fund at a loss in your taxable brokerage account to trigger a tax deduction, and then buy that same fund inside your IRA a week later, the IRS considers this a “wash sale.” The loss in your taxable account will be disallowed because, for all intents and purposes, you didn’t actually “lose” your position in that security—you just moved it into your IRA.

    The “substantially identical” aspect of the rule is intentionally broad. While the IRS does not provide a rigid definition for every single scenario, it generally includes the exact same ticker symbol, funds that track the same index, or options contracts that mirror the security. Because the IRS monitors these transactions, moving assets between your personal portfolio and your tax-advantaged accounts in a way that mimics a wash sale can result in a disallowed loss. This is why investment tax planning professionals often advise maintaining a distinct separation between the strategies you use in your taxable brokerage account and the holdings you maintain in your retirement accounts.

    If you trigger a wash sale, you do not lose the benefit of the loss forever; rather, the disallowed loss is added to the “cost basis” of the new security you purchased. This effectively pushes the tax benefit into the future, until the time when you eventually sell the new security. However, this complicates your record-keeping significantly. For most investors, the easiest way to avoid this headache is to simply be aware of what you are buying across all your accounts simultaneously, ensuring that your 401k investment strategy and your taxable portfolio are not inadvertently creating “wash” scenarios that complicate your annual tax filing.

    Consequences of Attempting to Claim Losses in Tax-Advantaged Accounts

    Attempting to force the mechanics of tax-loss harvesting into your 401k or IRA is not merely ineffective; it is technically impossible and potentially dangerous for your overall tax compliance. When you fill out your tax returns, you report capital gains and losses using specific IRS forms that are strictly tied to your taxable brokerage activities. Attempting to report transactions from a tax-advantaged account as if they were taxable events is a red flag that can invite scrutiny from the tax authorities.

    The first consequence is the most immediate: the IRS will simply disallow the claim. Because retirement accounts operate under a specific tax-exempt or tax-deferred status, the brokerage firm or financial institution managing your IRA does not issue a 1099-B—the tax form used to report capital gains and losses—for your internal transactions. If you try to manually report a loss from an account that generated no such tax paperwork, you create a discrepancy between what your financial institution reports to the IRS and what you report on your personal return.

    Discrepancies of this nature are a common trigger for automated audits. Even if your intentions were innocent and you were simply trying to lower your taxes, the IRS may view this as an attempt to evade taxes or improperly claim deductions. The result is often a prolonged and stressful audit process where you have to prove that the “loss” was legitimate, only to find that it was never a claimable event in the first place. The energy and time spent resolving these issues far outweigh any potential tax savings you might have erroneously calculated.

    Beyond the legal consequences, there is the opportunity cost. When you obsess over tax-loss harvesting in an environment where it cannot function, you neglect the broader, more effective strategies for wealth building. Instead of worrying about harvesting losses in a 401k, the most successful investors spend that time refining their asset allocation, rebalancing their portfolio based on their target risk profile, and ensuring their contribution levels are optimized to capture any employer matching funds. The best approach is to accept the limitations of tax-advantaged accounts as part of the price of admission for the tax-deferred growth they provide. Leave the tax-loss harvesting to your taxable brokerage accounts, and focus your retirement accounts on long-term, compounding growth.

    Strategic Asset Location: Where to Hold Your Winning and Losing Assets

    Strategic asset location is one of the most effective levers in long-term wealth building, yet it is frequently misunderstood. While tax-loss harvesting is a tactic reserved for taxable brokerage accounts, asset location is the broader strategy of placing specific investments into the account types where they will be most tax-efficient. This practice minimizes the “tax drag” on your portfolio, allowing your wealth to compound more effectively over time.

    In a taxable account, you have the flexibility to harvest losses to offset capital gains. Because this mechanism does not exist within IRAs or 401ks, your focus in these accounts should shift entirely to minimizing the tax burden of the underlying assets. Assets that generate significant taxable events—such as high-turnover funds, actively managed mutual funds, or bonds that pay regular interest—are often better suited for tax-advantaged accounts. Conversely, assets that benefit from preferential tax treatment, such as long-term capital gains or qualified dividends, are generally better held in taxable accounts where you have more control over the timing of the tax event.

    When you hold a “losing” asset in a tax-advantaged account, you essentially lose the ability to harvest that loss to lower your tax bill. Therefore, you should avoid placing highly volatile or speculative assets in your IRA if you believe they have a high probability of needing to be harvested for tax purposes. Instead, prioritize placing high-growth assets or interest-heavy assets in these accounts. By keeping your dividend-paying stocks and short-term bond funds inside your 401k or IRA, you shield the annual interest and dividend distributions from immediate taxation, effectively creating a tax-deferred wrapper that preserves more of your wealth.

    Asset location requires a holistic view of your entire financial picture. You are not just managing an IRA or a 401k in isolation; you are managing a total portfolio. By coordinating your holdings across all accounts, you ensure that every dollar is working toward wealth accumulation while minimizing the total leakage to the government.

    How Capital Gains Differ Between Traditional and Roth Accounts

    Understanding the distinction between Traditional and Roth accounts is essential for effective investment tax planning. Many investors assume that because both accounts are “tax-advantaged,” they function identically regarding capital gains. However, the tax treatment of gains varies significantly depending on the account type and the timing of withdrawals.

    In a Traditional IRA or 401k, the funds are contributed pre-tax (or tax-deductible). Because of this, the government has not yet taken its share. Consequently, when you withdraw money in retirement, the entire amount—including the original principal and all the capital gains earned over the years—is taxed as ordinary income. The IRS does not distinguish between capital gains and earned income inside a Traditional account; it is all treated as a distribution of untaxed wealth.

    Roth accounts function differently. You contribute after-tax dollars to a Roth IRA or Roth 401k. Because you have already paid taxes on that money, the growth is tax-free. When you reach retirement age and meet the “qualified distribution” requirements, your capital gains are not just tax-deferred—they are tax-exempt. This is a massive advantage for long-term wealth building, as your portfolio could double or triple in value without incurring a single penny of federal income tax upon withdrawal.

    This fundamental difference changes how you should view “losses” in these accounts. In a taxable account, a loss is a tool to offset gains. In a Traditional account, a loss is simply a reduction in your future taxable income. In a Roth account, a loss is a tragic waste of potential tax-free growth. Because Roth space is so valuable, you generally want to hold your highest-growth assets there. Losing money in a Roth account is effectively losing out on the highest potential for tax-free compounding, which is why risk management in a Roth IRA is of paramount importance.

    Account Type Taxation on Gains Harvesting Losses Best For
    Taxable Brokerage Taxed as realized Yes (Tax-Loss Harvesting) Long-term stock holdings
    Traditional IRA/401k Taxed as Ordinary Income No Bonds & High-turnover funds
    Roth IRA/401k Tax-Free No Aggressive Growth Assets

    Best Practices for Managing Investments Across Multiple Accounts

    Managing multiple retirement accounts alongside taxable brokerage accounts can feel like a logistical nightmare. However, by establishing a disciplined system, you can maintain a coherent investment tax planning strategy that promotes wealth accumulation. The first step is to view your total assets as a single, unified portfolio rather than a collection of separate accounts.

    A “hub-and-spoke” model is often the most effective approach. Your core asset allocation (e.g., 70% equities, 30% bonds) should be maintained across your entire net worth. If your target is 70/30, you do not need 70% stocks in every single account. Instead, place your bond allocation primarily in your Traditional IRA or 401k, where the interest payments are protected from immediate taxation. Place your tax-efficient equity index funds in your taxable account, which allows you the flexibility to harvest losses during market downturns. Finally, allocate your highest-growth, high-conviction stocks to your Roth accounts to maximize the tax-free appreciation potential.

    Rebalancing is the second piece of the puzzle. Over time, market performance will shift your percentages, causing your portfolio to drift from your original targets. Instead of selling assets in your taxable account—which triggers capital gains taxes—rebalance by selling assets inside your IRA or 401k. Because these accounts are tax-shielded, you can shift funds from stocks to bonds (or vice-versa) without worrying about tax consequences. This allows you to “sell high” and “buy low” to reset your targets while keeping your tax bill as close to zero as possible.

    Finally, keep a master ledger or use an automated aggregation tool to track your total exposure. If you do not know exactly what you own across all platforms, you cannot effectively plan for taxes. Consistency is key; review your allocations once or twice a year to ensure your strategy remains aligned with your long-term wealth goals.

    The Role of Tax-Efficient Investing Without Loss Harvesting

    While tax-loss harvesting is a popular topic in investment tax planning, it is only one tool in the shed. Many investors focus so heavily on harvesting losses that they overlook the more impactful strategy: tax-efficient investing. If you design your portfolio correctly from the outset, you will have significantly fewer taxable events to worry about in the first place.

    The primary driver of tax-efficient investing is the use of broad-market index funds and Exchange-Traded Funds (ETFs). Unlike actively managed mutual funds, which often engage in high turnover—buying and selling stocks frequently to try to “beat the market”—index funds simply track a benchmark. This strategy typically results in fewer capital gains distributions, which are the hidden tax-killer for many brokerage accounts. When a fund manager realizes a capital gain, they pass the tax liability on to the shareholders, even if those shareholders haven’t sold their own shares. By choosing low-turnover index vehicles, you prevent these “surprise” tax bills from eroding your wealth.

    Another component of tax-efficient investing is the holding period. The tax code rewards long-term investors through lower long-term capital gains rates compared to short-term rates. By simply adopting a “buy and hold” philosophy, you automatically become more tax-efficient. Every time you sell an asset, you lose the power of compounding on the taxes you just paid to the government. Staying invested for years or decades, rather than months, keeps more money in your account to grow exponentially.

    Finally, consider the use of municipal bonds for your taxable accounts if you are in a higher tax bracket. The interest generated by municipal bonds is typically exempt from federal income taxes (and sometimes state taxes, depending on where you reside). By shifting your bond allocation to tax-free municipal debt in your taxable account, you can keep your IRA/401k space open for assets that generate ordinary income, further optimizing your total tax efficiency.

    When to Consult a Financial Advisor for Complex Tax Planning

    While the principles of wealth building and tax efficiency are straightforward, individual circumstances can become complex. There are specific milestones and scenarios where the “do it yourself” approach may no longer be sufficient. Consulting a qualified financial professional or a Certified Public Accountant (CPA) is advisable when the complexity of your financial life outweighs the simplicity of your investment strategy.

    One major trigger for seeking professional help is a transition in your tax bracket or income structure. If you are starting a business, receiving significant equity compensation, or nearing retirement, your tax strategy needs to shift. For instance, planning for a “Roth conversion ladder” to lower your future tax burden requires precise calculations to ensure you do not inadvertently push yourself into a higher tax bracket or trigger unwanted penalties.

    Inheritances and estate planning represent another critical juncture. When you inherit an IRA, the rules regarding Required Minimum Distributions (RMDs) become significantly more complicated. Missing an RMD or failing to properly structure a tax-advantaged account transfer can lead to severe IRS penalties that far outweigh the cost of a professional consultation. If your net worth has reached a level where tax-efficient wealth transfer or complex gifting strategies are involved, it is time to move beyond general strategies and into bespoke planning.

    Lastly, if you find that you are spending more time worrying about the potential tax implications of your trades than you are focused on your actual life or business, it may be time to delegate. A financial advisor who specializes in tax-efficient wealth management provides not only technical expertise but also the peace of mind that comes from knowing your assets are structured correctly. They act as a partner in your long-term success, helping you navigate the complexities of shifting tax laws so that you can remain focused on your primary career and personal goals.

    Frequently Asked Questions

    Can I perform a wash sale if I buy the same stock in my IRA that I sold in my taxable account?

    Yes. The IRS wash sale rule specifically includes transactions within your IRA. If you sell a security at a loss in a taxable account and purchase the same or a “substantially identical” security in your IRA within 30 days before or after that sale, the loss is disallowed. Furthermore, unlike in a taxable account, you cannot simply add the disallowed loss to the cost basis of the shares in the IRA. The tax benefit of that loss is effectively lost permanently.

    What happens if I accidentally trigger a wash sale in my 401k?

    If you trigger a wash sale in a 401k or IRA, the loss is disallowed for tax purposes. Because you cannot adjust the basis of assets held within a tax-advantaged account, the tax deduction you were hoping to claim is simply negated. It is a costly mistake that underscores the importance of monitoring all your accounts collectively, rather than assuming that your tax-advantaged accounts exist in a separate vacuum where the wash sale rule does not apply.

    Are there any exceptions to the wash sale rule for IRAs?

    The IRS is quite clear on this: the wash sale rule applies to all accounts, including IRAs and Roth IRAs. There are no notable exceptions for these accounts. If you engage in a “substantially identical” trade across any of your accounts, including those held at different brokerages, the IRS treats it as a wash sale. Always wait the required 31-day period to be safe.

    Is it ever smart to harvest a loss and then buy an asset that is “similar” but not “substantially identical”?

    Yes, this is a common strategy used to maintain market exposure while still capturing the tax benefit. For example, if you sell an S&P 500 index fund at a loss, you might immediately buy a total stock market index fund. While both track the U.S. market, they are typically considered different enough by the IRS to avoid the “substantially identical” label. However, always exercise caution, as the IRS has not provided a definitive list of what constitutes “substantially identical,” so avoid anything too similar.

    Should I prioritize tax-loss harvesting over other investment goals?

    Tax-loss harvesting is a useful tool, but it should never override your core investment strategy. Never let the “tax tail” wag the “investment dog.” If you are selling an asset simply to generate a loss, but that asset is one you believe has long-term growth potential, you may be doing more harm than good by exiting a winning position. Focus on long-term wealth building, and use tax-loss harvesting only when it aligns with your broader financial plan.

    Can I harvest losses in a 401k if I’m leaving my employer?

    No. Leaving an employer and rolling your 401k into an IRA or another 401k does not create a taxable event that allows for loss harvesting. The internal movements within a 401k or an IRA are always tax-deferred, regardless of whether you are changing jobs, changing providers, or rebalancing your asset allocation. The tax status of these accounts remains intact throughout the transition.

    Conclusion

    Mastering the complexities of tax-advantaged accounts is a vital component of successful wealth building. While the temptation to “harvest” losses inside an IRA or 401k is understandable, the IRS rules governing these accounts are strict, and attempting to do so will almost certainly result in a disallowed loss and unnecessary administrative headaches. Instead, your success should be built on the bedrock of strategic asset location, long-term tax-efficient investing, and a disciplined approach to managing your total portfolio as one cohesive unit.

    By keeping your taxable events in your brokerage account and utilizing your retirement accounts for their intended purpose of tax-deferred or tax-free growth, you maximize the efficiency of every dollar you earn. Remember that wealth is not just about what you make, but what you keep after taxes and inflation have taken their share. Take the time to audit your current holdings, ensure your asset location aligns with your tax bracket, and stay committed to the long-term vision of your financial future.

    Ready to take full control of your financial destiny? Start by auditing your portfolio today to ensure your assets are in the right accounts. For more expert insights on growing your net worth, subscribe to our newsletter and keep building your wealth with confidence.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Tax-Loss Harvesting: How to Lower Taxes and Build Wealth

    Tax-Loss Harvesting: How to Lower Taxes and Build Wealth

    Key Takeaways

    • Tax-loss harvesting is a strategic method to offset capital gains by selling underperforming assets to reduce your overall tax bill.
    • Properly managing your brokerage account taxes is a fundamental component of long-term wealth building strategies.
    • The IRS wash-sale rule prohibits claiming a loss if you purchase a “substantially identical” security within 30 days before or after the sale.
    • Focusing on tax efficiency allows investors to keep more of their earnings, accelerating the compounding process over time.
    • A disciplined approach to harvesting losses requires careful record-keeping and a deep understanding of your specific investment goals.

    Investing in the stock market is one of the most reliable vehicles for long-term wealth building, yet many investors inadvertently surrender a significant portion of their returns to the tax collector. While you cannot control the volatility of the markets, you can exercise significant control over your tax liability. Tax-loss harvesting is a sophisticated yet accessible financial maneuver that allows you to transform investment losses into a tangible tax benefit. By strategically selling securities that have declined in value, you can reduce your capital gains tax, optimize your portfolio’s tax efficiency, and keep more capital working for your future. This guide provides an authoritative look at how to navigate these complex regulations to protect your assets and grow your net worth.

    What Is Tax-Loss Harvesting and How Does It Work

    Tax-loss harvesting is an investment strategy that involves selling securities at a loss to offset the taxes you owe on capital gains. When you sell an asset in a taxable brokerage account for more than you paid for it, you realize a capital gain, which is generally subject to taxation. Conversely, if you sell an asset for less than its original purchase price, you realize a capital loss. Tax-loss harvesting allows you to use those realized losses to mitigate the impact of your realized gains, thereby lowering your overall brokerage account taxes.

    The mechanics of this strategy are relatively straightforward, though they require strict attention to detail. Imagine you hold two stocks: Stock A, which has gained significant value, and Stock B, which has dropped in value. If you sell Stock A to rebalance your portfolio, you will owe taxes on that profit. However, if you simultaneously sell Stock B, you can use that loss to offset your gain from Stock A. If your losses exceed your gains in a given tax year, you are generally permitted to use up to a specific amount of the excess loss to offset your ordinary income, with any remaining loss carried forward to future tax years. This carry-forward feature is a powerful tool in wealth building strategies, as it provides a multi-year buffer against future tax liabilities.

    The core philosophy behind tax-loss harvesting is to increase tax efficiency. By reducing the drag of taxes on your portfolio, you leave more money invested in the market, allowing it to compound over a longer horizon. Many investors mistakenly view losses solely as failures; however, in a tax-advantaged framework, an investment loss can be repurposed as a valuable tax asset. It is important to remember that this strategy only applies to taxable accounts. Retirement accounts like IRAs or 401(k)s do not provide the same tax-loss harvesting opportunities because those accounts are already tax-deferred or tax-free, and you cannot write off losses incurred within them.

    To implement this effectively, investors typically review their portfolios periodically—sometimes monthly or quarterly—to identify unrealized losses. When the market experiences a downturn, it often creates “harvesting” opportunities. By capturing these losses while the market is down, you effectively reset the cost basis of your portfolio while maintaining your market exposure. The goal is not to abandon an investment philosophy, but to maintain your target asset allocation while optimizing the tax consequences of the journey. This proactive management separates passive investors from those who are intentional about wealth preservation and growth.

    Understanding Capital Gains and Tax Liability

    To master tax-loss harvesting, you must first understand how the IRS categorizes investment outcomes. Capital gains are divided into two main buckets: short-term and long-term. A short-term capital gain arises from the sale of an asset held for one year or less, and it is typically taxed at the same rate as your ordinary income. Because ordinary income tax rates are often higher than capital gains rates, these gains can be particularly burdensome on your wealth.

    Long-term capital gains, conversely, apply to assets held for more than one year. These enjoy preferential tax rates, which are typically lower than standard income tax brackets. Understanding the distinction between these two is critical for effective tax planning. When you engage in tax-loss harvesting, you generally must use your losses to offset gains of the same type first. For example, short-term losses are applied against short-term gains, and long-term losses against long-term gains. If one category results in a net loss, it can then be applied against the other category’s net gain. This hierarchy is essential for calculating your precise tax liability.

    The impact of brokerage account taxes on your wealth should not be underestimated. Even a difference of one or two percentage points in tax efficiency can translate into tens of thousands of dollars in lost compounding potential over several decades. When you pay taxes, you are not just losing the amount paid; you are losing the future growth that money would have generated. This is the “opportunity cost” of taxes. By using tax-loss harvesting to reduce capital gains tax, you are essentially reinvesting money that would have otherwise left your portfolio.

    Furthermore, tax liability can fluctuate based on your total annual income. Higher earners may face additional taxes, such as the Net Investment Income Tax (NIIT), which adds another layer of complexity to investment planning. Because these rules are nuanced and depend on your specific financial profile, investors often look to tax-loss harvesting as a defensive strategy. It is not about timing the market, but rather about managing the consequences of market fluctuations. By staying informed about how your gains and losses interact, you can make more strategic decisions about when to buy, hold, or sell, ensuring that your wealth building strategies remain robust regardless of macroeconomic shifts.

    Approach Strategy Focus Best For
    Manual Harvesting Self-directed trades based on account monitoring Active, hands-on investors
    Automated Robo-Advisors Algorithmic, daily monitoring of losses Passive, “set-it-and-forget-it” investors
    Tax-Loss Harvesting Funds Institutional management of tax-efficient baskets High-net-worth individual portfolios

    Step-by-Step Guide to Executing a Tax-Loss Trade

    Executing a tax-loss trade is a deliberate process that involves more than just clicking the “sell” button. To effectively leverage this strategy, you must approach it with a clear roadmap. The first step is to audit your portfolio for unrealized losses. Most modern brokerage platforms offer a “tax lot” view that displays your cost basis—the original price paid for an asset—alongside its current market value. If the current value is lower than your cost basis, you have an unrealized loss candidate.

    Once you identify an asset to sell, the second step is to confirm that you have sufficient capital gains to offset. If your goal is simply to harvest a loss to carry forward into future years, you do not necessarily need current-year gains, but be mindful of the annual deduction limit. The third step is the sale itself. You will place a sell order for the position, ensuring you select the specific tax lot (often through “specific identification” or “spec-id” settings) that maximizes your loss. This allows you to sell the shares you purchased at the highest price, creating the largest possible loss for tax purposes.

    After the sale, you must adhere to the 30-day window required by the IRS wash-sale rule. Many investors find it helpful to replace the sold security with a “substitute” to maintain their market presence. For example, if you sell a large-cap S&P 500 ETF, you might immediately purchase a different ETF that tracks a similar, but not identical, index. This ensures you do not miss out on market rallies while you wait out the required period. This “buy-the-replacement” step is vital because the primary goal of the transaction is tax efficiency, not moving to cash.

    Documentation is the final, and perhaps most critical, step. You must keep accurate records of your original purchase price, the date of the loss harvest, the date of the replacement trade, and the cost basis of the new security. While your brokerage will provide 1099-B forms, having your own organized ledger ensures that you can verify the math when filing your tax returns. Consistency is key here; frequent, small-scale harvesting often yields better results over time than waiting for a single large market correction. By turning the act of selling a losing position into a structured, repetitive process, you minimize your capital gains tax and refine your path toward long-term wealth.

    Avoiding the Wash-Sale Rule: Essential IRS Compliance

    The wash-sale rule is the most significant hurdle for investors practicing tax-loss harvesting. The IRS implemented this regulation to prevent taxpayers from claiming a tax benefit while maintaining their investment position. Under current tax code, a wash sale occurs if you sell a security at a loss and purchase a “substantially identical” security within 30 days before or after the sale. If a wash sale is triggered, the loss is disallowed for the current tax year, and the amount of that disallowed loss is instead added to the cost basis of the new, replacement security.

    While the IRS does not provide a definitive, narrow legal definition for “substantially identical,” the financial community generally interprets this to mean securities that are virtually interchangeable. Buying the exact same stock is clearly a wash sale. Buying a different ETF that tracks the exact same index with the exact same fee structure and holdings can also be viewed as substantially identical. To remain compliant, investors often swap between asset classes or indices that provide similar exposure without being direct clones. For instance, swapping between a fund tracking the S&P 500 and one tracking a total stock market index is often viewed as sufficiently different by most tax professionals, as the underlying compositions vary.

    The 30-day window is unforgiving. It spans 61 days in total: the 30 days before the sale, the day of the sale, and the 30 days following the sale. If you unknowingly purchase the same security within any of those days—perhaps through an automated dividend reinvestment plan—the rule is triggered. This is a common pitfall. Many investors forget that dividends automatically reinvested in the same security can trigger a wash sale, effectively canceling out the tax benefit of their recent harvest. To avoid this, you should disable dividend reinvestment for any security you are actively harvesting until you are confident the 30-day window has closed.

    Staying compliant requires vigilance. It is rarely worth the risk to “game” the system. If you are ever unsure whether a replacement security is substantially identical, err on the side of caution. Using different indices, or choosing securities from different providers that hold slightly different underlying assets, provides a layer of safety. The goal of tax-loss harvesting is to reduce tax drag; triggering an IRS audit or a disallowed deduction creates more complexity and stress than the strategy is worth. By understanding the boundaries of the wash-sale rule, you can confidently build wealth without violating the regulatory environment that governs your investments.

    Identifying Suitable Assets for Tax-Loss Harvesting

    Not every asset is a candidate for tax-loss harvesting. The ideal asset for this strategy is one that has lost value but still fits within your long-term investment mandate. You should never sell an asset solely for the tax benefit if the underlying company or fund no longer aligns with your goals. Harvesting is a tactical move, not a reason to abandon a sound investment strategy. Look first to assets that have experienced temporary price dips due to market volatility rather than fundamental shifts in the business model. If you truly believe in the long-term outlook of an investment, harvesting provides a way to capture tax benefits while keeping your exposure to that investment class intact.

    Exchange-Traded Funds (ETFs) are often the most suitable candidates for tax-loss harvesting. Because there are thousands of ETFs available, it is relatively easy to find a “tax-efficient substitute.” If you sell a Vanguard ETF, you can typically find a BlackRock or State Street fund that offers similar exposure to the same sector or market cap. This allows you to harvest the loss while maintaining your desired asset allocation—the “what” of your portfolio remains largely unchanged, even if the “how” (the specific vehicle) changes.

    Individual stocks are also harvestable, but they require more caution. If you hold a volatile tech stock that has dropped in price, you might harvest the loss. However, you must avoid buying back that same stock for 31 days. This exposes you to the risk of the stock price surging during that month, potentially causing you to miss out on recovery gains. This is why many investors prefer to harvest losses in diversified funds rather than individual securities. In a fund, you are capturing a market movement rather than an idiosyncratic stock movement, which is generally easier to replicate without triggering the wash-sale rule.

    Finally, look for assets with high “tax-lot” density. If you have been investing in the same fund for years, you likely have dozens of individual tax lots, some of which may have gains and others with losses. By selectively selling only those lots that are at a loss, you can surgicaly extract tax benefits without liquidating your entire position. This level of precision is only possible if you maintain clear, detailed records. As you refine your approach, you will begin to see your brokerage account not just as a collection of tickers, but as a dynamic financial structure that can be optimized for both growth and tax efficiency. This shift in mindset is a hallmark of sophisticated wealth management and is key to long-term financial success.

    The Impact of Tax-Loss Harvesting on Long-Term Compounding

    The true power of tax-loss harvesting is best understood not as a one-time tax savings event, but as a mechanism to accelerate the engine of long-term wealth building. When you strategically realize investment losses to offset capital gains, you are effectively keeping more of your capital inside your brokerage account rather than sending it to the tax authorities. This retained capital, even if it represents a relatively small percentage of your portfolio in any given year, remains invested and subject to the mathematical miracle of compounding.

    Consider the difference between a taxable portfolio where dividends and realized gains are taxed annually without mitigation, versus a portfolio where tax-loss harvesting is employed systematically. In the latter, the tax drag—the reduction in your annual returns caused by taxes—is minimized. By reinvesting the tax savings back into the market, you expand your principal. Over a ten, twenty, or thirty-year horizon, that additional principal can grow significantly. This process is a foundational component of modern wealth management, allowing investors to harness the full potential of their market returns.

    Furthermore, tax-loss harvesting provides a cushion against market volatility. During downturns, when an investor might feel discouraged by the paper losses in their account, tax-loss harvesting turns a negative experience into an actionable strategy. By capturing these losses, you lower your future tax liability while maintaining your exposure to the market. This ensures that when the recovery occurs, you are participating with a larger cost basis and a more efficient overall tax structure, maximizing the velocity of your wealth creation.

    When to Avoid Harvesting Losses in Your Portfolio

    While tax-loss harvesting is a potent tool for tax efficiency, it is not universally appropriate in every scenario. Understanding the nuances of when to abstain from this strategy is as important as knowing how to execute it. The primary concern is the “Wash Sale Rule,” which prohibits you from claiming a loss on a security if you purchase a “substantially identical” security within 30 days before or after the sale. If you violate this rule, the IRS disallows the loss, and the tax benefit is deferred, complicating your record-keeping without providing the immediate benefit you sought.

    Additionally, you must consider the costs of transaction fees and the potential impact of short-term versus long-term capital gains tax rates. If your brokerage charges high commissions for trades, the cost of executing the harvest might outweigh the tax savings, particularly if the loss is minimal. You should also be mindful of the “tax rate arbitrage” trap. If you harvest a long-term capital loss—which is generally taxed at a lower rate—to offset a short-term capital gain—which is taxed at your higher ordinary income rate—you are making a tactical error. Your goal should be to offset high-tax-rate gains first.

    Investors should also exercise caution when dealing with investments that have high dividend yields or unique tax treatments, such as certain Master Limited Partnerships (MLPs) or Real Estate Investment Trusts (REITs). Because these assets have complex tax reporting requirements (often involving K-1 forms), the administrative burden of tracking losses may not justify the tax savings. Finally, if you expect to be in a significantly lower tax bracket in the future—perhaps due to impending retirement—the immediate value of the tax deduction today may be less than the benefit of deferring those gains to a time when your marginal tax rate is reduced.

    Integrating Tax-Loss Harvesting into Your Wealth Strategy

    To move beyond occasional trades and make tax-loss harvesting a true pillar of your wealth strategy, you need a disciplined, systematic approach. This begins with asset location—ensuring that the right investments are held in the right accounts. High-turnover or tax-inefficient assets should generally reside in tax-advantaged accounts like IRAs or 401(k)s, while tax-efficient index funds and ETFs are best suited for taxable brokerage accounts where harvesting is possible.

    Successful integration also requires robust monitoring. Many modern platforms offer automated tax-loss harvesting, which scans your portfolio daily for opportunities to harvest losses, but even manual investors can succeed by conducting a quarterly review. During these reviews, check for “tax-loss harvesting candidates”—assets that have dropped below your cost basis. Before selling, identify a suitable “replacement asset” to keep your market exposure consistent while avoiding a wash sale.

    Strategy Type Methodology Best For
    Automated Harvesting Algorithmic daily monitoring of price drops Busy professionals with diverse portfolios
    Quarterly Tactical Scheduled review and rebalancing sessions Hands-on investors seeking control
    Opportunistic Executing trades during market corrections Long-term investors reacting to volatility
    Asset Replacement Swapping ticker symbols to maintain exposure Avoiding the 30-day Wash Sale Rule

    How to Track and Report Losses on Your Tax Return

    Accurate record-keeping is the cornerstone of tax-loss harvesting. Without it, you risk either missing out on valid deductions or triggering an audit due to discrepancies. Your brokerage firm will provide you with a Form 1099-B each year, which reports your capital gains and losses. However, the brokerage may not always perfectly calculate the wash sales across different accounts you hold at different firms, making your personal documentation essential.

    Start by maintaining a comprehensive log of your transactions. Record the purchase date, the original cost basis, the sale date, and the net proceeds of every trade. If you engage in tax-loss harvesting, clearly note the “substantially identical” replacement asset purchased to ensure you have proof that you did not violate the wash sale rule. When filing your taxes, these losses are summarized on Schedule D of your Form 1040.

    Remember that you can use capital losses to offset capital gains dollar-for-dollar. If your losses exceed your gains, you can deduct up to $3,000 of the excess against your ordinary income. Any remaining loss beyond that can be “carried forward” into future tax years indefinitely. This carry-forward ability is a massive advantage for wealth building, as it creates a “bank” of losses that can be tapped during years when you realize significant capital gains, such as when you sell a property or rebalance a large, successful investment position.

    Frequently Asked Questions

    What is the difference between a capital gain and a capital loss?

    A capital gain occurs when you sell an investment for more than its original purchase price (cost basis), while a capital loss occurs when you sell an investment for less than you paid for it. In the context of taxes, these are used to determine your net profit or loss for the year, which directly impacts your tax liability.

    Can I harvest losses if I don’t have any capital gains?

    Yes, you can still harvest losses even if you haven’t realized any capital gains in a given year. If your losses exceed your gains, you can use up to $3,000 of the net loss to offset your ordinary income, such as your salary. Any amount beyond that can be carried forward to future tax years, providing a tax shield for future gains.

    What exactly is a “substantially identical” investment?

    The IRS does not provide a rigid definition for “substantially identical,” but it generally refers to an investment that is almost exactly the same as the one you sold. For example, selling an S&P 500 index fund and buying another S&P 500 index fund from a different provider is often viewed as substantially identical. Investors typically choose a fund tracking a slightly different index to avoid this ambiguity.

    How does tax-loss harvesting affect my long-term portfolio performance?

    Tax-loss harvesting improves your net performance by reducing the amount of money lost to taxes each year. By effectively lowering your tax bill, you retain more capital in your brokerage account, which is then reinvested. Over long periods, this retained capital benefits from compounding interest and growth, which can significantly enhance your final wealth accumulation compared to an account that does not utilize these strategies.

    Is tax-loss harvesting only for wealthy investors?

    No, tax-loss harvesting is a strategy available to anyone with a taxable brokerage account. While high-net-worth individuals may find it more impactful due to higher marginal tax brackets, investors at all stages of wealth building can benefit from the ability to lower their taxable income and optimize their returns. Many automated platforms now make this accessible for small account balances as well.

    What happens if I forget to report a wash sale?

    If you fail to report a wash sale correctly, the IRS may eventually catch the discrepancy when they receive information from your brokerage. This could lead to a correction of your tax return, potential penalties, and interest charges. It is critical to reconcile your own trading records with the 1099-B forms provided by your financial institutions to ensure complete and accurate reporting.

    Conclusion

    Tax-loss harvesting is far more than a technical accounting maneuver; it is a sophisticated wealth-building strategy that allows you to take control of your financial destiny in the face of market uncertainty. By transforming market volatility into a mechanism for tax efficiency, you preserve your capital, maximize the effects of compounding, and build a more resilient financial future. As with any strategy, the key lies in consistency, discipline, and a thorough understanding of the rules. Whether you choose to automate the process through a digital advisor or manage your portfolio with manual precision, the goal remains the same: keeping more of what you earn so that it can work harder for you. Start reviewing your portfolio today to identify potential opportunities for efficiency, and ensure that your investment strategy is fully aligned with your long-term wealth goals.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • 529 Plan vs Coverdell ESA: Which Is Better for Education Wealth?

    529 Plan vs Coverdell ESA: Which Is Better for Education Wealth?

    Key Takeaways

    • 529 plans offer higher contribution ceilings, making them a preferred tool for aggressive long-term wealth building for education.
    • Coverdell ESAs provide greater investment flexibility, allowing account holders to select individual stocks and alternative assets.
    • Both accounts offer powerful tax-advantaged status where earnings grow tax-free if used for qualified education expenses.
    • Eligibility for Coverdell ESAs is restricted by income levels, whereas 529 plans have no such income-based contribution caps.
    • Choosing between the two depends on your specific wealth-building strategy, time horizon, and desired level of hands-on investment control.

    When it comes to building long-term wealth for a child’s future, the escalating cost of education remains a primary financial hurdle for families globally. Navigating the landscape of tax-advantaged accounts requires a clear understanding of the tools available to maximize your savings efficiency. While both the 529 plan and the Coverdell ESA serve as essential vehicles to save for college and other qualified expenses, they function under different regulatory frameworks that can significantly impact your portfolio’s trajectory. By carefully weighing the flexibility of investment choices against contribution limits and tax structures, you can determine which strategy aligns best with your broader financial goals. This guide, brought to you by the wealthsimplyput Editorial Team, examines the nuances of these accounts to ensure your education savings strategy is both robust and efficient.

    Understanding the Basics of 529 Education Savings Plans

    The 529 plan is perhaps the most widely recognized tool for families aiming to build wealth specifically for education. Established under section 529 of the Internal Revenue Code, these plans are state-sponsored investment accounts that offer distinct tax-advantaged benefits designed to make saving for college more manageable. When you contribute to a 529 plan, you are typically investing after-tax dollars, but the true wealth-building power lies in the tax-free growth of those investments. Provided the funds are utilized for qualified education expenses—which include tuition, fees, room and board, books, and required equipment—the earnings on your investments are never subject to federal income tax.

    From an administrative perspective, 529 plans are divided into two main types: education savings plans and prepaid tuition plans. The education savings plan, which functions similarly to a 401(k) or an individual retirement account (IRA), allows your contributions to be invested in a portfolio of mutual funds or exchange-traded funds (ETFs). The value of your account rises and falls based on the performance of these underlying assets. Conversely, a prepaid tuition plan allows you to essentially purchase credits for tuition at today’s rates to be used at eligible institutions in the future. While this provides a hedge against tuition inflation, it is generally restricted to specific public or private institutions within a state system.

    One of the most compelling aspects of the 529 plan is its lack of income restrictions. Unlike other education-focused savings vehicles, there is no maximum income threshold for contributors. This makes the 529 plan an accessible option for high-earning households looking to secure wealth for future generations. Furthermore, these plans offer high contribution limits, which vary by state but are often quite generous, allowing families to build significant education funds over an 18-year horizon.

    Additionally, 529 plans are highly portable and flexible regarding beneficiaries. If the original beneficiary decides not to pursue higher education or receives a scholarship, the account owner can generally change the beneficiary to another qualifying family member without incurring taxes or penalties. This flexibility protects the accumulated wealth from being “trapped” in an account that might otherwise go unused. Many states also offer additional tax incentives, such as state income tax deductions or credits for residents who contribute to their home state’s plan, further enhancing the overall value proposition of these accounts. By leveraging these state-level benefits, savvy savers can essentially manufacture an immediate return on their initial investment, significantly accelerating the wealth-building process.

    How Coverdell Education Savings Accounts Work

    The Coverdell Education Savings Account (ESA) is a specialized tax-advantaged account that functions quite differently from a 529 plan, primarily in terms of control and accessibility. Often considered a “boutique” option for education savings, the Coverdell ESA operates under a trust structure where the account holder acts as a custodian for the designated beneficiary. Similar to the 529 plan, the primary benefit is that contributions grow tax-deferred, and withdrawals are tax-free if used for qualified education expenses. However, the scope of what constitutes a “qualified expense” is often broader for a Coverdell ESA, potentially including elementary and secondary education costs, such as private school tuition or uniforms, which provides a layer of flexibility that many families find highly advantageous.

    Despite its benefits, the Coverdell ESA comes with strict limitations that define its place in a wealth-building strategy. The most notable constraint is the annual contribution limit per beneficiary. Unlike 529 plans, which can accept tens of thousands of dollars in a single year, Coverdell ESAs are capped at a relatively low annual amount. This limit applies regardless of the number of individuals contributing to the account. Because of this ceiling, the Coverdell ESA is often viewed as a supplemental tool rather than a primary vehicle for funding a full undergraduate degree at a prestige institution.

    Furthermore, the Coverdell ESA is subject to strict eligibility requirements based on the contributor’s modified adjusted gross income (MAGI). If your income exceeds specific federal thresholds, you may be ineligible to contribute directly to a Coverdell ESA. This income-based restriction serves as a significant hurdle for high-net-worth individuals, effectively steering them toward the more inclusive 529 plans.

    Beyond these financial limitations, the Coverdell ESA carries a “use it or lose it” deadline. In many cases, the funds in a Coverdell ESA must be used or distributed by the time the beneficiary reaches age 30, unless they are transferred to another family member. This necessitates a more precise timeline for educational goals compared to the open-ended nature of some 529 plans. Despite these constraints, the Coverdell ESA remains a powerful wealth-building instrument for those who start early. Because the account allows for a much wider range of investment options—including individual stocks, bonds, and even real estate investment trusts (REITs)—it is highly favored by investors who prefer a hands-on, active approach to managing their assets. If you have the time to actively manage a portfolio and want the ability to invest in specific assets rather than relying on state-provided fund menus, the Coverdell ESA offers an level of customization that is difficult to replicate elsewhere.

    Comparing Tax Advantages and Growth Potential

    When analyzing the efficacy of education wealth strategies, one must look closely at how tax advantages and compounding growth interact within each account type. Both the 529 plan and the Coverdell ESA are designed to insulate your capital gains from the eroding effects of taxation. In a standard brokerage account, dividends, interest, and capital gains are subject to taxes annually, which acts as a “drag” on the power of compounding. By contrast, the 529 plan and Coverdell ESA allow your wealth to grow entirely tax-free, meaning every dollar of gain can be reinvested to generate further growth.

    The primary divergence in growth potential arises from the contribution limits and the underlying investment philosophy permitted by the IRS. Because the 529 plan has significantly higher contribution ceilings and, in some cases, no aggregate limit on the account balance, it is the superior vehicle for long-term “set it and forget it” wealth building. An investor who maximizes their 529 contributions over a decade can generate a massive pool of capital that leverages the compounding effect far more effectively than an account limited by low annual caps.

    However, the “growth potential” is also a product of the investment choices available. Because Coverdell ESAs typically allow the account owner to hold individual stocks or alternative assets, a savvy investor might achieve higher returns than the broader market averages found in typical 529 age-based portfolios. This is a classic trade-off: 529 plans provide ease of use and high capacity, whereas Coverdell ESAs provide the granular control required for aggressive, tactical investment strategies.

    State tax treatment also influences growth. Many 529 plans allow for a state income tax deduction on contributions. If you invest $5,000 in a 529 plan and receive a $300 state tax break, that is an immediate 6% return on your investment that does not exist with the Coverdell ESA. Over 18 years, reinvesting those tax savings into the plan creates an additional layer of compounding that significantly increases the total wealth generated for education.

    Ultimately, the choice hinges on your tax bracket and your desire for investment control. If you are a high earner or seeking to maximize total account size, the 529 plan’s structural advantages—namely its lack of contribution caps and state-level incentives—often outweigh the flexibility offered by the Coverdell. If you are a sophisticated investor who prefers a self-directed portfolio and values the ability to pay for K-12 schooling, the Coverdell ESA provides a distinct set of advantages that can complement your other wealth-building efforts.

    Feature 529 Plan Coverdell ESA Best For
    Contribution Limits Very High (State specific) Low (Annual limit) 529 for large-scale wealth
    Investment Control Limited (Age-based/Fixed menus) High (Self-directed/Stocks) Coverdell for active traders
    Income Limits None Yes (MAGI restrictions apply) 529 for high earners
    Qualified Expenses College/Limited K-12 College + K-12 Coverdell for private K-12
    Age Deadlines None/Extended Typically age 30 529 for long-term planning

    Analyzing Contribution Limits and Eligibility Rules

    Understanding the boundaries of your contributions is critical to maintaining compliance with federal regulations. The 529 plan, while governed by state-level sponsorship, operates under federal rules that are remarkably permissive. There is effectively no federal limit on how much you can contribute to a 529 plan in a single year, though individual states do set an “aggregate limit” (the total amount allowed in an account) to prevent abuse. These limits are typically quite high, often exceeding several hundred thousand dollars, reflecting the plan’s intent to cover the entire cost of a four-year degree at a top-tier university. Furthermore, for families looking to jump-start their wealth-building, the 529 plan allows for “super-funding”—the ability to front-load five years’ worth of gift-tax-exempt contributions into a single year, providing a significant boost to your compound growth timeline.

    In sharp contrast, the Coverdell ESA is governed by stringent federal caps. The annual contribution limit per beneficiary is a fixed, relatively small amount. This limit is an aggregate cap, meaning that even if you open multiple Coverdell accounts for one child, the total contributions across all those accounts cannot exceed the annual threshold. If you exceed this amount, you risk significant tax penalties. Consequently, the Coverdell ESA is often treated as a supplementary account, rarely used as the sole vehicle for funding higher education.

    Eligibility is another area of significant divergence. The 529 plan has no income-related barriers. Anyone, regardless of their annual salary, can open and fund a 529 account. This makes it the standard choice for wealth management planners working with high-net-worth clients. Conversely, the Coverdell ESA is subject to income phase-outs. If your modified adjusted gross income (MAGI) exceeds the limit defined by the IRS, your ability to contribute is either restricted or completely eliminated. These rules change periodically, making it necessary to review current IRS guidelines before committing to a Coverdell contribution strategy.

    When planning your wealth strategy, consider how these limits affect your ability to diversify. Many families choose to utilize both accounts simultaneously. They might use a 529 plan to capture the bulk of the wealth-building momentum while using a Coverdell ESA to handle specific, smaller educational expenses like private elementary tuition, which may not be fully covered or as easily accessible under certain state-specific 529 guidelines. By understanding these regulatory constraints, you avoid the administrative headaches of over-contribution and ensure that your capital is deployed in the most efficient manner possible. Always consult the latest IRS Publication 970 to stay updated on these specific thresholds, as they are subject to legislative adjustments that can impact your long-term wealth strategy.

    Investment Flexibility: What Can You Actually Buy?

    The spectrum of investment flexibility is perhaps the most defining characteristic separating the 529 plan from the Coverdell ESA. When you open a 529 plan, you are effectively choosing from a menu curated by the state or the program manager. Typically, this menu consists of a series of “age-based” portfolios that automatically adjust their asset allocation as the child approaches college age. In the early years, these portfolios are heavily weighted toward equities to maximize growth potential. As the beneficiary nears college age, the portfolio gradually shifts toward fixed-income and cash equivalents to preserve the capital. While this “auto-pilot” approach is highly valued by busy families, it limits your ability to make independent investment decisions. You generally cannot select individual stocks, sector-specific ETFs, or alternative assets.

    The Coverdell ESA flips this dynamic completely. When you open a Coverdell ESA, you are usually doing so through a self-directed brokerage account. This empowers the account holder—typically the parent or guardian—to act as the primary investment manager. You have the freedom to select virtually any asset permitted by the brokerage, which could include individual stocks of blue-chip companies, specific mutual funds that reflect your personal values, or even niche assets if your brokerage platform supports them. This level of control is ideal for the investor who views education savings not just as a static pool of money, but as an opportunity to practice active portfolio management.

    This difference in flexibility creates a distinct divergence in the potential risk-reward profile of your education savings. A 529 plan is built for diversification and risk management; it is designed to keep you from “gambling” with your child’s future. If you are an investor who prefers to minimize the time spent monitoring market trends, the 529 plan is an exceptionally robust tool. Its internal rebalancing ensures that you are not overly exposed to market volatility as the date for withdrawal approaches.

    Conversely, the Coverdell ESA requires a higher degree of financial literacy and discipline. Without a preset menu of age-based adjustments, you are solely responsible for ensuring that your asset allocation remains appropriate for the time horizon. If your child is five years away from starting college and you are heavily concentrated in high-beta tech stocks within your Coverdell account, you are assuming a level of risk that a 529 plan would naturally mitigate. Therefore, the “better” account depends on your capability and desire to perform active asset management. If your strength lies in picking winning sectors or individual equities, the Coverdell ESA allows you to leverage that skill to potentially outperform the market. If you prefer a hands-off approach that guarantees institutional-grade asset allocation, the 529 plan is almost universally the preferred solution for serious wealth-building.

    Qualified vs Non-Qualified Education Expenses

    Understanding the distinction between qualified and non-qualified expenses is the cornerstone of managing your tax-advantaged education accounts. Misinterpreting these categories can lead to unnecessary tax liabilities and penalties, which ultimately erodes your wealth-building efforts. Both 529 plans and Coverdell ESAs allow for tax-free withdrawals when funds are used for “qualified education expenses,” but the scope of these definitions is what often dictates which account serves a family’s long-term strategy best.

    For both 529 plans and Coverdell ESAs, qualified expenses typically include tuition, fees, books, supplies, and equipment required for enrollment or attendance at an eligible educational institution. This includes computers, software, and internet access if they are used primarily by the beneficiary for educational purposes. Additionally, room and board are considered qualified expenses, provided the student is enrolled at least half-time. However, the definition of “room and board” is subject to specific institutional cost-of-attendance limits, meaning you cannot simply use these accounts to pay for any off-campus housing arrangement without verifying the limits set by the school’s financial aid office.

    Where the divergence occurs is in the nuance of secondary education. Coverdell ESAs have historically been more flexible regarding K-12 expenses, including tuition, fees, academic tutoring, and even special needs services at public, private, or religious schools. While 529 plans were expanded under recent legislation to cover up to $10,000 annually in K-12 tuition, they generally lack the broader coverage for extracurriculars or specific K-12 supplies that a Coverdell ESA might allow. If your primary goal for wealth preservation involves private schooling before college, the Coverdell ESA’s wider latitude for K-12 expenses may offer a structural advantage.

    Non-qualified expenses, by contrast, trigger a tax headache. If you withdraw funds for purposes outside of the IRS-approved definition—such as paying for non-educational car repairs, travel, or general living expenses—you will owe income tax on the earnings portion of the withdrawal, plus a 10% penalty. This penalty is a significant barrier to wealth building, as it essentially wipes out the compounding advantage gained over time. Therefore, maintaining a clear ledger of receipts and keeping these accounts strictly for their intended educational purpose is vital for anyone prioritizing wealth accumulation through these vehicles.

    Impact on Financial Aid and Student Loan Eligibility

    A common concern for families building wealth for their children’s future is how these assets will impact the Free Application for Federal Student Aid (FAFSA). The federal government views education savings differently depending on the account owner, and understanding this impact is essential for optimizing your college funding strategy.

    When a 529 plan is owned by a parent, it is considered a parental asset on the FAFSA. Parental assets are assessed at a lower rate—typically around 5.64% of the account value—when calculating the Student Aid Index (SAI). This means that a 529 plan generally has a relatively minor impact on financial aid eligibility compared to assets held in the student’s name. Coverdell ESAs are treated similarly, provided they are reported as parental assets. However, if the Coverdell ESA is held in the name of the student, it could potentially be assessed at a higher rate, though current regulations generally treat them as parental assets if the parent is the account holder.

    Perhaps more important is the distinction regarding distributions. When a student receives money from a 529 plan that is owned by a grandparent or another non-parent, those funds historically triggered a higher assessment in subsequent aid years. Recent regulatory changes have aimed to simplify this, but the “best practice” for wealth management remains for parents to maintain primary ownership of the accounts to maximize aid potential. If you are aiming for specific need-based aid, you must navigate these federal formulas carefully to ensure that your prudent saving habits don’t inadvertently disqualify your student from receiving institutional or federal grants.

    Regarding student loans, both accounts are intended to reduce the need for borrowing. Because these accounts allow for tax-advantaged growth, they function as a hedge against the rising cost of tuition, which is the primary driver of student loan debt. By front-loading these accounts, you reduce the necessity of taking out high-interest loans later, which preserves the family’s overall net worth and long-term financial flexibility.

    Transferability and Beneficiary Changes Explained

    One of the strongest arguments for using a 529 plan in your wealth-building portfolio is its flexibility regarding the beneficiary. If your first child decides not to attend college, or if there are leftover funds after they graduate, the 529 plan allows you to change the beneficiary to another qualifying family member, including siblings, cousins, or even the original beneficiary themselves, without triggering taxes or penalties. This creates a “legacy” account that can serve multiple generations, acting as a vehicle for generational wealth transfer.

    The Coverdell ESA is significantly more rigid. By law, the beneficiary of a Coverdell ESA must be named by the time they reach age 18, and the funds must generally be distributed by the time the beneficiary turns 30. While you can technically roll over a Coverdell ESA to a family member, the timing constraints make it a less effective tool for long-term multi-generational planning compared to the 529 plan. If your intent is to create a pool of capital that can be repurposed across a wider timeline, the 529 plan is the superior choice.

    Furthermore, recent tax law changes allow for a limited amount of unused 529 plan funds—subject to strict conditions—to be rolled over into a Roth IRA for the beneficiary. This specific provision makes the 529 plan an incredibly powerful tool for not just education, but for kickstarting a young adult’s retirement wealth. Because the Coverdell ESA does not share this rollover provision, its utility is strictly capped at education, whereas the 529 plan possesses an exit strategy for excess capital that can bolster a child’s long-term financial independence.

    Feature 529 Plan Coverdell ESA Best For
    Beneficiary Changes Flexible (Family members) Restricted 529 for long-term legacy
    Contribution Limits Very High (State-set) Low ($2,000/year) 529 for aggressive saving
    K-12 Flexibility Limited ($10,000/year) Broad Coverdell for K-12 schooling
    Age Restrictions None (Typically) Distribution by age 30 529 for lifelong flexibility

    Which Account Offers Better Long-Term Wealth Preservation?

    When evaluating which account better preserves wealth, we must look at the impact of contribution limits and compound growth. The 529 plan is designed for large-scale wealth building. With total lifetime contribution limits often reaching several hundred thousand dollars, parents and grandparents can park significant capital in a tax-advantaged environment, allowing the tax-free growth to snowball over 15 to 20 years. For families with the means to aggressively save for education, the 529 plan is the undisputed champion due to its sheer capacity.

    The Coverdell ESA, capped at $2,000 in annual contributions per beneficiary, acts more as a “supplemental” savings bucket. While the tax benefits are identical (tax-free growth and tax-free withdrawals for qualified expenses), the low contribution cap limits the absolute amount of wealth that can be accumulated. If your objective is to fully fund a four-year degree at a private institution, you will likely need the higher limits of a 529 plan to reach your goal.

    However, the Coverdell ESA offers an investment advantage: control. Many 529 plans limit you to a selection of age-based portfolios or predetermined investment paths. With a self-directed Coverdell ESA, depending on the custodian, you may have a wider range of investment options, including individual stocks or alternative assets. If you are an experienced investor who believes you can outperform the market indices through individual stock selection, a Coverdell ESA offers more tactical freedom. That said, for most families, the institutional oversight and simplicity of the 529 plan outweigh the minor potential gains from individual asset selection.

    When to Use Both Accounts for Maximum Tax Efficiency

    It is not always an “either-or” decision. In fact, many families optimize their wealth-building strategy by utilizing both vehicles in tandem. A common strategy for high-earning households is to maximize the Coverdell ESA first, taking advantage of its total control and broad K-12 flexibility for early-childhood or private primary school costs. Once the $2,000 annual limit is reached, all additional funds are directed into the 529 plan.

    By using the Coverdell for immediate or short-term educational needs, you preserve the 529 plan to act as the primary engine for high-cost university expenses. This tiered approach allows you to capture the benefits of the Coverdell’s specific strengths while ensuring that you have the robust contribution capacity of the 529 plan for the heavy lifting of college tuition. This strategy ensures that no tax-advantaged space is left wasted.

    Furthermore, keep in mind the interaction between these accounts. You cannot pay for the same educational expense with both accounts in the same tax year. Careful record-keeping is required to ensure that you are “splitting” your expenses correctly. If you use a Coverdell to pay for textbooks and a 529 to pay for room and board, you maintain full compliance with IRS guidelines. This level of planning is how wealthy families manage their education liabilities, turning a stressful financial obligation into a structured, manageable, and tax-efficient wealth strategy.

    Frequently Asked Questions

    Can I open both a 529 plan and a Coverdell ESA for the same child?

    Yes, you are permitted to open both types of accounts for the same beneficiary. Many families choose to do this to maximize their tax-advantaged space, using the Coverdell for more flexible K-12 expenses while relying on the 529 plan for the bulk of college costs.

    What happens to the money in a 529 plan if my child receives a scholarship?

    If your child receives a scholarship, you can withdraw an amount equal to the scholarship value from your 529 plan penalty-free. While you will still owe income tax on the earnings portion of that specific withdrawal, the 10% penalty is waived. This is a common and safe way to recoup your savings.

    Can I invest in a 529 plan from a state other than the one where I live?

    Yes, you can participate in almost any state’s 529 plan regardless of where you reside. However, you should check if your home state offers a state income tax deduction or credit for contributions to its own plan, as this can provide an additional layer of financial benefit.

    Do I have to pay taxes on the money if I move it from a Coverdell to a 529?

    You can generally roll over funds from a Coverdell ESA to a 529 plan without incurring taxes or penalties, provided the rollover is handled directly between the financial institutions. It is wise to verify the specific administrative procedures with both your current and receiving custodians to ensure it is processed as a non-taxable event.

    What are the primary investment risks associated with these accounts?

    Because these are investment accounts, the principal is subject to market volatility. Unlike a savings account, your balance can decrease if the underlying investments perform poorly. It is recommended to choose an asset allocation that aligns with the time horizon remaining until the student begins their education.

    Are there income limits for contributing to these accounts?

    There are no income limits for contributing to 529 plans, making them accessible to families of all income levels. Coverdell ESAs, however, do have modified adjusted gross income (MAGI) limits for contributors; if your income exceeds these thresholds, you may be ineligible to contribute to a Coverdell ESA directly.

    Conclusion

    Building wealth for education is a marathon, not a sprint. By leveraging the tax-advantaged power of 529 plans and Coverdell ESAs, you are not just saving for tuition—you are securing the financial future of the next generation. Whether you prioritize the high-contribution capacity of the 529 plan or the tactical flexibility of the Coverdell ESA, the most important step is to start early and stay consistent. The earlier you begin, the more time you provide your capital to benefit from the power of tax-deferred growth.

    As you navigate your path toward education wealth, remember that these tools are designed to work for you. Assess your family’s specific needs, look at your long-term goals, and don’t hesitate to build a hybrid approach that utilizes the unique strengths of both accounts. Your commitment today will pay dividends in your family’s ability to pursue academic dreams without the crushing burden of excessive debt.

    Ready to start? Evaluate your current budget, compare the investment options in your state’s 529 plan, and consider speaking with a professional about integrating these accounts into your broader financial plan. Take control of your education savings journey today and watch your wealth grow.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Tax-Loss Harvesting: How to Lower Your Taxes and Build Wealth

    Tax-Loss Harvesting: How to Lower Your Taxes and Build Wealth

    Key Takeaways

    • Tax-loss harvesting allows investors to sell underperforming assets to offset gains, effectively lowering their overall tax liability.
    • The strategy is a core component of tax-efficient investing, helping to preserve more capital for long-term wealth building.
    • Compliance with the IRS 30-day wash sale rule is essential to ensure that your losses remain deductible for tax purposes.
    • Beyond offsetting capital gains, investors can use up to a set annual limit of excess losses to offset ordinary income.
    • Investment portfolio optimization requires balancing tax considerations with the long-term goal of maintaining a consistent market presence.

    In the modern investment landscape, what you earn is only half the equation; what you keep determines the true trajectory of your financial future. As we move further into 2026, the complexity of global markets makes tax-efficient investing more than just a preference—it is a necessity for those committed to serious wealth building. Among the most effective tools in a sophisticated investor’s arsenal is tax-loss harvesting. By strategically selling securities that have declined in value, you can transform a temporary paper loss into a functional shield against taxes. This guide, prepared by the wealthsimplyput Editorial Team, explores how mastering these maneuvers can help you optimize your portfolio, mitigate the burden of capital gains, and accelerate your path to sustained wealth.

    What Is Tax-Loss Harvesting and How Does It Work?

    At its core, tax-loss harvesting is the practice of selling an investment that has experienced a decline in market value to realize a loss for tax purposes. This strategy is primarily used to offset capital gains—the profit you make when you sell an asset for more than you paid for it. If you hold a diverse portfolio, it is almost inevitable that some assets will perform differently than others. When an asset drops below your original purchase price (your cost basis), that position holds “unrealized” losses. By intentionally triggering these losses, you create a ledger entry that the IRS allows you to use to reduce your total taxable gains.

    The mechanics of the process are straightforward, though they require disciplined portfolio management. Imagine you have a portfolio with various holdings. You might have one position in an index fund or individual stock that has gained significant value, and another that has depreciated. If you sell the winning position, you trigger a capital gain, which is typically taxable. However, if you simultaneously sell the underperforming position, the loss from that sale can be subtracted from your total gains for the year. This effectively lowers your tax bill, leaving more money in your account to be reinvested into the market.

    Beyond the simple math, tax-loss harvesting is a vital component of investment portfolio optimization. It forces an investor to review their holdings regularly. Often, individuals hold onto losing investments out of a psychological attachment or the “sunk cost fallacy,” hoping for a rebound that may never come. Tax-loss harvesting encourages a proactive approach: evaluating why an asset is underperforming and determining whether it still aligns with your long-term wealth goals. If the asset is no longer a core part of your strategy, harvesting the loss allows you to exit the position, claim the tax benefit, and reallocate those funds into an asset that better fits your risk profile.

    It is important to note that tax-loss harvesting is not about locking in permanent losses; it is about tax management. Many investors “reinvest” the proceeds from the sale into a similar—but not identical—asset. This keeps the investor’s market exposure intact, ensuring they do not miss out on potential recoveries or long-term growth. Because this strategy involves frequent adjustments to your holdings, it is often automated by robo-advisors or managed through systematic rebalancing. However, even manual investors can execute this strategy by keeping a close watch on their cost basis throughout the year, rather than waiting until the end of December when many others attempt to harvest losses, which can sometimes lead to suboptimal trading executions.

    Approach Methodology Best For
    Manual Harvesting Monitoring positions and executing trades yourself based on price targets. Active, hands-on investors.
    Automated/Robo-Advisor Software algorithms that trigger sales automatically when losses hit a threshold. Set-it-and-forget-it investors.
    Professional Management Working with a tax-focused financial advisor to coordinate trades. High-net-worth portfolios.

    Understanding the Capital Gains Tax Impact on Your Wealth

    To understand the necessity of tax-efficient investing, one must first grasp the impact of capital gains taxes on long-term wealth building. Every time you sell an asset for a profit, the government claims a portion of that gain. Depending on how long you held the asset, this is classified as either short-term or long-term capital gains. Short-term gains, resulting from assets held for a year or less, are typically taxed at your ordinary income tax rate. Long-term gains, for assets held for more than a year, are generally taxed at preferential, lower rates. While these rates can seem manageable in a vacuum, the compounding effect of paying them annually can significantly erode the power of your investment growth over decades.

    When you allow gains to accumulate without offsetting them through investment tax strategies, you are essentially paying a “drag” on your portfolio’s performance. Consider the difference between $10,000 growing in a tax-deferred environment versus one where you must subtract 15-20% of your growth annually to pay tax bills. That “lost” tax money is capital that is no longer compounding. Over twenty or thirty years, the difference in the final portfolio value can be substantial. This is why wealth preservation is often defined by the steps taken to minimize unnecessary outflows, and taxes are consistently one of the largest outflows an investor will face.

    Furthermore, capital gains taxes can create a “lock-in effect.” Investors may be reluctant to sell a position that has grown too large or no longer aligns with their risk tolerance because they fear the impending tax bill. This leads to portfolio concentration, where an investor’s wealth is overly tethered to a single asset or sector, increasing overall risk. By utilizing tax-loss harvesting, you can “cleanse” your portfolio of underperformers while simultaneously generating the tax shields needed to offset the gains from rebalancing your concentrated positions. This allows you to modernize your asset allocation without suffering the full fiscal penalty of selling your winners.

    Additionally, the impact of capital gains taxes is magnified when considering state-level taxation. In many jurisdictions, capital gains are treated as taxable income, meaning you could be paying both federal and state taxes on the same profit. When you proactively harvest losses, you are working to reduce your “Adjusted Gross Income” in a way that can lower your federal tax burden and, by extension, your state liability. This multi-layered approach to tax mitigation is what differentiates passive savers from strategic wealth builders. By keeping capital gains taxes in check, you ensure that more of your total return is reinvested, effectively allowing your portfolio to do more of the heavy lifting over the long run.

    How to Identify Assets for Tax-Loss Harvesting

    Identifying candidates for tax-loss harvesting is a methodical process that requires an objective look at your brokerage statements. The goal is to isolate positions where the current market price is lower than the cost basis. The cost basis is generally the price you paid for the asset, plus any commissions or fees, adjusted for dividends or stock splits. While your brokerage platform likely tracks this for you, it is vital to verify these figures independently to ensure you have an accurate picture of your unrealized losses. If you have been purchasing shares of the same stock or fund at different times, you must also be aware of the “tax lot” identification method you are using, such as FIFO (first-in, first-out) or specific identification.

    Once you have identified the assets trading below their cost basis, the next step is to evaluate them through the lens of your investment strategy. Not every loss is worth harvesting. If an asset is simply experiencing short-term volatility but remains a cornerstone of your long-term wealth strategy, selling it may be counterproductive—especially if you believe in its eventual recovery. The best candidates for harvesting are those where the thesis for holding the asset has weakened. Perhaps the company’s competitive advantage has eroded, the underlying sector is facing long-term regulatory headwinds, or you have simply identified a more promising opportunity that offers better growth potential.

    It is also helpful to categorize your portfolio into “core” and “satellite” holdings. Core holdings, such as broad-market index funds or diversified ETFs, are essential for long-term growth. Because these indices tend to recover, harvesting losses here can be tricky; you want to maintain your market exposure at all times. In these cases, investors often switch to a “proxy” asset. For example, if you sell an S&P 500 index fund that is down, you might immediately reinvest the proceeds into a different S&P 500 fund from a different provider. You get to keep the loss for tax purposes while maintaining the exact same market exposure, effectively “resetting” your tax basis while staying fully invested.

    Lastly, consider the magnitude of the loss relative to your overall capital gains. If you have significant gains to offset, you may prioritize harvesting larger losses to maximize the tax benefit. However, even smaller losses can be valuable if they offset gains that would otherwise be taxed at high ordinary income rates. Many experienced investors create a “harvesting checklist” that they review on a quarterly basis. This prevents the end-of-year rush and allows for more thoughtful decision-making. By keeping a running log of potential harvestable assets throughout the year, you ensure that you are never caught off guard when a market dip provides a clear opportunity to improve your tax efficiency.

    The 30-Day Wash Sale Rule Explained

    While the benefits of tax-loss harvesting are compelling, they come with a regulatory guardrail known as the “wash sale rule.” This is an IRS regulation designed to prevent investors from selling a security just to claim a tax loss while immediately buying it back to maintain their position. The rule states that if you sell a security at a loss and purchase a “substantially identical” security within 30 days before or after the sale, the IRS will disallow the loss deduction for that year. Instead, the disallowed loss is added to the cost basis of the new position, effectively deferring the tax benefit until the new position is eventually sold.

    Understanding what constitutes “substantially identical” is the most critical aspect of avoiding a wash sale violation. The IRS has not provided an exhaustive list of what counts as identical, but general guidance suggests that selling shares of a company and buying the exact same ticker symbol is a clear violation. Buying an option contract on the same stock or a call option within the window is also typically considered a violation. However, the interpretation becomes more nuanced when discussing ETFs or mutual funds. Many investors assume that buying a different S&P 500 fund from a different issuer is safe, but it is always wise to consult with a tax professional regarding your specific choices, as the IRS maintains the right to challenge trades they view as tax-avoidance schemes rather than legitimate investment moves.

    To successfully navigate the wash sale rule, you must be disciplined about the 30-day window. If you accidentally trigger a wash sale, it is not the end of the world—the loss is merely deferred rather than lost forever—but it does complicate your tax filing. You will need to track the adjusted cost basis of your new position, which adds administrative burden during tax season. For those who automate their portfolios, many brokerage platforms have built-in wash sale prevention tools that automatically flag or block trades that would trigger a violation. If you are managing your own investments, consider setting calendar alerts to remind you when the 30-day “danger zone” has passed for any asset you have harvested.

    The most effective strategy to avoid wash sales while staying invested is to use “closely correlated but not identical” assets. For instance, if you sell a loss-making total stock market ETF, you might replace it with an ETF that tracks a slightly different index, such as one focused on large-cap stocks or a broader international index. By diversifying your holdings in this way, you fulfill your goal of staying invested while harvesting a meaningful tax deduction. This approach not only keeps you compliant with the IRS but can also lead to a more robust, diversified portfolio. The wash sale rule should be viewed not as a barrier, but as a framework that encourages you to be more intentional about your portfolio’s composition and your long-term asset allocation strategy.

    Offsetting Ordinary Income Using Capital Losses

    A frequently overlooked advantage of tax-loss harvesting is its potential to offset more than just capital gains. Under current tax laws, if your total capital losses for the year exceed your total capital gains, you are permitted to use a portion of that net loss to offset your ordinary income. In many tax jurisdictions, this limit is set at $3,000 per year for individuals, though specific rules can vary based on filing status and regional laws. While this may seem like a modest amount, it can translate to meaningful savings for those in higher tax brackets, effectively lowering your taxable income by a few thousand dollars and providing an immediate boost to your net cash flow.

    What happens if you have losses that exceed this annual limit? The good news is that these losses are not forfeited. Any net capital loss that exceeds the annual threshold can be “carried forward” into future tax years indefinitely. This carryover allows you to use those historical losses to offset future gains or future ordinary income. This creates a powerful, multi-year tax planning strategy. By building up a “bank” of carried-forward losses during market downturns, you can essentially create a long-term cushion that protects your future wealth from tax volatility. This turns bad market years into potential long-term strategic assets.

    To maximize this feature, you should keep meticulous records of your capital loss carryovers. Every year, when you file your taxes, you will report these amounts on the appropriate tax forms. Ensuring that your tax preparer or tax software is correctly tracking your carryover from year to year is essential for wealth building. If you lose track of these figures, you lose the opportunity to lower your future tax bills. Because capital gains and losses are aggregated across all your taxable accounts, it is vital to maintain a consolidated view of your investment performance, rather than looking at accounts in isolation.

    Using losses to offset ordinary income is particularly useful for investors who may have high salary income but smaller capital gains in a given year. By strategically harvesting losses, you can reduce your total tax burden, creating more “room” in your budget to invest in retirement accounts or debt reduction. This creates a positive feedback loop: the tax savings from your investments are recycled into further wealth-building activities, which in turn grow your portfolio and provide more capital for future compounding. This is the essence of systematic wealth management—leveraging the tax code as a tool to accelerate your progress toward financial independence rather than letting it serve as a silent drain on your hard-earned assets.

    Tax-Loss Harvesting vs Asset Location Strategies

    While tax-loss harvesting is a tactical maneuver used to reduce your immediate tax liability, asset location is a strategic framework focused on where you keep your investments to maximize long-term wealth. Understanding the interplay between these two is essential for achieving a tax-efficient portfolio.

    Asset location involves placing assets with different tax characteristics into the accounts where they will be taxed the least. For example, high-yield bonds or actively managed funds, which generate significant ordinary income, are often better suited for tax-advantaged accounts like IRAs or 401(k)s. Conversely, tax-efficient investments like broad-market index ETFs or municipal bonds are frequently placed in taxable brokerage accounts.

    Tax-loss harvesting specifically applies to your taxable accounts. It is the practice of selling securities at a loss to offset capital gains or to reduce your taxable income. You cannot harvest losses in a tax-deferred account because those accounts do not generate taxable capital gains or losses in the same way. When you integrate both, you create a dual-layered defense against tax drag: you minimize the tax impact of your growth through strategic location, and you actively harvest losses to lower your taxable capital gains throughout the year.

    Strategy Primary Goal Account Type Best for
    Tax-Loss Harvesting Reduce immediate capital gains tax Taxable Brokerage Active portfolio management
    Asset Location Minimize tax drag on ongoing returns Mix of Taxable/Tax-advantaged Long-term wealth building
    Tax-Efficient Placement Delay or eliminate tax events Tax-Advantaged (IRA/401k) High-tax bracket investors

    Automating Your Tax-Loss Harvesting Process

    In 2026, the technology behind investment portfolio optimization has become increasingly sophisticated. Manually monitoring every position for a dip significant enough to justify a trade is time-consuming and prone to human error, particularly when accounting for the 30-day “wash sale” rule.

    Many modern robo-advisors and brokerage platforms now offer automated tax-loss harvesting services. These automated systems monitor your portfolio daily. When an asset drops below a specified threshold, the algorithm automatically sells the security and replaces it with a “substantially similar” asset—such as swapping one S&P 500 ETF for a different provider’s S&P 500 ETF. This allows you to lock in the tax loss without exiting the market or significantly altering your asset allocation.

    The primary benefit of automation is consistency. You don’t have to wait until December to look for opportunities; the system harvests losses throughout the entire calendar year. However, investors must be aware of the “tracking error” that can occur when an algorithm moves funds between similar but non-identical assets. While the long-term impact on wealth is generally positive due to tax savings, you should periodically review these automated trades to ensure they align with your broader investment strategy.

    Common Tax-Loss Harvesting Mistakes to Avoid in 2026

    Even with advanced tools, tax-loss harvesting is fraught with regulatory traps. The most common pitfall remains the violation of the IRS wash sale rule. If you sell a security for a loss and purchase a “substantially identical” security within 30 days before or after the sale, the IRS will disallow the tax deduction, and the loss will be added to the cost basis of the new security.

    Another frequent mistake is “over-harvesting.” Some investors become so focused on generating losses that they churn their portfolios, incurring unnecessary transaction costs or drifting away from their target asset allocation. Remember that the goal of tax-efficient investing is to optimize for after-tax returns, not just to generate tax deductions.

    Lastly, many investors forget to track their carryover losses. If your harvested losses exceed your capital gains, you can use up to a specific amount of that net loss to offset ordinary income, with the remainder carried forward indefinitely. Failing to account for these carryovers on your tax filings means leaving potential wealth-building opportunities on the table. Always ensure your tax software or CPA is accurately recording these figures year-over-year.

    Is Tax-Loss Harvesting Right for Your Portfolio Size?

    A common misconception is that tax-loss harvesting is only for the ultra-wealthy. In reality, it can be a valuable tool for anyone with a taxable brokerage account, though the benefits scale differently based on portfolio size.

    For smaller portfolios, the time and effort required to track losses may outweigh the tax savings, unless you are using an automated platform. If your capital gains are relatively low, you might not have much of a tax bill to offset in the first place. However, as your wealth grows and your portfolio generates more taxable events, the percentage of your returns lost to taxes becomes a significant drag. For these investors, harvesting losses can lead to meaningful tax alpha over a multi-decade horizon.

    Before implementing this strategy, perform a cost-benefit analysis. Consider your current tax bracket, the amount of your assets in taxable accounts, and the volatility of those assets. Volatile assets, such as individual stocks or aggressive ETFs, provide more frequent opportunities for harvesting than stable bond funds. If your portfolio is small and largely held in tax-advantaged accounts, focus your efforts on low-cost, tax-efficient index fund investing rather than complex harvesting strategies.

    Advanced Strategies for High-Net-Worth Investors

    For high-net-worth individuals, tax-loss harvesting is often part of a broader “tax alpha” strategy. One advanced technique is “Direct Indexing,” where instead of buying an ETF that tracks an index, you purchase the individual stocks within that index. By holding hundreds of individual positions, you gain granular control over which specific stocks to sell for a loss at any given time, providing significantly more harvestable opportunities than a standard ETF would offer.

    Another strategy involves “tax-efficient gifting.” If you have highly appreciated assets, gifting them to charity or to family members in lower tax brackets can be more effective than selling them yourself. This allows you to avoid the capital gains tax entirely while still removing the asset from your taxable estate, serving as a powerful tool for intergenerational wealth building.

    Finally, sophisticated investors often engage in “tax-aware rebalancing.” This means rebalancing a portfolio not just to maintain target weights, but to do so in a way that minimizes tax hits. By selling the “losers” to fund the purchase of “winners” (or vice versa, depending on the need), you can achieve your target allocation while simultaneously pruning the portfolio for tax purposes.

    Frequently Asked Questions

    Can I harvest losses in my 401(k) or IRA?

    No. Tax-loss harvesting only applies to taxable brokerage accounts. Assets in 401(k)s and IRAs grow on a tax-deferred or tax-free basis, meaning capital gains and losses within these accounts do not have an impact on your annual personal income tax returns.

    What is considered a “substantially identical” investment?

    The IRS does not provide a rigid definition for “substantially identical,” but it generally includes securities that perform in the same way. Selling an S&P 500 index fund and immediately buying another S&P 500 index fund is generally considered a wash sale, whereas swapping an S&P 500 fund for a Total Stock Market fund is typically acceptable.

    How much can I deduct from my ordinary income?

    If your total capital losses exceed your capital gains in a given year, you can use the excess loss to offset up to a specific amount of your ordinary income (the amount is subject to inflation adjustments and current tax law). Any remaining loss can be carried forward to future tax years.

    Do I need a professional to perform tax-loss harvesting?

    You do not need a professional to execute the strategy, as many automated platforms handle it for you. However, for high-net-worth investors with complex portfolios, direct indexing, or significant charitable gifting goals, a tax professional or financial advisor can provide valuable guidance to ensure compliance and optimization.

    How does the wash sale rule impact my long-term strategy?

    The wash sale rule prevents you from taking a tax deduction if you repurchase the same security too quickly. It does not mean you cannot own the asset; it simply means you must wait 31 days to repurchase it, or choose a “non-identical” substitute to maintain your market exposure during that period.

    Is tax-loss harvesting still effective in a bull market?

    Yes. Even in a bull market, individual sectors or specific stocks within your portfolio may experience temporary downturns. Tax-loss harvesting allows you to capture those losses to offset gains from other parts of your portfolio, even while the overall market trend is positive.

    Conclusion

    Tax-loss harvesting is more than just a way to save a few dollars at tax time; it is a fundamental component of proactive investment portfolio optimization. By strategically utilizing market volatility to your advantage, you can reduce your tax drag, compound your returns more effectively, and accelerate your path to long-term wealth. Whether you choose to automate the process through modern technology or take a hands-on approach with advanced direct indexing, the key is consistency and awareness of regulatory boundaries.

    As you plan your financial journey in 2026 and beyond, remember that the most successful investors are those who view tax management as a year-round discipline rather than an annual chore. Take the time to audit your current taxable holdings today and consider how a tax-efficient approach might enhance your bottom line.

    If you are ready to take control of your financial future, start by reviewing your brokerage account’s tax-loss settings or speaking with a qualified advisor about implementing a more tax-aware strategy. Your future self will thank you for the diligence you apply today.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Estate Planning 101: How to Protect Your Wealth at Any Age

    Estate Planning 101: How to Protect Your Wealth at Any Age

    Key Takeaways

    • Estate planning is a proactive tool for wealth preservation, regardless of your current net worth or age.
    • Understanding the legal distinction between a trust vs will is the foundation of effective asset transition.
    • Beneficiary designations are powerful legal contracts that often supersede the instructions left in your final will.
    • A comprehensive plan includes incapacity planning, such as durable power of attorney and healthcare directives.
    • Regularly updating your estate plan ensures your wealth transfer reflects your life changes and current financial goals.

    For many young professionals, the concept of estate planning feels like a task reserved for the distant future—a chore to be addressed only after retirement or during one’s golden years. However, true wealth management is a lifelong commitment. Whether you are just beginning your career or you have already accumulated significant assets, proactive estate planning is the most effective way to protect your wealth and ensure your financial legacy remains intact. By taking control of your financial and medical decisions today, you prevent unnecessary legal hurdles, protect your loved ones from administrative burdens, and ensure that your hard-earned assets are managed according to your precise vision. This guide serves as a foundational resource for navigating the complexities of wealth transition, moving from basic concepts to actionable strategies.

    Why Estate Planning Is Not Just for the Elderly

    A common misconception in the finance world is that estate planning is merely about writing a will to distribute property after death. In reality, estate planning is a holistic approach to managing your financial life, aimed at both preservation and orderly transfer. For young professionals, the focus is often on the accumulation phase, but the risk of failing to plan—regardless of age—cannot be overstated. If you become incapacitated due to an unforeseen illness or injury, your assets could become frozen, leaving your family unable to pay bills or manage your business interests without court intervention.

    Estate planning basics involve more than just drafting documents; it is about creating a roadmap for your life. When you are in your twenties, thirties, or forties, you are likely building the foundation of your future wealth. Protecting that foundation means establishing guardrails that activate during times of crisis. Many experts suggest that young adults should view estate planning as a form of financial insurance. Just as you carry health or auto insurance to mitigate unforeseen risks, an estate plan serves as insurance against legal and administrative chaos.

    Consider the professional who is scaling a business or climbing the corporate ladder. With equity stakes, digital assets, and investment portfolios, the complexity of one’s financial footprint grows rapidly. If you do not have a plan, the state’s default laws—known as intestacy laws—dictate who inherits your wealth and who manages your affairs. These laws rarely align with personal intentions or family dynamics. By engaging in estate planning early, you maintain agency. You decide who receives your assets, who manages your accounts, and who holds the authority to speak for you when you cannot speak for yourself.

    Furthermore, early planning is highly efficient. Because you likely have fewer creditors and less complex tax considerations than someone in retirement, your initial planning is often straightforward and cost-effective. As you age, you can simply update your documents to reflect the growth of your wealth. This iterative process creates a habit of fiscal responsibility that sets high-net-worth individuals apart from those who leave their future to chance. Ultimately, estate planning is about peace of mind. Knowing that you have secured your affairs allows you to focus your energy on growing your wealth, advancing your career, and enjoying your life, rather than worrying about the catastrophic costs of poor planning.

    Understanding the Difference Between a Will and a Trust

    When you start to explore how to protect your wealth, you will inevitably encounter the core debate: trust vs will. Both are vital instruments for wealth transfer, but they serve different functions and offer varying levels of control, privacy, and efficiency. A will is a legal document that outlines your wishes for the distribution of your assets after your passing. It is a fundamental part of a comprehensive plan, but it is also a public document. When a will is used as the primary vehicle for wealth transfer, it must pass through the probate court process.

    Probate is the court-supervised procedure that validates your will, pays your remaining debts, and distributes your assets. While probate provides a level of legal oversight, it can be time-consuming, public, and expensive. For many, the cost of probate can erode the very wealth they intended to pass on to their heirs. This is where a trust often becomes the superior choice for sophisticated wealth planning.

    Feature Last Will and Testament Living Trust Best For
    Probate Involvement Yes No Trust: Wealth Preservation
    Privacy Public Record Private Trust: Financial Secrecy
    Incapacity Planning No Yes Trust: Ongoing Management
    Upfront Effort Low Moderate to High Will: Simplicity

    A living trust allows you to transfer your assets into a legal entity while you are still alive. You act as the trustee, maintaining control over the assets, and you name a successor trustee who takes over if you become incapacitated or pass away. Because the assets are owned by the trust, they avoid the probate process entirely. This transition is usually faster and more private, as the distribution of your assets remains between you, your successor, and your beneficiaries without court involvement. For young professionals, a trust is particularly effective because it can be funded with new assets as your wealth grows.

    Furthermore, trusts offer flexibility that a will simply cannot match. If you want to place conditions on how your beneficiaries receive their inheritance—such as distributions tied to age milestones, educational achievements, or specific financial goals—a trust is the mechanism that makes that possible. While a will provides a “lump sum” transfer, a trust provides ongoing management. Many people utilize both documents in tandem: the trust handles the majority of the asset transfer and probate avoidance, while a “pour-over will” acts as a safety net, ensuring any assets accidentally left outside the trust are funneled into it upon death. By understanding these instruments, you can tailor your estate plan to reflect your specific complexity and goals.

    The Critical Role of Beneficiary Designations

    Perhaps one of the most overlooked aspects of estate planning is the beneficiary designation. Many people erroneously believe that their will serves as the master document for all their assets. However, in the world of financial law, beneficiary designations often override the instructions in your will. Assets such as life insurance policies, 401(k) accounts, IRAs, and certain bank accounts use “payable-on-death” (POD) or “transfer-on-death” (TOD) designations. These are binding contracts with the financial institution, and they dictate exactly where those assets go regardless of what you wrote in your Last Will and Testament.

    This reality makes regular auditing of your beneficiary designations an essential task for any wealth-conscious professional. Life changes frequently—marriage, divorce, the birth of a child, or the purchase of a new home—and each of these events should trigger a review of your designations. Failing to update these forms can lead to disastrous outcomes. For example, if you neglect to update a life insurance policy and a former partner remains listed as the primary beneficiary, that individual will legally receive the proceeds upon your death, even if your will clearly states otherwise. The courts rarely intervene in these scenarios because the contract with the financial institution is seen as superior to your testamentary document.

    Beyond simply naming a person, consider the implications of naming minors as beneficiaries. Generally, minors cannot legally own large sums of money or property. If you name a minor child directly on an insurance policy or retirement account, a court may be required to appoint a guardian to oversee the assets until the child reaches the age of majority. This court supervision can be expensive and may limit your ability to dictate how the funds are used for the child’s care. Instead, experts often recommend naming a trust as the beneficiary of these accounts, which allows you to define how the assets should be managed and distributed for the child’s benefit.

    Finally, do not overlook “contingent” beneficiaries. If your primary beneficiary passes away before you, and you have not named a secondary recipient, your assets may end up in a default category that forces them into the probate process. Providing a clear line of succession for every account ensures that your wealth transfer remains seamless. Making this a routine part of your financial health check—perhaps alongside your annual investment portfolio review—will protect your wealth from unintended legal exposure and ensure that your beneficiaries are prepared to receive the assets exactly as you intended.

    Setting Up Durable Power of Attorney for Finances

    Estate planning is not just about what happens after death; it is equally about what happens while you are alive but unable to make decisions. If you suffer a sudden injury or a medical crisis that leaves you incapacitated, your bank accounts, investment portfolios, and business holdings do not magically stop requiring management. Without a pre-authorized plan, your family could be forced to petition the court to be appointed as your legal guardian or conservator. This process is time-consuming, expensive, and can result in the court choosing an agent you might not have selected yourself.

    A Durable Power of Attorney (DPOA) for finances is a critical legal document that grants a trusted person—your “agent” or “attorney-in-fact”—the authority to manage your financial affairs if you are unable to do so. The word “durable” is vital here, as it signifies that the power remains in effect even if you become mentally or physically incapacitated. Without the “durable” provision, your power of attorney would technically expire the moment you lose the capacity to make decisions, which is exactly the point when you need it most.

    When choosing an agent, consider someone who is not only trustworthy but also capable of handling your specific financial profile. This person may need to pay your mortgage, manage your investment accounts, file taxes, or run your business. They will have a fiduciary duty, meaning they are legally obligated to act in your best interests, but you should still choose someone with the financial literacy and temperament to navigate these responsibilities. Many people choose a spouse, a close family member, or even a professional fiduciary, such as an accountant or a trust officer at a bank.

    It is also a common practice to include “springing” powers in some jurisdictions, where the power of attorney only takes effect upon a formal medical determination of your incapacity. This can provide an extra layer of comfort for those worried about ceding control too early. However, regardless of the format, the goal is the same: to ensure that your financial engine continues to hum without interruption. By setting up a DPOA, you are effectively buying yourself a safety net, allowing you to focus on recovery and growth, knowing that your wealth is protected by a plan that you initiated while you were in control of your faculties.

    Healthcare Directives: Protecting Your Decisions and Assets

    The final pillar of foundational estate planning is the healthcare directive, often known as a living will or medical power of attorney. While this document is technically separate from your financial affairs, it is deeply intertwined with your wealth protection strategy. Medical costs can be astronomical, and without clear instructions, family members may be forced to make difficult, conflicting, and expensive choices regarding your care. A comprehensive healthcare directive ensures that your medical treatment aligns with your values, potentially preventing unnecessary interventions that could deplete your estate’s resources.

    A medical power of attorney allows you to designate a healthcare proxy—the person who will make medical decisions on your behalf if you cannot. This person should be someone who knows your values well and is comfortable speaking with medical professionals. They do not necessarily need to be the same person as your financial agent; in fact, some individuals choose to split these roles to balance the burden of responsibility. For example, you might choose a financially savvy person to manage your investments while choosing an empathetic family member to handle medical decisions.

    A living will, meanwhile, outlines your specific preferences for life-sustaining treatments. It addresses scenarios such as long-term artificial ventilation, tube feeding, or the use of experimental treatments. By documenting these preferences in advance, you remove the heavy emotional burden from your loved ones. In the absence of such a document, your family members might disagree on the appropriate course of action, leading to conflict that can spill over into the administration of your estate. Legal battles born from medical uncertainty are a common, yet entirely preventable, cause of wealth erosion.

    Furthermore, healthcare directives ensure that your wishes are respected across different healthcare providers and settings. Modern digital platforms now allow you to store these documents securely, ensuring that your doctors can access your instructions in an emergency. Protecting your autonomy in these moments is a profound part of wealth management. When you make these decisions in advance, you ensure that your assets are used for your care according to your wishes, rather than being redirected to legal disputes or unwanted medical procedures. As a professional, taking the time to draft these documents is an act of foresight that protects your family, your dignity, and your legacy.

    Strategies to Minimize Estate Taxes and Transfer Costs

    One of the most persistent misconceptions among young professionals is that tax-efficient wealth transfer is only a concern for the ultra-wealthy. In reality, strategic tax planning is the bedrock of preserving your financial legacy, regardless of your current net worth. As your assets grow—through real estate, investment portfolios, and retirement accounts—the tax burden placed on your heirs can become significant if you have not proactively structured your estate.

    The primary objective of minimizing transfer costs is to ensure that more of your wealth goes to your intended beneficiaries and less to government coffers. One of the most effective tools for this is the strategic use of gifting. Most jurisdictions allow for an annual gift tax exclusion, which enables you to transfer a set amount of wealth to individuals tax-free each year. By starting this process early in your career, you can significantly reduce the size of your taxable estate over several decades, effectively “freezing” the value of certain assets or removing their future appreciation from your total estate valuation.

    Another powerful strategy involves the use of irrevocable trusts. Unlike a revocable living trust, which offers flexibility but does not necessarily remove assets from your taxable estate, an irrevocable trust transfers the legal ownership of assets out of your personal estate. Once assets are moved into this vehicle, they are generally shielded from estate taxes upon your death. While you relinquish control over these assets, this structure is a gold-standard approach for long-term wealth preservation and protection against creditors.

    Charitable giving also plays a pivotal role in tax minimization. Establishing a donor-advised fund (DAF) or a charitable remainder trust (CRT) can provide immediate income tax deductions while allowing you to maintain a degree of influence over how the funds are distributed over time. These vehicles allow you to support causes you care about while simultaneously lowering the total valuation of your estate, thereby potentially moving your assets below the threshold for estate taxation.

    Finally, consider the tax implications of your investment accounts. Assets held in traditional IRAs or 401(k)s often carry significant embedded income tax liabilities. When these accounts are passed to heirs, the beneficiaries may be required to withdraw the funds and pay income taxes at their own marginal rates. Strategic tax planning may involve converting a portion of these traditional assets into Roth accounts, where the growth and distributions are tax-free, thereby passing a much more valuable, “clean” asset to your heirs.

    Strategy Primary Benefit Best For
    Annual Gifting Reduces estate size tax-free Individuals building wealth early
    Irrevocable Trust Excludes assets from taxable estate High-net-worth protection
    Donor-Advised Fund Income tax deduction & legacy Philanthropic individuals
    Roth Conversions Tax-free distributions for heirs Long-term wealth transfer

    Naming Guardians: Protecting Your Children and Their Financial Future

    For young parents, the process of estate planning often feels emotionally taxing because it forces us to confront the “what-if” scenarios. However, naming a guardian is arguably the most important decision you will make regarding your minor children. Without a formal designation in a legally binding document, the decision regarding who will raise your children—and how your assets will be managed for them—will be left to the discretion of a court. This can result in lengthy, expensive, and public legal battles that add undue stress to your family during an already difficult time.

    When selecting a guardian, consider both the physical care of the children and the management of their inheritance. It is not uncommon for parents to split these roles. You might select a trusted family member or close friend to be the “guardian of the person” (responsible for the daily care and upbringing of the children) and a different party—or a professional trustee—to be the “guardian of the property” (responsible for managing the financial inheritance).

    When drafting your plan, be specific about your values. You can provide a “letter of intent” or a memorandum of wishes that outlines your preferences regarding education, religious upbringing, and even financial milestones. While these documents are not always legally binding in the same way a will is, they serve as a powerful roadmap for the individuals you have entrusted to raise your children. They provide clarity during a period of chaos and ensure that your children are raised in an environment that aligns with your vision.

    Furthermore, ensure that your financial planning supports the role of the guardian. If you name a guardian, you must also consider the life insurance coverage necessary to support that guardian in taking on the added expense of your children. A common mistake is naming a guardian without adequate liquidity to ensure that the guardian is not financially burdened by the responsibility of raising additional children. Financial legacy is not just about the numbers in your bank account; it is about providing the resources necessary to keep your family’s life stable and supported.

    Common Estate Planning Mistakes That Drain Your Wealth

    Even well-intentioned individuals often fall into traps that can derail their wealth transfer objectives. The most frequent error is the “set it and forget it” mentality. Estate planning is not a static event; it is a dynamic process. Failing to update beneficiary designations after major life events—such as marriage, divorce, the birth of a child, or the purchase of property—is a classic mistake that often leads to assets going to the wrong person. Beneficiary designations on life insurance and retirement accounts supersede your will, meaning if you listed an ex-spouse from a decade ago, that individual may legally inherit those assets regardless of what your current will states.

    Another significant drain on wealth is failing to coordinate your assets with your estate plan. Many people go to the expense of creating a trust but fail to “fund” it. A trust is essentially an empty bucket until you retitle your assets—such as brokerage accounts, real estate, and business interests—into the name of the trust. If your assets remain in your personal name, the trust may be ineffective, potentially forcing your estate into a costly and time-consuming probate process.

    Procrastination regarding incapacity planning is another major oversight. Many assume estate planning is only about what happens at death. However, if you become incapacitated due to illness or injury and lack a financial power of attorney or a healthcare directive, your family may be forced to seek court intervention to manage your affairs. This process is public, expensive, and can significantly deplete the very wealth you are trying to protect, all while causing unnecessary conflict among family members.

    Finally, avoid the temptation to use “one-size-fits-all” templates found online without consulting a professional. While DIY forms can be an inexpensive starting point, they rarely account for the complexities of tax law, state-specific regulations, or the specific intricacies of your financial situation. A minor error in a legal document can lead to expensive litigation or, at worst, the nullification of your entire plan, leaving your legacy exposed to unnecessary taxes and legal fees.

    When and How to Update Your Estate Plan as You Age

    As you transition through different stages of your career and life, your estate plan should evolve with you. Generally, experts suggest a comprehensive review of your documents every three to five years, or whenever you experience a major life transition. This rhythm ensures that your plan remains aligned with your current net worth, your family structure, and the ever-changing tax landscape.

    Life transitions that trigger an immediate review include moving to a new state or country, as estate laws vary drastically by jurisdiction. Additionally, the acquisition of significant new assets, such as a business interest, a vacation home, or a large inheritance, should prompt a meeting with your financial advisor and estate attorney. These events often change the complexity of your estate and may necessitate a transition from a simple will to a more robust trust-based structure.

    Family changes are equally critical. The marriage or divorce of your adult children, the death of a designated executor, or a significant change in the financial status of a beneficiary are all reasons to pivot. If a designated beneficiary develops special needs or encounters financial instability, you may need to reconsider leaving assets to them outright. In such cases, creating a protective trust that provides for their needs without jeopardizing their eligibility for government benefits can be a life-changing adjustment.

    To keep your plan organized, maintain an “Estate Organizer” binder or a secure digital vault that contains copies of your will, trust documents, powers of attorney, insurance policies, and account access information. Ensure that your executor knows exactly where these documents are located and how to access them. By proactively managing these updates, you provide your loved ones with the greatest gift of all: peace of mind and a clear, organized path forward during a time of grief.

    Frequently Asked Questions

    What is the primary difference between a will and a trust?

    A will is a legal document that outlines your wishes for the distribution of assets after your death and typically requires the probate court process to take effect. A trust is a fiduciary arrangement that allows a third party, or trustee, to hold assets on behalf of your beneficiaries. Unlike a will, a trust can often bypass the probate process, offering more privacy, faster distribution, and greater control over how assets are managed for your heirs.

    Do I need an estate plan if I am young and don’t have many assets?

    Yes. Estate planning is not just for the wealthy or the elderly. It is essential for anyone who has children, a business, or specific wishes regarding their medical care. Even if your assets are modest, a plan ensures that you have designated individuals to make medical and financial decisions for you if you become incapacitated, which protects you and your family from unnecessary legal intervention.

    What happens if I die without a will?

    Dying without a will is known as dying “intestate.” In this scenario, state law dictates how your assets are distributed, typically favoring immediate family members in a fixed order. The court will appoint an administrator to handle your estate and a guardian for your minor children. This process is often impersonal, costly, and may not align with your actual desires for your family or your assets.

    How often should I review my beneficiary designations?

    It is best practice to review your beneficiary designations every time you have a major life change, such as a marriage, divorce, birth of a child, or death of a beneficiary. At a minimum, experts recommend checking these designations annually to ensure they still reflect your current intentions, as they function independently of your will.

    Can I update my estate plan on my own?

    While you can legally draft your own documents in some jurisdictions, it is generally discouraged. Estate planning laws are complex, and minor drafting errors can lead to significant legal complications or render documents invalid. Working with a qualified attorney ensures that your documents meet all state-specific requirements and are structured to withstand legal scrutiny.

    What is “probate” and can I avoid it?

    Probate is the court-supervised legal process of validating a will, paying off debts, and distributing the remaining assets of a deceased person. It can be a long and public process that involves court fees. Many people use a revocable living trust as their primary vehicle for asset transfer specifically to avoid probate, as assets held in a trust do not require court intervention to pass to the named beneficiaries.

    Conclusion

    Estate planning is far more than a task to be checked off a list; it is a profound act of stewardship and care. By proactively structuring your wealth, you create a buffer against the unpredictability of life, ensuring that your financial legacy serves your family and your values for generations to come. Whether you are just beginning your career or nearing the peak of your professional life, the foundation you build today provides the security your loved ones deserve.

    Take the first step by gathering your financial documents, discussing your intentions with your family, and consulting with a qualified professional. The peace of mind that comes from knowing your affairs are in order is an investment that pays dividends long after you are gone. Secure your future, protect your loved ones, and take control of your financial legacy today.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Business Wealth vs Personal Wealth: How to Keep Both Growing

    Business Wealth vs Personal Wealth: How to Keep Both Growing

    Key Takeaways

    • Mixing business and personal finances creates significant legal, tax, and emotional risks that can jeopardize your long-term wealth.
    • Establishing a clear salary structure is the foundation of effective personal vs business finance management.
    • Tax planning for entrepreneurs should focus on leveraging entity-specific deductions rather than just minimizing immediate tax liability.
    • True wealth management for business owners requires decoupling personal net worth from the volatile performance of a single company.
    • Early retirement planning is crucial, as business owners often neglect their own long-term security in favor of reinvesting in company growth.

    For many entrepreneurs, the boundary between “the business” and “the self” often blurs into a single, high-stakes financial ecosystem. While the passion required to scale a business often necessitates total immersion, relying solely on your company as your primary vehicle for wealth is a gamble that carries substantial risk. Achieving sustainable financial freedom requires a deliberate shift in perspective: treating your business as a high-performing asset that funds your life, rather than seeing your life as a support system for your business. By mastering the art of segregating your capital while simultaneously optimizing both sides of your ledger, you can build a resilient foundation that survives market cycles and provides long-term prosperity. This guide explores the critical strategies for wealth management for business owners, helping you ensure that as your business flourishes, your personal financial security grows in tandem.

    The Danger of Mixing Business and Personal Finances

    The habit of commingling funds is the single most common pitfall in business owner financial planning. When your business operating account functions as your personal piggy bank, you lose the ability to track the true profitability of your venture. From a legal standpoint, this practice—often referred to as “piercing the corporate veil”—can be disastrous. If you operate as a corporation or a limited liability entity, you rely on a distinct legal boundary to protect your personal assets from business liabilities. When you pay for personal groceries with a business debit card or use company funds for private travel without proper accounting, you risk forfeiting that protection, effectively exposing your family’s home, savings, and investments to potential business litigation or creditor claims.

    Beyond legal risk, commingling creates an “accounting fog” that prevents you from understanding the health of your enterprise. Without clear segregation, you might believe your business is highly profitable, while in reality, your profit margins are being inflated or deflated by a mix of unrelated expenses. This lack of visibility makes strategic decision-making nearly impossible. When you cannot distinguish between business capital and personal wealth, you cannot accurately calculate your return on investment or identify which areas of your business are actually driving value.

    Furthermore, the psychological toll of mixing finances cannot be overstated. Entrepreneurs who treat their business bank account as their personal bank account often suffer from “revenue anxiety.” If you see a large balance in your business account and assume it is yours to spend, you may fail to account for upcoming payroll, tax obligations, or seasonal fluctuations. This reactive approach to spending often leads to financial instability, where the business survives on a month-to-month basis despite high gross revenue. Experts generally agree that the first step toward building wealth as a business owner is to enforce a strict “hands-off” policy regarding business capital. This means establishing a separate business account and a personal account, and moving money between them only through formal channels like payroll, owner draws, or dividend distributions. By creating this physical and digital wall, you protect your professional entity, simplify your tax reporting, and, most importantly, gain the clarity needed to manage your personal wealth as an independent entity that is no longer held hostage by the daily fluctuations of your business operations.

    How to Pay Yourself a Sustainable Salary

    Determining how much to pay yourself is a nuanced exercise in balancing the short-term needs of your company with your long-term personal financial goals. Many entrepreneurs make the mistake of paying themselves “whatever is left over,” which is inherently unsustainable. This method ties your personal lifestyle—and your family’s security—directly to the volatile performance of the company. Instead, successful business owner financial planning requires a deliberate, consistent salary structure that allows you to manage your personal budget independently of business revenue cycles.

    To begin, you must establish a market-rate salary. Research your industry standards and determine what a professional in your position would be paid by a similar company. Paying yourself a market-based wage serves two purposes: it forces the business to be profitable on its own merits, without “subsidizing” your lifestyle through owner-draws, and it simplifies your tax planning for entrepreneurs by creating a clear, predictable income stream. Once you have established a salary, treat it as a non-negotiable business expense. Just as you prioritize rent, utilities, and payroll for your staff, your own salary must be factored into the operational budget. This creates a stable floor for your personal finances, allowing you to automate savings, invest in retirement accounts, and build an emergency fund without having to wonder if this month’s profit will be enough to cover your expenses.

    There is, however, an important distinction between a salary and a distribution. For owners of C-corps or S-corps, the IRS generally requires “reasonable compensation” as a salary, which is subject to payroll taxes. Distributions or dividends, on the other hand, are payments made from excess profits. By balancing these two types of income, you can optimize your total take-home pay while minimizing unnecessary tax burdens. The key is to avoid the temptation to increase your salary or take a large distribution during a high-revenue month if the business needs that capital for reinvestment. A sustainable salary is not the maximum amount the company can afford to pay; it is the amount that supports your lifestyle and goals while leaving enough cushion for the business to remain competitive and stable during lean periods. By standardizing this, you transition from a business owner who is constantly scrambling for cash to an executive who manages their income with discipline and foresight.

    Optimizing Tax Efficiency Between Business and Personal Accounts

    Tax planning for entrepreneurs is often viewed as a once-a-year scramble, but it is actually a year-round exercise in strategic wealth management. The goal is to move money from the business side to the personal side in a way that minimizes total tax liability while maximizing your long-term net worth. This requires a deep understanding of your business entity type—whether you are a sole proprietor, LLC, S-Corp, or C-Corp—and how different tax rules apply to each.

    One of the most effective strategies for tax efficiency is maximizing business deductions that serve as investments in your future. For instance, instead of taking out extra cash as a taxable dividend, many business owners find value in utilizing company-sponsored health plans, equipment leasing, or professional development programs that qualify as business expenses. These expenditures lower your business’s taxable income without necessarily increasing your personal income tax burden, provided they are legitimate business activities. However, the most significant opportunity for tax efficiency often lies in the interplay between corporate retirement vehicles and personal investment accounts. By leveraging the specific contribution limits of business-based retirement plans, you can shield a significant portion of your income from immediate taxation, allowing that money to compound over time.

    The following table outlines common approaches to managing cash flow and tax efficiency between business and personal accounts:

    Approach Primary Benefit Best For
    Fixed Market-Rate Salary Predictability & Budgeting All business owners requiring stable cash flow.
    Owner Distributions Tax Flexibility S-Corp owners managing excess profit cycles.
    SEP/Solo 401(k) Contributions High Tax Deferral High-income earners looking to lower current tax.
    Retained Earnings Compound Growth Business owners planning for heavy capital expansion.

    Strategic tax planning also involves the timing of income and expenses. If you expect your business to have a lower profit year, it may be the perfect time to accelerate certain tax-deductible investments or realize long-term capital gains at lower tax rates. Conversely, in high-growth years, you might focus on maximizing contributions to retirement vehicles to offset the increased tax burden. The challenge for many entrepreneurs is that they view taxes as an external force they cannot control, when in fact, you have significant agency in how your business structures its income. By working with a financial advisor who understands the intersection of corporate and personal tax law, you can ensure that you aren’t just paying what you owe, but are also organizing your wealth to prevent unnecessary leakage.

    Diversifying Outside of Your Own Business Assets

    One of the most dangerous, yet common, traps for entrepreneurs is the “concentration risk.” Many business owners effectively have 90% or more of their total net worth tied up in their company. While this is necessary in the startup phase, it becomes a major liability as your wealth grows. If the industry shifts, a new competitor enters the market, or the economy enters a downturn, your primary asset and your primary income stream are simultaneously threatened. Effective wealth management for business owners demands a strategy that slowly shifts wealth from the company into external, diversified assets.

    Think of your business as an engine that generates “fuel”—your profits. The goal of your personal wealth management plan is to take that fuel and deposit it into a variety of different, uncorrelated “storage tanks” outside of the business. These tanks might include a broad-based index fund portfolio, real estate, precious metals, or even other business ventures that are not directly tied to your primary company. Diversification isn’t just about reducing risk; it is about creating an independent financial base that can support your lifestyle even if your business faces significant challenges or you eventually decide to exit.

    A helpful way to implement this is to treat your business like a private equity investor treats a portfolio company. If your business is your main asset, start treating your personal investment account as your own private equity fund. As your business produces free cash flow, set aside a non-negotiable percentage to be moved into an external, diversified investment account. This discipline ensures that your personal net worth grows regardless of how the business performs on a quarterly basis. Furthermore, having liquidity outside of the business provides you with an “anti-fragility” factor; if an unexpected business opportunity arises, you have independent capital that you can deploy, or if the business requires an emergency capital injection, you have a reserve to pull from without needing to rely on expensive debt or outside investors. The goal is to reach a point where your lifestyle is supported by the passive income generated by your diversified assets, allowing the business to become an option rather than an obligation.

    Retirement Planning Options for Self-Employed Individuals

    Retirement planning for business owners is often pushed to the bottom of the to-do list, yet it is one of the most powerful tools available for tax planning and long-term security. Unlike traditional employees who have a 401(k) and employer matching, you are the one responsible for setting up and funding these vehicles. The good news is that as a self-employed individual, you have access to retirement accounts with significantly higher contribution limits than the standard retail IRA or 401(k), allowing you to aggressively save during your most profitable years.

    The Simplified Employee Pension (SEP) IRA is a popular choice for many entrepreneurs due to its simplicity and flexibility. It allows you to contribute a percentage of your compensation without the administrative burden of a full-scale 401(k). For those who want more robust options, a Solo 401(k) often provides higher contribution potential because you can effectively contribute as both the employer and the employee. This “double-dipping” effect allows you to shelter a much larger portion of your business income from taxes than you could in any other standard account type. Additionally, many business owners look into Defined Benefit Plans, which act similarly to traditional pensions and can allow for even higher annual contributions, provided the business consistently generates enough cash flow to support the plan’s requirements.

    When selecting a retirement vehicle, you must consider both your current income and your anticipated future tax bracket. While tax-deferred accounts (like traditional 401(k)s) are excellent for lowering your tax burden when you are in your peak earning years, you should also consider whether a Roth component is available to you. Having a mix of tax-deferred and tax-free assets in your retirement portfolio gives you the flexibility to choose where to draw from in retirement, allowing you to optimize your tax liability in your post-work years. Ultimately, retirement planning is the ultimate act of self-preservation. It is the practice of ensuring that the business you built with your sweat equity can eventually serve as a legacy rather than a requirement for survival. By starting these plans early and automating contributions, you ensure that your personal wealth trajectory remains upward, irrespective of the eventual lifecycle of your business.

    Managing Business Cash Flow Without Sacrificing Personal Liquidity

    For many entrepreneurs, the business is the primary engine of wealth, but relying solely on business cash flow to sustain a personal lifestyle is a high-stakes gamble. Business owners often fall into the trap of “cash flow cannibalization,” where personal financial stability is tied entirely to the monthly volatility of company revenue. Effective wealth management for business owners requires a disciplined approach to segregating operational needs from personal liquidity requirements.

    The first step in this process is establishing a fixed, market-rate salary. Instead of taking “owner’s draws” whenever cash is available, transition to a W-2 payroll structure. This allows you to forecast personal cash flow with accuracy and forces the business to prove its viability independent of your personal living expenses. By treating yourself as an employee, you gain a clear view of the business’s true profitability, which is essential for long-term financial planning.

    To ensure personal liquidity remains untouched by business downturns, prioritize building a “personal buffer fund” that exists entirely outside of the corporate balance sheet. Experts generally suggest that this fund should cover six to twelve months of personal living expenses, held in high-yield, liquid accounts. When business revenue slows, this buffer prevents you from having to liquidate business assets at unfavorable prices to pay your mortgage or utility bills.

    Furthermore, managing cash flow requires a sophisticated approach to working capital. By extending payables strategically and optimizing your accounts receivable cycle, you can maintain a healthier cash position within the business. However, always prioritize the business’s core operational health. If you are constantly dipping into your personal savings to cover payroll or vendor invoices, it is a sign that the business model requires an adjustment rather than a personal subsidy.

    Risk Mitigation: Shielding Personal Assets from Business Liabilities

    The legal separation between an entrepreneur and their business is the cornerstone of risk management. If your personal assets—such as your home, personal brokerage accounts, or college savings—are commingled with business liabilities, you are exposing your family’s future to the risks of commercial litigation, vendor disputes, or industry downturns.

    The most common method of protection is the proper selection and maintenance of a business entity, such as an LLC or a corporation. These structures create a “corporate veil” that typically limits personal liability to the amount invested in the business. However, this veil is not indestructible. “Piercing the corporate veil” occurs when a court decides that a business owner has not maintained a clear distinction between personal and company finances, effectively stripping away liability protection.

    To maintain this wall, you must avoid the following common pitfalls:

    • Commingling Funds: Never use a business credit card for personal purchases or vice versa. Every transaction should be strictly documented to its respective entity.
    • Inadequate Capitalization: Operating a business without sufficient capital can be seen as an attempt to offload business risks onto creditors.
    • Informal Record-Keeping: Even for single-member LLCs, maintain formal meeting minutes and resolutions for significant financial decisions.

    Beyond entity structure, consider umbrella liability insurance. While general business liability covers claims related to your operations, an umbrella policy adds an extra layer of protection for personal assets in the event of catastrophic legal claims. Additionally, wealth management for business owners often involves the use of trusts or holding companies. By placing non-business assets (like real estate or intellectual property) into an irrevocable trust, you may be able to shield them from business-related creditors, provided these transfers are handled well in advance of any legal issues.

    Strategy Primary Objective Best For
    Limited Liability Entity (LLC) Legal Separation General business owners starting out
    Umbrella Insurance Excess Liability Coverage High-net-worth owners with significant personal assets
    Irrevocable Trusts Asset Protection & Estate Planning Long-term wealth preservation for families
    Formal Accounting Practices Preserving the Corporate Veil All entrepreneurs to avoid legal pierce

    Establishing a Long-Term Wealth Transfer Strategy

    Wealth management for business owners is incomplete without a clear strategy for the ultimate transfer of assets. Whether you intend to pass the business to your children, sell it to a strategic partner, or liquidate it upon retirement, the planning must begin years, if not decades, in advance. Procrastination in this area often leads to unnecessary tax burdens and the erosion of family wealth.

    One essential tool in this space is a Buy-Sell Agreement. This legal contract dictates what happens to your shares of the business if you die, become disabled, or decide to retire. Without a clear agreement, surviving partners or family members may face chaotic legal battles over ownership. By pre-funding this agreement with key-person life insurance, you ensure that the surviving partners have the liquidity to buy out your interest, while your family receives the cash value of the business immediately.

    For those looking to keep the business in the family, consider the use of a Family Limited Partnership (FLP). An FLP allows you to transfer ownership interests to younger generations while retaining control over the day-to-day operations of the company. This can be an effective way to shift future appreciation of the business assets out of your taxable estate, effectively reducing your eventual estate tax liability.

    Tax planning for entrepreneurs also includes maximizing the utility of charitable giving. By donating appreciated business interests to a donor-advised fund or a private foundation, you may be able to secure a tax deduction while removing those assets from your estate. This not only accomplishes philanthropic goals but also simplifies the eventual transfer of wealth by reducing the overall size of the taxable estate.

    Scaling Your Personal Wealth Alongside Business Growth

    Building wealth as a business owner involves a paradoxical challenge: your greatest asset (the business) is often your greatest concentration of risk. As the business grows, it is vital to “harvest” the value generated by the company and diversify that value into other asset classes. If 95% of your net worth is tied up in your company, you are not truly wealthy—you are merely “business-rich.”

    Successful wealth management for business owners requires a systematic process of taking profits out of the business and moving them into a diversified, external portfolio. This could include tax-advantaged retirement accounts, index funds, real estate, or other ventures that have zero correlation to your primary business. The goal is to reach a state of “financial independence” where your external investments can sustain your lifestyle, regardless of whether your business is thriving or struggling.

    This process of harvesting profits should be automated. Treat the distribution of profits like a “bill” that the business must pay to the owner’s personal wealth management account. By doing this, you capture the wins during the business’s peak years and provide yourself with the security needed to make rational, long-term business decisions rather than reactive ones based on personal financial desperation.

    Furthermore, as your wealth grows, focus on tax-efficient growth. Utilize tax-advantaged accounts like SEP IRAs, Solo 401(k)s, or defined benefit plans. These accounts not only help you accumulate capital but also lower your current-year tax burden, allowing you to reinvest the savings back into your growth strategies. By aligning your personal financial growth with your business success, you ensure that your total wealth is resilient, diversified, and sustainable for generations to come.

    Frequently Asked Questions

    How can I legally lower my tax burden as a business owner?

    Entrepreneurs can lower their tax liability by maximizing contributions to business-based retirement accounts, utilizing health savings accounts (HSAs), and taking advantage of all eligible business deductions. Working with a CPA to structure your business as an S-corp or C-corp can also offer specific tax-saving opportunities. The key is to engage in tax planning throughout the year rather than waiting until the filing deadline.

    Is it better to keep my business cash in a checking or savings account?

    For operational cash flow, a high-yield business checking account is typically ideal to maintain liquidity while earning a modest return. However, any surplus capital—specifically cash reserves or money earmarked for long-term projects—should be moved into secondary accounts or diversified investments to ensure that your business liquidity is not eroded by inflation.

    What is the biggest mistake owners make with personal vs. business finance?

    The most common mistake is failing to separate finances. Mixing personal and business expenses makes it difficult to track profitability, exposes personal assets to business lawsuits, and complicates tax preparation. Keeping two distinct sets of accounts is the foundational step for any serious approach to personal vs. business finance.

    How do I know when I am “business-rich” but not personally wealthy?

    You are likely “business-rich” if the majority of your net worth is tied to the valuation of a single company and you lack sufficient liquid assets outside of the business to support your lifestyle. A key indicator is having to rely on an immediate sale or loan from the business to cover unexpected, significant personal expenses.

    When should I start planning my business exit strategy?

    Experts generally agree that an exit strategy should be a component of your initial business plan. Whether you intend to sell, merge, or pass the business to heirs, having a long-term goal allows you to build the business in a way that maximizes its value for that specific event. Waiting until you are ready to retire is often too late to implement effective tax and succession planning.

    How does business debt affect my personal wealth management?

    Personal wealth management for business owners involves carefully managing the balance between business and personal leverage. Excessive business debt can make the company more fragile during economic downturns, potentially forcing you to utilize personal assets to keep the company afloat. Always aim to balance necessary business growth financing with a robust personal emergency fund that remains shielded from corporate debt obligations.

    Conclusion

    Managing the intersection of business and personal wealth is not a one-time event; it is a disciplined, ongoing practice. By effectively segregating your finances, protecting your personal assets from business risks, and systematically diversifying your wealth away from your company, you build a foundation that supports both your entrepreneurial ambitions and your long-term personal security. Remember, the true goal of building a business is to generate the financial freedom to choose your future—not to tie your entire identity and livelihood to the volatility of a single enterprise. Take the time to audit your current financial structure today, consult with qualified professionals, and start building a balanced, resilient portfolio. Ready to secure your legacy? Begin by consolidating your business accounts and speaking with an advisor about your long-term estate and tax strategy.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
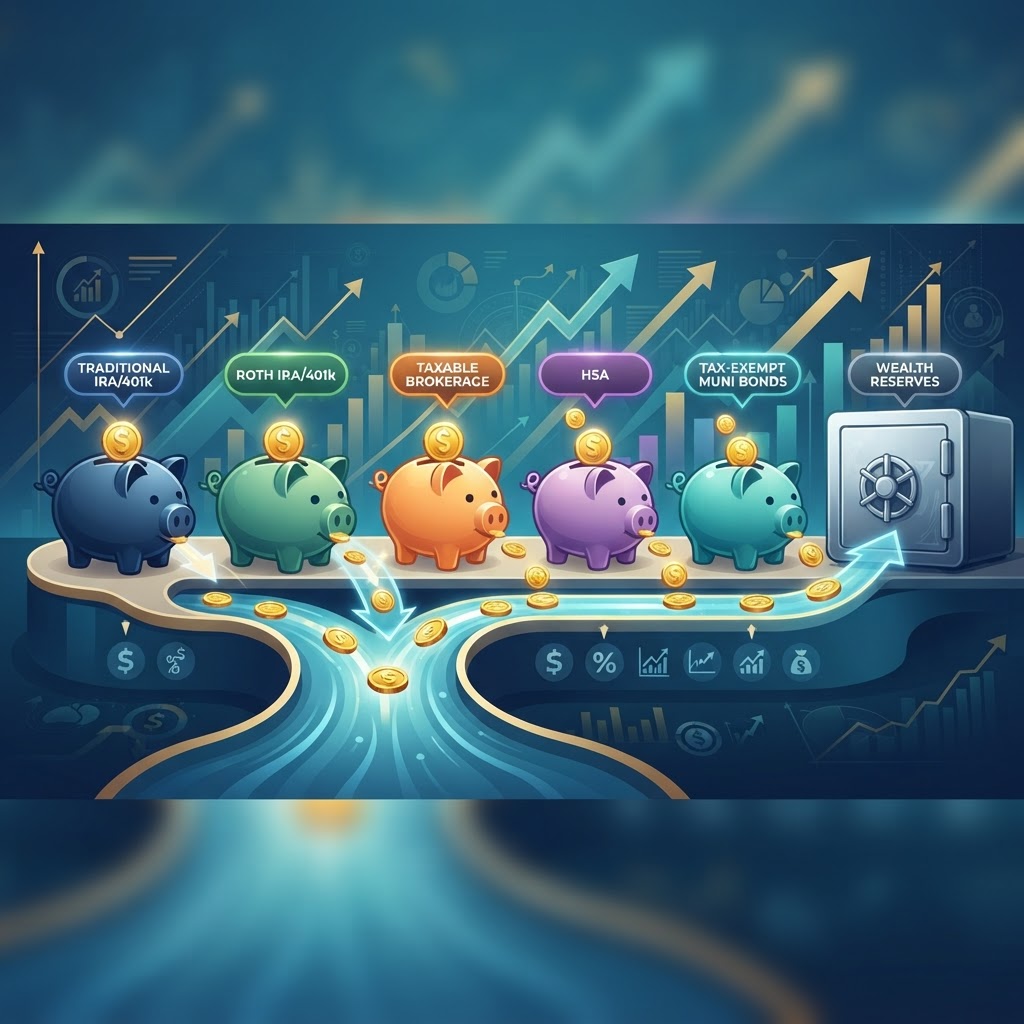
  • Financial Literacy Mistakes to Avoid: Stop Losing Wealth Today

    Financial Literacy Mistakes to Avoid: Stop Losing Wealth Today

    Key Takeaways

    • Mastering financial literacy is the fundamental first step to preserving and growing your capital over the long term.
    • High-interest debt functions as a wealth tax, eroding your potential for compounding returns every single month.
    • Specific, measurable financial goals act as a compass for wealth management, preventing aimless spending.
    • Ignoring inflation turns conservative savings into a depreciating asset rather than a growth vehicle.
    • Building an emergency fund is not optional; it is the essential insurance policy that prevents you from liquidating investments during market downturns.

    Achieving true financial independence is rarely about finding a single “get rich quick” scheme; rather, it is the cumulative result of avoiding common wealth traps that derail the average person’s journey. Many individuals find that despite earning a comfortable income, their net worth remains stagnant or even declines due to a lack of fundamental financial education. By recognizing the most common money mistakes to avoid, you can shift your strategy from reactive spending to proactive wealth building. This guide from the wealthsimplyput Editorial Team is designed to help you navigate these pitfalls, providing actionable personal finance advice to ensure your assets work as hard as you do.

    Understanding the True Cost of Debt and High Interest Rates

    One of the most significant barriers to building wealth is the quiet, persistent drain caused by high-interest debt. When we discuss financial literacy, the conversation often centers on investment strategies or tax optimization, yet the most immediate way to increase net worth is to eliminate liabilities that carry high interest rates. Debt is not merely a number on a statement; it is a mathematical obstacle that works directly against the mechanics of compound interest. When you carry a balance on a credit card or a high-interest personal loan, the cost of borrowing often dwarfs the potential gains you might receive from traditional market investments.

    The danger lies in the “minimum payment” trap. When you pay only the minimum required amount, you are essentially covering the interest while barely touching the principal. Over time, this transforms a relatively small purchase into a massive expense. For example, a modest item bought on credit can effectively double in price if left unpaid for years. This is the antithesis of wealth management; instead of your money earning returns, you are paying a premium for the privilege of delayed payment. Many experts suggest that high-interest debt should be viewed as a financial emergency, warranting immediate action before any significant capital is allocated toward speculative investments.

    To effectively manage this, you must adopt a strategic approach to debt repayment. Many choose between the “snowball” method, which focuses on paying off the smallest balances first to gain psychological momentum, or the “avalanche” method, which prioritizes the highest interest rates to save the most money over time. Regardless of the method, the goal remains the same: stop the bleeding. By systematically eliminating high-interest debt, you free up monthly cash flow that can then be redirected into wealth-generating vehicles like index funds, retirement accounts, or diversified assets. Understanding the opportunity cost—what you could have earned if that money had been invested instead of paid to a lender—is a cornerstone of financial education. Ultimately, becoming debt-free is not just about peace of mind; it is about reclaiming your future earnings so they can contribute to your long-term prosperity rather than settling past obligations.

    Why Failing to Set Specific Financial Goals Leads to Stagnation

    The absence of clear, defined objectives is perhaps the most common reason people find themselves drifting through their financial lives without building substantial wealth. Without a destination, you cannot build a map. Financial literacy is not just about understanding spreadsheets or market trends; it is about behavioral alignment. If your only goal is “to save more,” you are likely to fail because the objective is too vague to drive action. Successful wealth building requires specificity: a target amount, a timeline, and a defined purpose for every dollar you allocate toward your future.

    When you fail to set specific goals, you lose the ability to prioritize. Should you pay off a mortgage, fund a child’s education, or maximize your retirement contributions? Without a structured plan, these choices are often made impulsively based on short-term emotions rather than long-term logic. Furthermore, specific goals act as a defensive shield against lifestyle inflation. When you know that every extra dollar earned is earmarked for a specific milestone—such as a property down payment or a diversified portfolio target—you are far less likely to squander that money on depreciating assets or non-essential lifestyle upgrades. Goal-setting turns wealth management into a game you can track and measure.

    Goal Strategy Description Best For
    SMART Objectives Specific, Measurable, Achievable, Relevant, Time-bound goals. Retirement planning
    Bucket Strategy Allocating funds into distinct categories (needs, wants, investments). Budgeting consistency
    Milestone Tracking Focusing on incremental net-worth targets. High-net-worth growth

    Writing your goals down is a critical step in the psychology of wealth. Research consistently shows that those who document their financial aspirations are statistically more likely to achieve them. A goal should be broken down into actionable steps. For example, rather than saying “I want to be wealthy,” a specific goal would look like: “I want to save $20,000 in a low-cost index fund by the end of 24 months.” This level of detail allows you to reverse-engineer your monthly savings requirements. Once the goal is set, it becomes easier to say ‘no’ to temporary temptations. This is the essence of financial discipline: replacing short-term gratification with the long-term satisfaction of meeting your benchmarks. By focusing on your targets, you create a feedback loop of success that motivates you to remain consistent, even when market conditions or personal circumstances become challenging.

    The Danger of Ignoring Inflation and Its Impact on Savings

    A common misconception in the world of personal finance is that keeping money in a standard, low-interest savings account is a “safe” strategy. In reality, ignoring the erosive power of inflation is a significant mistake that can quietly destroy your purchasing power over time. While the nominal balance in your account may remain the same, the actual value of those dollars declines annually as the cost of goods and services rises. This is known as negative real interest, and it is a silent wealth killer that many people fail to account for when planning their financial future.

    To combat this, you must treat inflation as a guaranteed expense that must be outperformed. If your savings are earning an interest rate that is lower than the rate of inflation, you are technically losing wealth every single year. Achieving true wealth management requires moving beyond simple cash savings and into vehicles that have the potential to appreciate at a rate that beats the Consumer Price Index (CPI) over the long term. This doesn’t mean you should abandon cash entirely; liquidity is important. However, it means recognizing that the portion of your wealth intended for long-term growth must be invested in assets that possess intrinsic value or historical growth trends, such as equities, real estate, or inflation-protected securities.

    Many individuals are paralyzed by the fear of market volatility, leading them to stay entirely in cash. While they avoid the “risk” of a market correction, they expose themselves to the “certainty” of inflation. Over decades, this difference is profound. A thoughtful approach to wealth involves balancing your liquidity needs with an inflation-hedging strategy. This is why financial education is so vital—it teaches you that “risk” is a multifaceted concept. There is the risk of losing value due to market swings, but there is also the risk of your money becoming obsolete because it wasn’t deployed correctly. By diversifying your holdings and ensuring that your asset allocation is aligned with your long-term goals, you can effectively hedge against the rising cost of living. Maintaining the same purchasing power ten, twenty, or thirty years from now is just as important as growing your wealth today.

    Neglecting an Emergency Fund: The Most Common Financial Error

    If you were to rank the most critical money mistakes to avoid, neglecting an emergency fund would sit at the very top. An emergency fund is not merely “extra cash”—it is your primary defense against the unpredictability of life. Financial accidents, job losses, or sudden medical expenses are not if-events; they are when-events. Without a dedicated cushion, a single unexpected bill can force you to rely on credit cards or, worse, liquidate your long-term investments at the worst possible time, such as during a market downturn.

    A properly funded emergency account provides a psychological layer of security that allows you to make better, more rational financial decisions. When you aren’t living in a state of constant financial anxiety, you are less likely to fall victim to high-interest predatory loans or impulsive, high-risk financial schemes. Experts generally recommend keeping anywhere from three to six months of essential living expenses in a highly liquid account. This ensures that you can handle life’s curveballs without compromising your long-term financial roadmap. It is, in essence, the foundation upon which the rest of your wealth-building strategy is constructed.

    Establishing an emergency fund also changes your relationship with your investments. When you know you have cash reserves, you can afford to let your long-term investments grow undisturbed through market cycles. You stop treating your retirement accounts like personal banks and start treating them like the wealth-generating engines they were designed to be. If you find it difficult to save, start small. Even a few hundred dollars can prevent a minor inconvenience from turning into a major financial crisis. Over time, you can increase the fund until it reaches a level that provides genuine peace of mind. Remember, the purpose of an emergency fund isn’t to make you rich; it is to keep you from becoming poor when life doesn’t go according to plan. This is a fundamental principle of wealth preservation that serves as a prerequisite for any aggressive growth strategy.

    Overspending and Lifestyle Inflation: The Hidden Wealth Killer

    Lifestyle inflation is the silent thief of wealth. It occurs when your spending increases in tandem with your income, effectively neutralizing any potential for increased savings or investment. For many, a pay raise or a bonus is an invitation to upgrade their standard of living—a nicer car, a larger apartment, or more frequent luxury dining. While these upgrades are understandable human desires, they are the primary reason why high-income earners often find themselves living paycheck to paycheck. Wealth management is not about how much you make; it is about how much you keep.

    To avoid this trap, you must consciously decouple your lifestyle from your earnings. The moment you earn more, your first instinct should not be to increase your consumption, but to increase your savings and investment rate. This is the difference between a consumer mindset and a wealth-builder mindset. By maintaining a relatively stable standard of living while your income grows, you widen the gap between your earnings and your expenses. That gap, when consistently invested, is the fuel that powers compounding returns and leads to long-term financial independence.

    Identifying lifestyle inflation requires rigorous honesty about what constitutes a “need” versus a “want.” Many people frame luxury items as necessities, masking the fact that they are trading away their future freedom for present-day status symbols. Financial literacy includes the ability to pause and evaluate the long-term impact of current spending choices. If you can learn to find satisfaction in the progress of your net worth rather than the appearance of your lifestyle, you will possess a competitive advantage over the vast majority of your peers. Being mindful of your spending habits is not about deprivation; it is about intentionality. It is about deciding that the future version of yourself, who is financially secure and free from the stress of debt, is more important than the temporary thrill of a purchase that will lose its luster in a few weeks. By keeping your expenses lean even as you prosper, you ensure that your wealth continues to accumulate at an exponential rate, ultimately granting you the freedom to choose how you spend your time and energy.

    The Risks of Investing Without a Long-Term Strategy

    Many individuals enter the investment landscape with a desire for quick returns, often driven by the excitement of market volatility or the latest trends. However, failing to establish a long-term strategy is one of the most significant money mistakes to avoid. Without a roadmap, your investment portfolio becomes a collection of reactive decisions rather than a purposeful engine for wealth accumulation.

    When you lack a long-term strategy, you are susceptible to “emotional investing.” This is the tendency to buy high when markets are euphoric and sell low when markets experience a temporary downturn. This cycle effectively cannibalizes your potential gains and prevents the magic of compounding interest from working in your favor. A long-term approach, by contrast, focuses on time in the market rather than timing the market. By establishing clear goals—whether it is funding a child’s education, purchasing real estate, or preparing for a comfortable retirement—you provide yourself with a psychological anchor that keeps you steady during periods of volatility.

    Furthermore, an unstrategic approach often ignores the critical balance of asset allocation. Investors without a plan may find themselves inadvertently over-concentrated in a single sector, geography, or asset class. If that specific area faces a downturn, the impact on your net worth can be catastrophic. True wealth management involves diversification across various asset classes, such as equities, bonds, and perhaps alternative investments, tailored to your specific risk tolerance and time horizon.

    Consider the difference between a speculative approach and a strategic, disciplined portfolio:

    Investment Approach Core Philosophy Typical Holding Period Best For
    Speculative Trading Chasing short-term price fluctuations Days to weeks High-risk capital only
    Buy-and-Hold Investing Capturing long-term market growth Years to decades Wealth building and retirement
    Dollar-Cost Averaging Reducing entry point risk Ongoing consistency Steady, risk-averse investors
    Asset Allocation Managing risk through diversity Balanced lifecycle Preserving and growing net worth

    Why Failing to Optimize Taxes Limits Your Net Worth Growth

    Tax drag is the silent killer of wealth. Many people mistakenly believe that their only responsibility is to pay taxes as calculated by their employer or government software at the end of the year. However, high-net-worth individuals and successful long-term investors understand that tax-efficient wealth management is a cornerstone of financial education. When you fail to optimize your tax liability, you are essentially leaving money on the table that could have been reinvested to generate further growth.

    The primary pitfall here is failing to utilize tax-advantaged accounts. Whether it is a 401(k), an IRA, or other localized investment accounts designed to shield your growth from immediate taxation, these tools are essential. By contributing to accounts that offer tax-deferred or tax-free growth, you allow your capital to compound without the annual erosion caused by capital gains taxes or dividend taxes. If you withdraw funds from these accounts prematurely or prioritize taxable accounts without necessity, you incur unnecessary costs that compound negatively over time.

    Additionally, investors often fail to practice “tax-loss harvesting.” This strategy involves selling investments that have declined in value to offset capital gains realized from other assets. While this should not be the primary driver of any investment decision, it is a sophisticated method of lowering your annual tax burden. Similarly, failing to understand how different types of income (ordinary income versus long-term capital gains) are taxed can lead to poor decision-making regarding which assets to hold in which accounts. Aligning your asset location—placing tax-inefficient assets in tax-sheltered accounts—is a vital wealth management tip that can improve your net-of-tax returns by significant margins over a lifetime.

    The Importance of Consistent Financial Tracking and Review

    Financial literacy is not a one-time achievement; it is a lifestyle of constant observation. One of the most common money mistakes to avoid is the “set it and forget it” mindset regarding your household budget and net worth. If you are not tracking where your money goes, you have no way of knowing if your current trajectory aligns with your financial goals.

    Tracking your finances provides two critical benefits: awareness and accountability. Awareness helps you identify “lifestyle creep”—the tendency to increase spending as your income rises. Without consistent review, it is easy for small, recurring expenses to balloon, absorbing capital that could have been directed toward debt repayment or investments. Accountability, on the other hand, allows you to evaluate your progress. Are you hitting your savings milestones? Are your investments performing within the expected range for your risk profile? Regular reviews allow you to pivot when life circumstances change, such as a career transition, a new family member, or a change in regional economic conditions.

    We recommend a monthly “financial summit” with yourself or your partner. During this time, look at three things: your total net worth, your savings rate, and your progress toward specific goals. Tracking these metrics over years provides a visual map of your wealth creation journey, which serves as a powerful motivator to stay the course even when external economic pressures arise.

    Common Pitfalls When Planning for Retirement

    Retirement planning is often the most significant financial project an individual will undertake. Unfortunately, many approach it with dangerous assumptions that can lead to a shortfall in their later years. One major pitfall is underestimating the cost of longevity. With medical advancements, people are living longer, meaning your retirement nest egg must support you for 30 or even 40 years. Relying solely on a pension or government benefits is typically insufficient for a lifestyle that maintains your pre-retirement standards.

    Another common mistake is failing to account for inflation. While your expenses may seem manageable today, the rising cost of goods, services, and especially healthcare can drastically reduce your purchasing power over two decades. If your retirement savings are held entirely in low-yield cash accounts to “play it safe,” inflation will effectively decrease the value of your wealth every year. You must ensure your retirement allocation includes growth-oriented assets that have historically outpaced the rate of inflation.

    Finally, there is the risk of the “one-size-fits-all” withdrawal strategy. Many retirees follow a standard percentage withdrawal rule without considering market conditions. If you withdraw a high percentage of your portfolio during a market downturn, you deplete your capital base, making it much harder for your account to recover when the market eventually turns upward. Flexibility in your withdrawal rate—spending less during lean market years—is a sophisticated strategy that can significantly extend the life of your retirement fund.

    How to Improve Your Financial Literacy for Long-Term Success

    Improving your financial literacy is an ongoing commitment, but it is one that pays the highest interest. You do not need to be an expert in economics to master your own wealth; you simply need to build a framework for continuous learning. Start by curating your information sources. There is a vast amount of “noise” in the financial media world, much of which is designed to incite fear or FOMO (fear of missing out). Prioritize reputable sources that focus on long-term wealth management principles rather than daily stock market gossip.

    Practical application is the fastest way to learn. After reading a concept—such as the power of compound interest or the basics of diversification—try to calculate how it applies to your own situation. If you are reading about index fund investing, look at the expense ratios of the funds currently in your portfolio. If you are reading about debt management, calculate the interest you are paying annually on your credit cards. These exercises move knowledge from abstract theory to tangible reality.

    Finally, engage with a community of like-minded individuals. Whether it is through financial seminars, educational forums, or consultation with a fee-only financial planner, surrounding yourself with others who prioritize financial health can reinforce your discipline. Remember that financial literacy is the foundation of freedom. The more you understand, the less you have to rely on guesswork, and the more confident you will become in the decisions that shape your future.

    Frequently Asked Questions

    What is the most important first step to take when trying to build wealth?

    The most important first step is establishing a clear understanding of your current financial situation, including your total income, expenses, assets, and liabilities. Once you have a transparent view of your finances, the next step is to create a budget that prioritizes saving and investing before discretionary spending. Without this foundation, it is impossible to set effective goals or measure your progress toward long-term wealth.

    How much of my income should I be saving every month?

    While there is no single rule that applies to everyone, many experts recommend a “pay yourself first” approach, aiming to save at least 15% to 20% of your gross income. However, if you are starting later in life or have aggressive retirement goals, you may need to save more. The key is to start with a percentage you can consistently maintain and gradually increase it as your income grows.

    Is it better to pay off debt or invest my money?

    This decision typically depends on the interest rate of your debt compared to the potential return on your investments. Generally, high-interest debt, such as credit card balances, should be paid off immediately because the interest cost significantly outweighs most long-term investment gains. For low-interest debt, such as a fixed-rate mortgage, many people choose to pay the minimum and invest their surplus capital, as the stock market may offer a higher historical average return over time.

    What does “tax-efficient investing” actually mean?

    Tax-efficient investing refers to strategies that minimize the amount of taxes you pay on your investment returns. This includes using tax-advantaged accounts like 401(k)s or IRAs, holding assets for more than a year to qualify for lower long-term capital gains tax rates, and utilizing tax-loss harvesting to offset gains. The goal is to keep more of your earnings so they can continue to compound over the long term.

    How often should I review my investment portfolio?

    A portfolio review should typically occur on a semi-annual or annual basis. You should check your asset allocation to ensure that market movements haven’t shifted your portfolio too far from your target risk profile. Avoid checking your portfolio daily or weekly, as this can lead to emotional decision-making based on short-term market noise rather than your long-term strategy.

    When should I hire a financial advisor?

    You might consider hiring a financial advisor when your financial situation becomes complex—such as when you begin estate planning, managing significant tax burdens, or navigating specific retirement income scenarios. A fee-only advisor can provide an objective perspective and professional expertise that helps you avoid common pitfalls. Always ensure your advisor acts in a fiduciary capacity, meaning they are legally obligated to act in your best interest.

    Conclusion

    Building wealth is rarely about finding the next “hot” stock or striking it lucky; it is about consistency, patience, and the avoidance of common, costly mistakes. By prioritizing financial education, maintaining a long-term strategy, optimizing your tax exposure, and regularly tracking your net worth, you take control of your financial destiny. The path to wealth is available to anyone willing to put in the work to learn and apply these fundamental principles. Start today by reviewing your current savings rate and checking your investment accounts for unnecessary fees or lack of diversification. Your future self will thank you for the discipline you exert today.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.

  • Tax-Efficient Withdrawal Strategy: How to Make Wealth Last

    Tax-Efficient Withdrawal Strategy: How to Make Wealth Last

    Key Takeaways

    • Your withdrawal sequence is as important to your total wealth as your initial investment returns.
    • Diversifying across tax-deferred, tax-free, and taxable accounts provides the flexibility needed to navigate changing tax laws.
    • Strategic tax planning in retirement allows you to minimize the lifetime tax bite on your hard-earned savings.
    • Roth conversions can be a powerful tool to lower long-term tax liabilities, provided they are timed correctly.
    • Managing Required Minimum Distributions (RMDs) is essential to avoid being pushed into higher tax brackets later in life.

    For many investors, the accumulation phase of life is spent focusing on growth, dividends, and asset allocation. However, the transition from accumulating wealth to spending it requires an entirely different mindset. Many retirees mistakenly believe that once they stop earning a salary, their tax burden effectively disappears. In reality, the way you choose to harvest your nest egg can make the difference between a comfortable, sustainable lifestyle and one that is prematurely depleted by avoidable tax bills. A well-constructed withdrawal strategy is the silent engine of your financial security; it ensures that every dollar you withdraw is done with the goal of maximizing your net purchasing power and protecting your legacy. By understanding the intersection of investment account types and tax policy, you can craft a retirement income plan that makes your wealth last significantly longer.

    Why Your Withdrawal Order Determines Your Total Wealth

    The sequence in which you liquidate your assets is not merely a logistical choice; it is a fundamental pillar of retirement tax planning. When you retire, your total wealth is distributed across various accounts, each governed by different tax rules. If you tap into these accounts in the wrong order, you may find yourself paying unnecessary taxes, losing potential market growth, and potentially pushing yourself into higher tax brackets. The primary objective of a sound withdrawal strategy is to extend the longevity of your portfolio by minimizing the amount of capital that goes to the government in the form of taxes rather than into your own pocket.

    Consider the impact of tax drag. If you withdraw funds from a taxable account while leaving tax-advantaged accounts untouched, you might be paying taxes on capital gains and dividends today that could have been deferred. Conversely, draining your tax-deferred accounts too early can lead to a massive, immediate tax bill that shrinks your principal balance, leaving less money invested to compound over the long term. This loss of compounding is arguably the most significant cost of a poor withdrawal strategy.

    Furthermore, your withdrawal order dictates your eligibility for certain benefits and your susceptibility to surcharges. Many government-sponsored healthcare programs, for example, base premiums on your modified adjusted gross income. If your withdrawal strategy results in a high annual income, you may inadvertently trigger higher premiums, effectively raising your cost of living. A deliberate strategy—one that balances withdrawals across multiple “buckets”—allows you to manage your reported income, keeping it low enough to qualify for favorable rates and deductions while still meeting your lifestyle needs.

    Wealth-building isn’t just about what you save; it’s about what you keep. By strategically choosing which assets to sell first, you are essentially “tax-bracket management” in real-time. Experts generally agree that a flexible approach is superior to a rigid, one-size-fits-all rule. As tax codes change and the market fluctuates, your withdrawal strategy must adapt. Whether you are living off dividends, selling appreciated assets, or taking distributions from retirement accounts, each decision ripples forward, affecting the composition of your remaining wealth. Understanding that your strategy serves as a gatekeeper for your total net worth is the first step toward true financial autonomy in retirement.

    Understanding Tax Buckets: Tax-Deferred vs Tax-Free vs Taxable

    To master your withdrawal strategy, you must first categorize your assets into three distinct “tax buckets.” Each bucket behaves differently under the scrutiny of the tax code, and understanding these differences is critical for effective tax-efficient investing.

    The Tax-Deferred Bucket: This includes traditional 401k plans and traditional IRAs. Contributions to these accounts were typically made with pre-tax dollars, meaning you haven’t paid income tax on them yet. When you withdraw these funds, every dollar is treated as ordinary income. This bucket is the most common target for retirees, but it is also the most dangerous to deplete without a plan. Because you are essentially carrying a “tax liability” for the government inside your portfolio, taking too much too quickly can lead to a significant portion of your wealth being eroded by income tax.

    The Tax-Free Bucket: This includes Roth IRAs and Roth 401k accounts. These funds have already been taxed at the time of contribution. Consequently, qualified withdrawals are entirely tax-free. This bucket is an incredibly valuable resource for managing your tax bracket in retirement. When you need a large purchase—like a new car or an emergency home repair—pulling from the tax-free bucket allows you to cover the expense without adding to your taxable income for the year.

    The Taxable Bucket: This includes standard brokerage accounts, savings accounts, and certain types of bonds. These accounts don’t offer the same tax-deductible benefits as retirement plans, but they do offer lower long-term capital gains tax rates on growth. These accounts are often the most liquid and provide a valuable buffer during years when you want to minimize your reported income to stay in a lower tax bracket.

    Account Type Tax Treatment Best For
    Taxable Brokerage Capital gains rates Flexibility & Liquidity
    Traditional 401k/IRA Ordinary income Funding base expenses
    Roth IRA/401k Tax-free Bracket management

    By balancing these buckets, you create a “dial” that you can turn to control your tax burden year after year. For example, if you anticipate a year where you have high expenses, you can augment your taxable withdrawals with Roth withdrawals to ensure you don’t jump into a higher tax bracket, thereby keeping your overall wealth intact.

    The Ideal Sequence: When to Tap Each Investment Account

    There is no universal “ideal” sequence, but there is a logic that successful retirees follow to ensure their portfolio remains tax-efficient. Generally, the strategy involves harvesting assets that provide the most benefit to your long-term wealth preservation without triggering unnecessary tax events.

    Many financial experts suggest a “Tax-Efficient Withdrawal Order” that typically starts with the taxable brokerage account. By exhausting the growth in your taxable accounts first, you allow your tax-deferred and tax-free investments more time to compound. Because the gains in your taxable account are usually taxed at the lower long-term capital gains rate (assuming assets are held for more than a year), this can be an effective way to lower your immediate tax bill.

    Once the taxable account is depleted, the focus often shifts to the tax-deferred accounts. However, this is where the strategy becomes nuanced. You don’t necessarily want to drain your 401k entirely, as it will become a source of required income later. Instead, many retirees pull just enough from the traditional 401k or IRA to fill up their current tax bracket—meaning, they withdraw an amount that keeps them at the top of a lower, more favorable bracket. Any expenses exceeding that amount are then covered by the tax-free Roth accounts.

    The “Tax-Free Bucket” should be treated with care. Because Roth assets grow tax-free indefinitely and are not subject to the same withdrawal requirements as traditional accounts, they are often the best assets to hold for the “long haul” or to pass on as an inheritance. However, they are also your best tool for managing tax-bracket creep. If you find yourself needing extra cash in a year where you have already reached the ceiling of your desired tax bracket, pulling the remainder from your Roth IRA is the ideal solution, as it adds zero dollars to your adjusted gross income.

    This tiered approach requires discipline. It means resisting the urge to spend down your Roth accounts early because they feel “easy” or “tax-free.” Instead, treat them as your strategic reserve. By sequencing your withdrawals—starting with taxable assets, utilizing tax-deferred assets to fill lower tax brackets, and using Roth assets as a flexible top-off—you effectively smooth out your income, keep your tax obligations predictable, and keep your total wealth working for you in the market as long as possible.

    The Role of Required Minimum Distributions in Your Strategy

    The government requires that you begin taking distributions from your tax-deferred accounts—like your traditional 401k and traditional IRA—once you reach a certain age. These are known as Required Minimum Distributions (RMDs). For many, RMDs represent a significant “tax trap.” They force you to withdraw a specific percentage of your balance each year, regardless of whether you actually need the money or whether the market is currently experiencing a downturn.

    RMDs are problematic because they are considered ordinary income. If you have been diligent about saving throughout your career, your RMDs can be quite substantial. These forced withdrawals can push you into a significantly higher tax bracket, increase the percentage of your Social Security benefits that are subject to taxation, and escalate your healthcare premiums. If you ignore RMDs, the penalties are notoriously steep, making it a critical component of your retirement tax planning that cannot be overlooked.

    A proactive withdrawal strategy attempts to mitigate the “RMD spike” long before it happens. If you know that your RMDs will be high, it may be beneficial to take larger, voluntary withdrawals from your tax-deferred accounts earlier in retirement—during those years when your income is lower—to “smooth out” the tax impact. By taking money out when your tax rate is lower, you reduce the balance of the account that will eventually be subject to RMDs, thereby shrinking the future mandatory distributions.

    Furthermore, managing your RMDs often involves a “fill the bracket” philosophy. If you are in a low-tax-bracket year early in retirement, consider withdrawing more than your current expenses from your tax-deferred account and reinvesting the surplus into a taxable account or, if you are eligible, using it to fund a Roth conversion. While this seems counterintuitive because it involves paying taxes today, you are essentially buying a lower tax rate today to avoid a potentially higher, mandatory tax rate tomorrow. This is the essence of long-term wealth preservation: making small, calculated tax payments now to avoid large, unavoidable tax bills later that could jeopardize the longevity of your portfolio.

    How to Use Roth Conversions to Smooth Out Future Tax Brackets

    A Roth conversion is the process of moving funds from a tax-deferred account (like a traditional IRA) to a tax-free account (like a Roth IRA). When you perform this conversion, you must pay income tax on the amount converted in the year the move occurs. At first glance, paying taxes now might seem like the opposite of tax-efficient investing, but when viewed through the lens of your lifetime tax bill, it is often a brilliant strategic maneuver.

    The primary goal of a Roth conversion is to manage your tax brackets over the long term. If you believe your future tax rate will be higher than your current rate—perhaps because you expect large RMDs or changes in tax legislation—converting now allows you to “lock in” your current rate. By converting moderate amounts over several years, you can avoid the “tax spike” that often occurs when RMDs kick in, creating a more level and predictable income stream throughout your retirement.

    Timing is everything when it comes to conversions. The “sweet spot” is typically the window between the day you retire and the day your RMDs begin. During these years, you may have little to no earned income, putting you in a lower tax bracket. By utilizing this period to convert funds, you can shift money from your traditional IRAs to your Roth IRAs at a bargain price. You are essentially shifting wealth into a tax-free container while the tax cost is manageable, significantly reducing the future tax liability on that portion of your assets.

    Another strategic benefit of Roth conversions is the impact on your heirs. Roth accounts generally do not have the same RMD requirements during your lifetime, and they can be passed on to beneficiaries as tax-free growth vehicles. This makes them a superior tool for wealth transfer. However, because conversions are irreversible, they must be done with precision. You need to ensure you have the cash on hand outside of the retirement account to pay the taxes generated by the conversion, as using retirement funds to pay the tax bill itself can negate the efficiency of the strategy. As with all things in retirement, consistency and long-term planning are the hallmarks of those who successfully preserve their wealth against the inevitable erosion of taxes.

    Managing Capital Gains and Dividends for Lower Tax Rates

    When you transition from the accumulation phase to the distribution phase of your retirement, the nature of your income changes. While you once relied primarily on earned income, your wealth is now generating returns through dividends and capital gains. Understanding how these are taxed is a cornerstone of an effective withdrawal strategy. Unlike ordinary income—which is taxed at your marginal tax rate—long-term capital gains and qualified dividends are subject to preferential, lower tax rates.

    To minimize your tax burden, you must distinguish between your investment vehicles. Assets held in a taxable brokerage account are the primary targets for tax-efficient management. In these accounts, every sale of an appreciated asset triggers a taxable event. By adopting a “buy and hold” philosophy and utilizing tax-loss harvesting, you can manage the timing of these gains to align with your overall retirement income needs. For example, if you have a year where your income is lower than usual, that may be the opportune time to realize long-term capital gains, potentially even qualifying for the zero-percent long-term capital gains tax bracket.

    Dividends, however, require a different approach. Qualified dividends receive the same favorable tax treatment as long-term capital gains. If your portfolio is heavy on dividend-paying stocks, you can generate a significant portion of your annual retirement income at these lower rates, rather than withdrawing from a 401(k) or traditional IRA, which would be taxed as ordinary income. Always ensure your portfolio is diversified, as chasing high dividend yields can sometimes lead to unexpected capital depreciation.

    The Impact of Social Security Benefits on Your Withdrawal Plan

    Social Security is often the bedrock of retirement income, but it acts as a “tax multiplier” in your withdrawal plan. This occurs because the amount of Social Security benefits subject to federal income tax is determined by your “combined income.” Combined income is your adjusted gross income plus non-taxable interest, plus one-half of your Social Security benefits. As you withdraw more money from your tax-deferred accounts—like a traditional 401(k) or IRA—to cover living expenses, you inadvertently push your combined income higher.

    This dynamic can lead to a “tax torpedo,” where the inclusion of your Social Security benefits into your taxable income pushes you into a higher tax bracket, effectively increasing your marginal tax rate on those very withdrawals. Strategic retirement planning requires you to model how your withdrawal sequence interacts with your Social Security claiming age. Delaying Social Security benefits, while often beneficial for increasing the monthly payout, also delays the point at which your combined income calculations begin to impact your tax liability.

    Consider the table below to understand how different income sources impact your overall tax profile during retirement:

    Income Source Tax Treatment Impact on Social Security Taxation Best For
    Traditional 401(k)/IRA Ordinary Income High Deferring taxes during high-earning years
    Roth IRA/401(k) Tax-Free None Tax-free growth and liquidity
    Taxable Brokerage Capital Gains Rates Low Tax-efficient wealth preservation
    Social Security Partially Taxed N/A Guaranteed lifelong income

    Common Withdrawal Mistakes That Drain Wealth Prematurely

    One of the most frequent errors retirees make is the “default withdrawal” approach—simply taking money from the account with the highest balance or the one that is easiest to access. Without a formal withdrawal strategy, you may inadvertently liquidate assets that were intended for long-term growth or incur avoidable tax penalties. Another major pitfall is failing to account for Required Minimum Distributions (RMDs). Once you reach the age mandated by current legislation, you must withdraw a specific amount from your tax-deferred accounts. If you haven’t planned for this, these RMDs can force you into a higher tax bracket and limit your ability to manage your tax exposure for the remainder of the year.

    Another common mistake is neglecting the impact of healthcare costs and Medicare Part B/D surcharges (IRMAA). Your income level dictates the premiums you pay for Medicare. If you withdraw a large sum from your retirement accounts to fund a one-time purchase or trip, you might find yourself hit with an IRMAA surcharge two years later, effectively increasing your healthcare costs because your income two years prior exceeded certain thresholds. Wealth preservation is as much about controlling outflows—especially taxes and surcharges—as it is about market returns.

    How to Rebalance Your Portfolio While Withdrawing Assets

    Rebalancing is the process of realigning the weightings of a portfolio of assets. In your accumulation years, you likely rebalanced by buying more of the underperforming asset classes. In retirement, rebalancing is even more critical because you need to ensure you are not forced to sell “low” during a market downturn just to generate cash for living expenses. The most tax-efficient way to rebalance is to use your required withdrawals as a mechanism for rebalancing.

    Instead of selling assets specifically to rebalance, identify which portions of your portfolio have grown beyond their target allocation. If you need to withdraw cash, sell those over-weighted assets to fulfill the distribution. This strategy accomplishes two goals: it provides you with the liquidity you need for retirement, and it brings your portfolio back to your target asset allocation without triggering unnecessary trades that could result in transaction costs or capital gains taxes. If your account is tax-advantaged, such as an IRA, you can rebalance frequently without worrying about capital gains consequences, allowing you to maintain your desired risk profile throughout your golden years.

    Frequently Asked Questions

    What is the most tax-efficient order for withdrawing retirement funds?

    Generally, experts recommend a strategy that begins with taxable accounts, followed by tax-deferred accounts (like a 401(k) or traditional IRA), and finally tax-free accounts (like a Roth IRA). By letting your tax-advantaged accounts grow as long as possible, you maximize the power of tax-deferred or tax-free compounding. However, this should always be balanced against your specific marginal tax bracket for each year.

    How can I avoid the “tax torpedo” related to Social Security?

    You can mitigate the impact of the tax torpedo by managing your taxable income through strategic withdrawals. By utilizing tax-free income from Roth accounts or returns from taxable brokerage accounts (which may be taxed at lower capital gains rates), you can keep your “combined income” below the thresholds that trigger higher taxation on your Social Security benefits.

    Is a Roth conversion always a good idea?

    A Roth conversion can be a powerful tool, but it is not universally beneficial. It is typically most effective when your current tax bracket is lower than what you expect your tax bracket to be in the future, or when you wish to minimize RMDs later in life. You must have the cash available outside of the retirement account to pay the taxes incurred during the conversion process.

    How do Required Minimum Distributions (RMDs) affect my tax planning?

    RMDs are mandatory withdrawals from tax-deferred accounts that start at a specific age. Because they are taxed as ordinary income, they can significantly increase your annual tax liability. Effective planning involves anticipating the size of these distributions early and potentially performing Roth conversions or charitable qualified distributions (QCDs) to lower your future RMD burden.

    What role do tax-loss harvesting play in a retirement withdrawal strategy?

    Tax-loss harvesting involves selling investments that have lost value to offset capital gains realized elsewhere in your portfolio. In retirement, this can be an essential strategy for keeping your taxable income low while still liquidating assets from your brokerage account, allowing you to rebalance your holdings without triggering a large tax bill.

    Can I rebalance my portfolio without incurring taxes?

    Yes, if your assets are held within tax-advantaged accounts like an IRA or 401(k), you can buy and sell assets to rebalance your portfolio without incurring immediate capital gains taxes. In a taxable brokerage account, you will trigger taxes on any gains when you sell, so rebalancing there should be done strategically, perhaps by using new contributions or dividends to purchase underweighted asset classes rather than selling winners.

    Conclusion

    Building wealth is only half the journey; the other half is successfully managing that wealth so it lasts throughout your retirement. A tax-efficient withdrawal strategy is not a “set it and forget it” process. It requires ongoing vigilance regarding market conditions, changing tax legislation, and your own evolving income needs. By thoughtfully sequencing your withdrawals, managing your capital gains, and being mindful of how your income sources interact with Social Security and Medicare, you can significantly improve the longevity of your portfolio.

    Your goal is to retain as much of your hard-earned wealth as possible, leaving less to the tax authorities and more for your personal lifestyle and legacy goals. Take the time to audit your current accounts, understand your projected RMDs, and consult with a tax-focused financial professional to build a roadmap tailored to your specific situation. The peace of mind that comes with a well-structured plan is perhaps the most valuable asset of all.

    Take action today: Start by mapping out your expected income sources for the next five years. Identify which of your accounts are taxable, tax-deferred, and tax-free, and begin prioritizing your withdrawals to ensure you are not paying more in taxes than necessary.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.