- A health savings account (HSA) offers a unique triple-tax advantage that remains unmatched by most other retirement vehicles.
- To maximize wealth, you must view your HSA as a long-term investment account rather than a simple vehicle for immediate medical expenses.
- HSA eligibility is strictly tied to enrollment in a High Deductible Health Plan (HDHP).
- Transitioning your account into an investment vehicle requires active management and a focus on long-term portfolio growth.
- Prioritizing an HSA over a 401k depends on employer matching, tax brackets, and your current health care expenditure needs.
For many, a health savings account (HSA) is seen merely as a convenient way to pay for deductibles and prescription co-pays. However, astute investors have long recognized that this account type is arguably the most powerful tool for building wealth in the modern financial landscape. By treating the HSA not as a short-term spending account but as a tax-advantaged investment engine, individuals can create a significant financial cushion for their golden years. This guide explores the mechanics of HSA investing, providing the actionable insights needed to leverage this account for long-term financial independence.
What Is an HSA and Why Is It More Than a Savings Account
At its core, a health savings account is a tax-advantaged financial product designed for individuals who have a high-deductible health plan (HDHP). Unlike a traditional flexible spending account (FSA), which often operates on a “use it or lose it” basis, an HSA stays with you for life. The funds in your account roll over from year to year, allowing the balance to grow indefinitely. While many people open these accounts specifically to cover the out-of-pocket costs associated with their health insurance plan, the true potential of an HSA lies in its ability to function as an investment vehicle.
When you use an HSA strictly for immediate medical expenses, you are capturing only a fraction of its value. To truly maximize your wealth, you must shift your perspective. Think of your HSA as a specialized retirement account that just happens to be earmarked for health-related costs. Because medical expenses often become a significant portion of an individual’s budget during retirement, having a dedicated, tax-free reservoir of funds is a major strategic advantage.
The transition from a “savings account” to an “investment vehicle” happens when you begin to contribute more than you spend on current medical needs. Once your balance reaches a certain threshold—often set by the account provider—many institutions allow you to invest those funds in stocks, bonds, and mutual funds. Over several decades, the power of compounding interest transforms these contributions into a substantial nest egg. By paying for current out-of-pocket medical costs with out-of-pocket cash instead of HSA funds, you allow your HSA balance to remain untouched and grow in the market. This is the hallmark of sophisticated wealth building. You are effectively using your HSA as a “supercharged” IRA that provides extra flexibility when you reach retirement age.
Furthermore, an HSA is portable. It is not tied to your current employer. If you change jobs, the account moves with you. This stability allows you to cultivate a long-term strategy without worrying about administrative disruption. As you mature in your career, the account acts as a secondary layer of financial security. If you ever face a significant health event, you have the liquidity to handle it without dipping into your 401k or brokerage accounts. If you remain healthy, the funds continue to accumulate until you eventually withdraw them for any purpose—or for qualified medical expenses—at which point you enjoy the full benefit of your earlier patience and disciplined investing.
Understanding the Triple-Tax Advantage Explained
The “triple-tax advantage” is the cornerstone of why experts frequently cite the HSA as the most efficient tax-advantaged account available today. This three-pronged benefit applies to contributions, growth, and withdrawals, creating a cycle of tax efficiency that is difficult to replicate in other investment vehicles. Understanding these three pillars is essential for anyone interested in building wealth through an HSA.
First, contributions are made on a pre-tax or tax-deductible basis. If your employer offers a payroll deduction for an HSA, those funds are taken out before federal income taxes are applied. This reduces your overall taxable income for the year, effectively lowering the cost of your contribution. If you contribute individually, you can deduct those contributions from your gross income when you file your taxes, providing a similar benefit. This initial tax shield means you are investing “more” of your dollar because less of it was diverted to taxes in the first place.
Second, the account benefits from tax-deferred or tax-free growth. Just like a 401k or an IRA, the assets held within your HSA are not subject to capital gains taxes or dividend taxes while they remain in the account. This is a critical component of wealth building. In a standard brokerage account, you might pay taxes every time a dividend is paid or whenever you rebalance your portfolio by selling an asset. In an HSA, these transactions occur behind a tax-protected wall. This allows your dividends and capital gains to be reinvested in full, significantly accelerating the compounding process over twenty or thirty years. The difference between taxed and tax-free compounding is substantial over long horizons.
Third, withdrawals for qualified medical expenses are entirely tax-free. This is the final piece of the puzzle. When you reach retirement, you can use your accumulated wealth to pay for medical care, prescription drugs, or long-term care premiums without owing a single cent to the IRS. While most retirement accounts (like traditional 401ks) tax your distributions as ordinary income, the HSA allows you to access your money tax-free for healthcare. Even if you choose to withdraw funds for non-medical reasons after the age of 65, you simply pay standard income tax on the withdrawal, effectively treating the account like a traditional IRA. This inherent flexibility—combined with the primary tax-free medical benefit—is why so many investors prioritize their HSA contributions as a central pillar of their long-term financial health.
HSA Eligibility: Who Can Open and Contribute to an Account
While the benefits are undeniably attractive, not everyone is eligible to open or contribute to a health savings account. Eligibility is strictly governed by the IRS and is tied to your health insurance coverage. To be considered an “eligible individual,” you must be covered by a High Deductible Health Plan (HDHP). The IRS sets specific annual minimum deductibles and maximum out-of-pocket limits that determine whether a plan qualifies as an HDHP.
Beyond being enrolled in an HDHP, there are a few other essential criteria. First, you cannot be covered by any other “non-HDHP” health insurance, such as a spouse’s traditional plan or a general-purpose flexible spending account. This rule is designed to ensure that the HSA is used exclusively by those who bear a higher degree of immediate financial responsibility for their healthcare. Second, you generally cannot be enrolled in Medicare. Once you become eligible for Medicare—typically at age 65—you can no longer make new contributions to your HSA, though you can continue to use the funds already in the account for qualified medical expenses. Finally, you cannot be claimed as a dependent on someone else’s tax return.
It is important to keep track of these eligibility rules annually. Your health insurance status can change due to employment shifts, open enrollment selections, or life events. If you are only eligible for part of the year, you may be subject to prorated contribution limits. Staying within the IRS-mandated limits is crucial to avoid tax penalties or unnecessary administrative hurdles. Most employers or HSA custodians will provide documentation confirming your eligibility or reminding you of the contribution ceilings for the tax year.
For those who are eligible, the contribution process is straightforward. You can contribute up to the annual limit established by the IRS, which is adjusted for inflation periodically. It is often wise to check these limits every January to ensure you are maximizing your tax advantage. Some employers also provide an “employer contribution” to your HSA as part of your benefits package. This is essentially free money—an immediate return on your investment—and it should be factored into your total financial planning. If you are eligible, prioritizing this account can serve as a foundational step toward a more secure financial future, providing both immediate tax savings and a long-term growth engine for your retirement years.
How to Transition Your HSA From Savings to Investment Vehicle
Transitioning your HSA from a stagnant savings account to a dynamic investment vehicle is a tactical shift that separates casual savers from serious wealth builders. Most HSAs begin as cash-heavy accounts, often earning negligible interest that barely keeps pace with inflation. If you want to build genuine wealth, you must move that capital into the financial markets. The transition typically involves three distinct stages: meeting the threshold, selecting your investment strategy, and managing the long-term allocation.
Most HSA providers require that you maintain a minimum cash balance (often $1,000 to $2,000) before you are permitted to invest the remaining funds. Your first goal should be to reach this minimum balance as quickly as possible. Once you pass that hurdle, you should enable the investment feature within your custodian’s portal. Many modern HSA providers have simplified this process, allowing you to choose from a selection of low-cost index funds or target-date retirement funds similar to those found in a 401k or IRA.
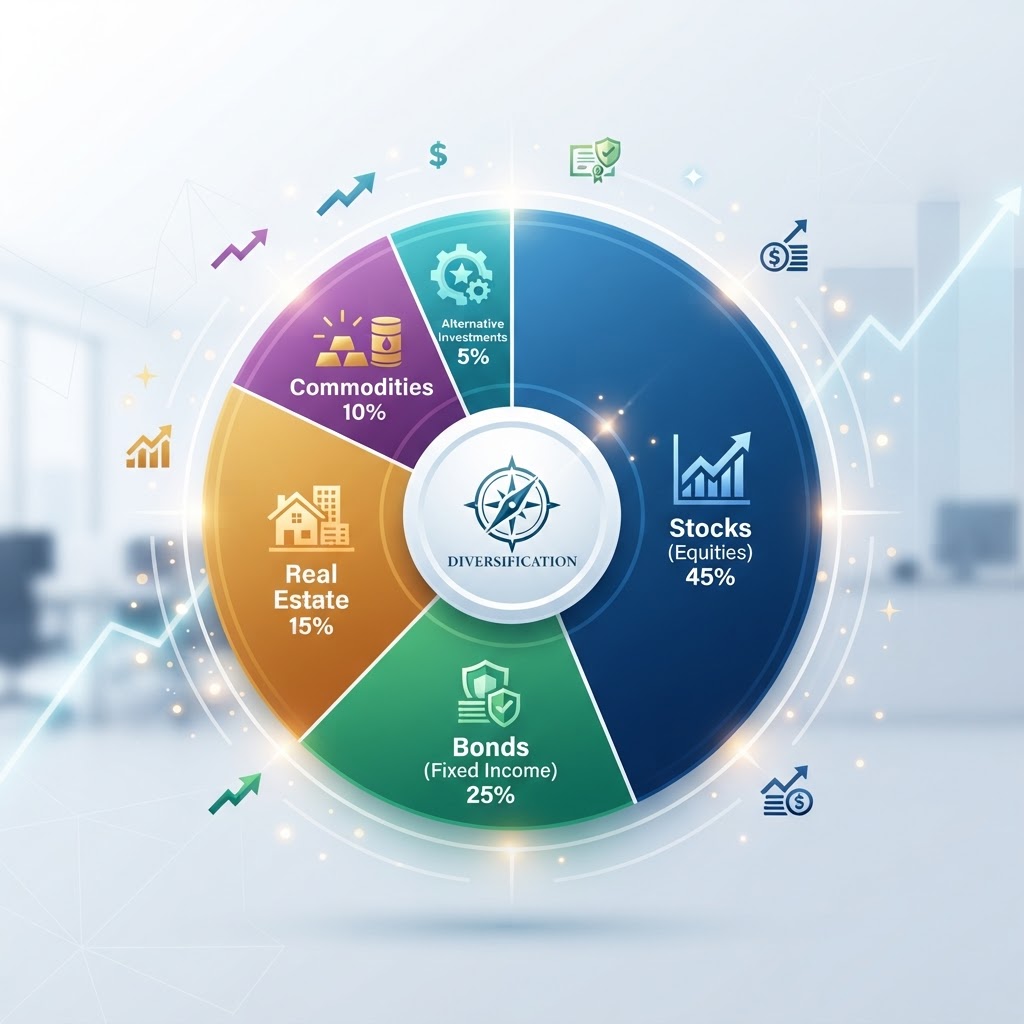
When selecting investments, consider your timeline. If you are decades away from retirement, a growth-oriented approach with a higher percentage of total stock market index funds is typically recommended. Because the HSA is a long-term play, you can afford to ride out the volatility of the stock market. You should view this account as a complement to your other assets. If your 401k is heavily invested in domestic equities, you might consider adding international exposure to your HSA to ensure your overall net worth remains well-diversified.
Automation is your greatest ally in this transition. Just as you contribute to your 401k through automatic payroll deductions, you should automate your HSA contributions. Many providers also allow you to “auto-invest” any amount above your threshold. This means that as your contributions accrue, the funds are automatically moved from your cash balance into your selected investments. This “set it and forget it” strategy ensures that you aren’t leaving money on the table in a low-interest cash account. Periodically, perhaps once or twice a year, you should log in to rebalance your holdings, ensuring that your HSA remains aligned with your overall risk tolerance and wealth goals.
| Account Type | Core Benefit | Best For |
|---|---|---|
| HSA | Triple-tax advantage | High-deductible health plan enrollees |
| 401k | Employer matching | Employees with company matches |
| Roth IRA | Tax-free growth and access | Diversifying tax exposure in retirement |
HSA vs 401k: Which Account Should You Prioritize First
Deciding whether to prioritize an HSA or a 401k is a common dilemma for investors looking to optimize their retirement contributions. While both are powerful, they serve different primary purposes. The general rule of thumb for most financial professionals is to secure any “free money” first. If your employer offers a match on your 401k contributions, you should always contribute enough to capture that full match before turning your attention to other accounts. That match represents an immediate 100% return on your investment, which is mathematically superior to any tax benefit you might find elsewhere.
Once you have secured the full employer match, the comparison between an HSA and a 401k becomes more nuanced. If you are in a high tax bracket and looking to lower your current taxable income, both accounts are effective. However, the HSA has a slight edge because of the triple-tax advantage. While 401k withdrawals are taxed as ordinary income in retirement, HSA withdrawals for medical expenses are completely tax-free. This creates a more favorable long-term tax environment. If you are planning to cover your future healthcare costs with your savings, the HSA is the undisputed winner.
Another factor to consider is the nature of the funds. A 401k is strictly for retirement, and withdrawing before the age of 59 ½ usually carries a 10% penalty plus taxes. An HSA is more flexible; while it is intended for health expenses, you can technically withdraw funds for non-medical reasons after 65 without the penalty (though you will owe income tax). This provides a “safety valve” that the 401k does not offer. Additionally, if you have significant, immediate out-of-pocket medical expenses, the HSA allows you to pay for those with pre-tax dollars today, effectively giving you a discount on your healthcare.
Consider your personal health profile when deciding your priority. If you have recurring, predictable medical costs, maxing out your HSA contributions annually is an excellent way to cover those costs with tax-advantaged money. Conversely, if your goal is primarily to reach a large lump sum for general retirement living, the higher contribution limits of the 401k might be more attractive. For most individuals, the ideal approach is a balanced one: contribute enough to your 401k to get the full match, then prioritize the HSA up to the maximum limit, and finally circle back to the 401k if you have additional income to invest. By utilizing both accounts effectively, you create a robust, tax-efficient foundation for long-term wealth.
Investment Strategies for Long-Term HSA Growth
When you transition from treating your Health Savings Account (HSA) as a mere checking account for medical bills to viewing it as a vehicle for building long-term wealth, your entire financial trajectory changes. Because the funds in an HSA are triple-tax-advantaged—tax-free contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses—they serve as an elite tier of investment accounts. To maximize this growth, you must adopt a strategic approach to asset allocation.
The primary goal for long-term HSA growth is to mirror the strategies used in retirement accounts like a 401(k) or IRA. Since an HSA does not have the same forced distribution schedules as many other retirement accounts, your investment horizon can be significantly longer. For investors who are decades away from retirement, a portfolio heavily weighted toward diversified low-cost index funds or Exchange-Traded Funds (ETFs) is often recommended. By focusing on broad market exposure—such as total stock market index funds—you capture the long-term growth of the global economy while minimizing the risks associated with picking individual stocks.
Another essential strategy involves liquidity management. Many investors fail to invest their HSA because they fear they will need the cash immediately for an unexpected medical emergency. A proven strategy is to keep a small “buffer” in cash within your HSA—perhaps enough to cover your annual out-of-pocket maximum—and invest the remainder of the balance. This ensures that you aren’t forced to sell assets during a market downturn to cover a routine doctor’s visit, allowing your core investments to remain untouched and compounding over the long haul.
Consider the tax-efficiency of your asset placement as well. Because HSAs grow entirely tax-free, they are actually superior to taxable brokerage accounts. Therefore, prioritizing growth-oriented assets within your HSA can be more beneficial than holding bonds or dividend-heavy stocks, which might be better suited for other accounts or strategies depending on your personal tax bracket. By treating the HSA as a long-term equity-focused portfolio, you effectively harness the power of compound interest to build a significant medical retirement nest egg.
Common HSA Investing Mistakes to Avoid
Building wealth through an HSA is a powerful strategy, but it is easy to stumble if you aren’t aware of common pitfalls. The most frequent error is simply leaving your contributions in a zero-interest cash account. Because inflation erodes the purchasing power of idle cash, leaving money uninvested in an HSA is effectively losing money over time. If your HSA provider offers a low-cost brokerage interface, prioritize moving your idle funds into diversified investment vehicles as soon as the account balance reaches a threshold that makes investing practical.
Another significant mistake is failing to account for the impact of fees. Just like with a 401(k), the fees associated with your HSA provider can eat into your long-term returns. Some providers charge monthly maintenance fees or high transaction costs for trading stocks. Before choosing an HSA, research the fee structure thoroughly. If your current employer-sponsored HSA has high fees and limited investment options, check if you are permitted to conduct a partial rollover of your funds into a more cost-effective, standalone HSA provider that offers better investment choices.
Many individuals also treat their HSA as a short-term savings account for routine, predictable healthcare costs. While this is the intended purpose of the account, it defeats the purpose of the triple-tax advantage if you deplete your balance every year. If your financial situation allows, aim to pay for current medical expenses out-of-pocket using taxable savings, while letting the HSA balance stay invested. This keeps your medical “capital” growing in the tax-advantaged account, ensuring that you have significantly more wealth available to cover larger expenses in the future.
Finally, failing to keep adequate documentation is a major oversight. Because the tax-free withdrawal benefit is contingent upon using funds for qualified medical expenses, the burden of proof lies with you in the event of an audit. Losing track of receipts or invoices for medical procedures can make it difficult to justify your withdrawals, potentially leading to unnecessary tax complications. Implementing a digital filing system for all medical receipts is a fundamental step in protecting your wealth and ensuring compliance.
Tracking Medical Expenses for Tax-Free Withdrawals
One of the most misunderstood aspects of HSA investing is the “delayed withdrawal” strategy. The IRS does not require you to reimburse yourself for a medical expense immediately. You can pay for an expense today, save the receipt, and withdraw the funds from your HSA years or even decades later. This allows your investment balance to compound for years while you keep your out-of-pocket cash accessible, effectively acting as an emergency fund that is secretly tax-advantaged.
To master this strategy, you must be disciplined with your record-keeping. Start by creating a dedicated folder—digital or physical—specifically for “HSA Reimbursable Expenses.” Every time you incur an expense, whether it is a co-pay, a dental procedure, or even qualifying over-the-counter medications, ensure you have an itemized receipt. It is not enough to have a bank statement; you need a receipt that clearly indicates the date, the patient, the service provider, the type of service, and the amount paid.
Some investors use spreadsheet software or specialized apps to track these expenses, creating a running total of the amount they are “owed” by their HSA. This gives you a clear snapshot of your liquidity. If you ever face a financial hardship, you know exactly how much you can withdraw from your HSA tax-free without needing to wait for a current medical event. This creates a flexible, secondary layer of financial security that helps protect your overall wealth.
Remember that there is no time limit on when you can reimburse yourself for a medical expense, provided the expense was incurred after your HSA was established. Whether you are 30 or 60, those receipts from a decade ago are still valid for a tax-free withdrawal. Maintaining this historical record is arguably the most effective way to optimize the utility of your HSA throughout your life.
| Account Type | Tax Deduction | Withdrawal Rules | Best For |
|---|---|---|---|
| HSA | Yes (Triple Tax Advantage) | Tax-free for medical; taxable penalty otherwise | Long-term wealth & health costs |
| 401(k) | Yes (Traditional) | Taxable as income in retirement | Employer matching & retirement income |
| Roth IRA | No (After-tax) | Tax-free in retirement | Tax-free growth & flexibility |
How to Use Your HSA for Retirement Income After 65
Once you reach the age of 65, the HSA undergoes a transformation in how it is treated by the IRS. While you can continue to use the funds tax-free for qualified medical expenses—and there are many types of care covered, including Medicare premiums—the HSA also begins to function much like a traditional IRA. If you withdraw funds for non-medical expenses, you will owe ordinary income tax, but the 20% penalty for non-qualified withdrawals is permanently waived.
This makes the HSA an incredibly versatile retirement tool. At 65, your HSA effectively becomes a “super-IRA.” If you have been diligent about investing your HSA funds throughout your career, you may find yourself with a significant portfolio that can supplement your Social Security and other retirement accounts. Even if you have very few medical expenses in retirement, you can withdraw funds for general living expenses and pay only the income tax you would have paid anyway, essentially mimicking a traditional 401(k) withdrawal but with the added potential for massive, tax-free medical coverage if needed.
Furthermore, because you can use HSA funds to pay for Medicare Part B and Part D premiums, as well as Medicare Advantage premiums and long-term care insurance premiums, your HSA becomes a critical buffer against the rising costs of healthcare in your later years. Many retirees find that healthcare is their single largest expense; having an HSA specifically funded and grown over decades can provide peace of mind that a health crisis will not erode their retirement savings.
The key to this strategy is the long-term investment horizon. By resisting the urge to spend your HSA contributions on small, current medical bills, you allow the assets to grow through decades of market cycles. By the time you reach 65, your HSA is no longer just a savings account for an annual check-up—it is a cornerstone of your retirement wealth strategy.
Frequently Asked Questions
Can I invest my HSA money if I don’t have a large balance?
Many providers allow you to begin investing once you have reached a minimum cash balance, often ranging from $1,000 to $2,000. It is best to check with your specific HSA administrator to see their minimum requirements for opening a brokerage or investment account within the HSA.
Is an HSA better than a 401(k) for retirement?
The HSA offers a triple-tax advantage that the 401(k) cannot match, specifically regarding the tax-free status of withdrawals for medical expenses. While a 401(k) is usually better for accessing employer matching funds, an HSA is often considered the most efficient account for long-term wealth building once the employer match has been captured.
What happens to my HSA if I change jobs?
Your HSA belongs to you, not your employer. If you change jobs, the account remains yours to manage. You can leave it where it is, roll it over to a new HSA provider, or simply stop contributing and let the existing balance continue to grow through investments.
Can I use my HSA to pay for my spouse’s medical expenses?
Yes, you can use your HSA funds to pay for qualified medical expenses for yourself, your spouse, and your tax dependents, even if they are not covered by the high-deductible health plan associated with your HSA.
What are considered “qualified” medical expenses?
Qualified medical expenses include a wide range of costs, such as doctor visits, dental care, vision exams, prescription drugs, and many medical devices. The IRS provides a full list of eligible expenses in Publication 502, which is a valuable resource for identifying what your HSA can pay for.
What happens to my HSA if I pass away?
If you designate your spouse as the beneficiary, the HSA becomes their HSA upon your death. If you designate someone other than your spouse, the account ceases to be an HSA and the fair market value becomes taxable income for the beneficiary in the year of your death.
Conclusion
The HSA is far more than a simple medical expense account; it is a sophisticated financial instrument that serves as a cornerstone for long-term wealth. By leveraging the triple-tax advantage—tax-deductible contributions, tax-deferred growth, and tax-free withdrawals—you can build a substantial nest egg designed to cover both future healthcare needs and retirement income. The shift from using the account for day-to-day medical bills to investing in a diversified portfolio is the defining move of a savvy long-term investor.
As you move forward, prioritize consistency. Treat your HSA contributions with the same urgency as your retirement savings. Keep meticulous records of your medical spending to maintain your future flexibility, and resist the temptation to tap into these assets prematurely. By viewing your health savings account through the lens of long-term growth, you are taking a definitive step toward achieving lasting financial security and building genuine wealth.
Start today by reviewing your current HSA provider’s investment options and ensuring your funds are working as hard as you are. If you aren’t currently investing your HSA balance, now is the time to start.
By wealthsimplyput Editorial Team
This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.