⭐ EXPERT-REVIEWED  |  ✅ UPDATED 2026  |  🔒 NO SPONSORED BIAS  |  📚 EVIDENCE-BASED

Author: admin

  • How to Build Wealth From Nothing: A Proven Strategy

    How to Build Wealth From Nothing: A Proven Strategy

    Key Takeaways

    • Wealth creation is primarily a mindset shift that prioritizes long-term outcomes over immediate consumption.
    • Establishing a clear financial baseline is the essential first step to measuring progress toward your goals.
    • A sustainable budget functions as a tool for intentional spending rather than a mechanism for restriction.
    • Aggressive debt elimination acts as a guaranteed return on investment by stopping interest accumulation.
    • An emergency fund provides the psychological and financial buffer necessary to avoid dipping into long-term investments during life’s inevitable setbacks.

    The journey to financial independence often feels like an insurmountable mountain when you are standing at the base with nothing but your ambitions. Many people believe that wealth is the byproduct of luck, inheritance, or high-level insider connections, but the reality is far more accessible. Learning how to build wealth from nothing requires a departure from traditional consumer habits and an embrace of intentional, compounding behaviors. Whether you are currently staring at a negative net worth or simply looking to organize your finances for the first time, the path forward is paved with consistent, repeatable actions. By mastering the fundamentals of personal finance—budgeting, debt management, and proactive saving—you can transform your financial trajectory. This guide serves as your roadmap, designed to strip away the confusion and provide clear, actionable wealth building strategies that work for anyone, regardless of their starting point.

    The Psychology of Wealth Creation

    Before you calculate a single dollar, you must first address the internal machinery that drives your financial decisions. The psychology of wealth creation is the bedrock upon which all successful wealth building strategies are constructed. Most individuals view money through the lens of scarcity or immediate gratification, viewing every paycheck as a resource to be depleted. To change your financial reality, you must pivot toward a mindset of abundance and long-term utility. This shift is not about depriving yourself of the joy of living; it is about recognizing that every dollar spent today is a dollar that cannot work for you in the future.

    One of the most significant psychological barriers to starting from zero is the “all-or-nothing” fallacy. People often feel that if they cannot save a large sum of money, the effort is not worth making. However, building wealth is not an event; it is a series of small, mundane decisions repeated over thousands of days. Wealth creation is essentially the art of delaying gratification. When you choose to invest in your future rather than consume a non-essential luxury, you are actively re-wiring your brain to value your future self as much as your present self. This requires self-awareness. You must identify your “financial triggers”—those moments when you are most likely to spend impulsively—and develop systems to mitigate them.

    Furthermore, understanding the difference between “active” and “passive” financial mindsets is crucial. An active mindset focuses on the immediate paycheck and the next purchase. A passive, or compounding, mindset focuses on assets and cash flow. Experts generally agree that the greatest obstacle to personal finance success is not a lack of income, but the “lifestyle creep” that occurs when income increases. As you begin to earn more, the temptation to expand your lifestyle to match your salary is immense. The wealthy, however, keep their expenses steady while their income rises, directing the surplus toward wealth-generating assets. This is the core psychological shift required to grow wealth fast in relative terms, as it maximizes the delta between your income and your outgoings.

    Developing resilience is also a critical part of this psychological journey. There will be market downturns, unexpected car repairs, and economic shifts that feel personal. If your mindset is tied strictly to market performance or the number in your bank account, you will likely panic and make poor decisions. Instead, anchor your psychology to your habits. If you can focus on the consistency of your savings rate and the wisdom of your spending choices, the macro-level fluctuations become noise. Wealth is ultimately a reflection of your character—your discipline, your foresight, and your ability to value long-term independence over the fleeting comfort of immediate status. By committing to this change in perspective, you move from being a passenger in your financial life to becoming the pilot.

    Assessing Your Current Financial Baseline

    You cannot reach a destination if you do not know your starting point. Assessing your current financial baseline is a sobering but necessary exercise in radical honesty. To begin, you must construct a comprehensive net worth statement. A net worth statement is simply a snapshot of everything you own (assets) minus everything you owe (liabilities). This is the only true scorecard of your financial health. When you start from zero, your net worth might be negative, and that is perfectly okay. Many people are intimidated by this number, but acknowledging it is the precise moment when you stop being a victim of your financial situation and start being a manager of it.

    To calculate your baseline, list your assets in one column: cash in savings and checking accounts, retirement fund balances, equity in real estate, and the estimated resale value of significant personal property. In the second column, list your liabilities: credit card balances, student loans, car loans, and any personal debts. The difference between these two totals is your net worth. This figure provides the objective data required to set realistic goals. Without this number, any advice regarding how to build wealth is purely speculative. You need to see exactly where your capital is currently held—or where it is being drained.

    Once your net worth is calculated, examine your cash flow statement. While your net worth tells you where you are, your cash flow tells you how you got there. Review your last three months of bank statements and credit card bills. Categorize every expense into two groups: “Fixed” and “Variable.” Fixed expenses are the non-negotiables that remain relatively steady, such as rent or mortgage payments, insurance premiums, and minimum debt payments. Variable expenses are where your wealth building potential is hidden—dining out, entertainment, subscriptions, and impulse shopping. This audit often reveals “financial leaks”—recurring charges for services you no longer use or habits that provide little genuine value to your life.

    Comparing your current strategies is a useful exercise to determine which methods might best suit your temperament and income level. See the table below for a quick breakdown of how different approaches to baseline tracking can impact your focus.

    Approach Focus Area Best For
    Manual Spreadsheets Deep granularity and total control Those who want to understand every cent
    Automated Apps Convenience and real-time alerts Those who struggle with manual tracking
    The “Envelope” Method Strict physical cash management Those prone to overspending on credit
    Simplified Net Worth High-level quarterly check-ins Those who prefer big-picture growth

    After reviewing these figures, set your initial targets. These should be S.M.A.R.T. (Specific, Measurable, Achievable, Relevant, and Time-bound). For example, rather than saying “I want to save more,” commit to “I will increase my net worth by $500 this month through a combination of debt reduction and savings.” By documenting your baseline, you create a feedback loop that rewards progress. As you see your liabilities drop and your assets grow, the psychological momentum builds, making the next step significantly easier. Remember, this baseline is not a judgment on your past; it is the foundation upon which you will build your future financial independence.

    Creating a Sustainable Monthly Budget

    The term “budget” often evokes feelings of restriction, anxiety, and punishment. However, a sustainable budget is the most powerful tool in your arsenal. When you are looking to build wealth from nothing, a budget is not a cage; it is a permission slip to spend your money on the things that truly matter while systematically cutting out the waste. A well-designed budget provides the surplus income necessary to fuel your investments. Without one, your money tends to evaporate into small, unmemorable expenses. The goal is to reach a state of financial mindfulness where you are no longer wondering where your money went, but rather telling it exactly where to go.

    There are several frameworks you can employ to create a budget that doesn’t feel like a chore. One popular method is the “50/30/20” rule, which suggests allocating 50% of your net income to needs, 30% to wants, and 20% to savings and debt repayment. While this is a helpful starting point, when you are in the aggressive wealth creation phase, you may find that you need to be more aggressive with your savings rate. If you are serious about fast-tracking your financial independence, you might choose to flip these ratios, aiming for a 50/10/40 split or something similar. The key is sustainability. If your budget is so restrictive that you burn out after two weeks, it will fail.

    When drafting your budget, start with your “non-negotiables.” These are the costs required to maintain your living situation and your health. If these expenses consume too large a portion of your income, your first wealth-building strategy is to lower your cost of living. This might mean downsizing your apartment, refinancing high-interest debt, or canceling unnecessary subscription services. Often, the fastest way to increase your wealth-building capacity is not by increasing your income—which takes time—but by decreasing your fixed overhead, which can be done immediately.

    Once your needs are covered, allocate your “wants” with intention. Wealth building is a marathon, and you need to incorporate rewards to stay consistent. If your budget includes a small, set amount for dining out or hobbies, you are less likely to experience the “binge-spending” cycle that occurs after long periods of extreme austerity. Transparency is also vital. Whether you share finances with a partner or are managing your budget alone, make the process visible. Use digital tools or a simple ledger to track your progress against your plan throughout the month. This constant visibility prevents the “head-in-the-sand” approach that leads to financial disarray.

    Finally, treat your savings and investments as “bills.” When your paycheck hits your account, immediately transfer the designated amount toward your debt or your savings before you spend a single dollar on discretionary items. This is often called “paying yourself first.” By prioritizing this transfer, you ensure that wealth creation happens regardless of how the rest of the month unfolds. A sustainable budget is essentially a set of guardrails. It keeps you on the road toward financial independence even when life attempts to push you toward impulsive, wealth-eroding decisions. Over time, this practice becomes a habit, and you will find that managing your money becomes less of a mental burden and more of a source of confidence.

    Prioritizing High-Interest Debt Elimination

    High-interest debt is the silent killer of wealth. It is a mathematical anchor that prevents you from gaining any traction, regardless of how much money you earn. When you pay double-digit interest rates on credit cards or high-interest personal loans, you are effectively working to pay someone else’s wealth instead of building your own. In the hierarchy of personal finance tips, eliminating this type of debt should almost always take precedence over investing. Why? Because paying off a debt with an interest rate of 20% is mathematically equivalent to receiving a guaranteed, tax-free 20% return on your money. No investment in the public markets can reliably offer that kind of return, making debt destruction your highest-impact financial move.

    To tackle debt effectively, you must first organize your liabilities by interest rate rather than by balance. This is known as the “Avalanche Method.” By focusing your surplus income on the debt with the highest interest rate while paying minimums on others, you save the most money over time and shorten the total time you spend in debt. Alternatively, some individuals find more motivation in the “Snowball Method,” where you pay off the smallest balance first to build momentum. While mathematically less efficient, the psychological win of clearing a debt entirely can provide the motivation needed to stay the course. Choose the method that best aligns with your psychology, but stay committed to the goal of debt elimination.

    While you are aggressively paying down debt, you must also stop the bleeding. This means freezing your credit cards and, if necessary, switching to a debit or cash-only system. It is impossible to dig yourself out of a hole while you are still digging. You must commit to living on less than you earn. This is the hardest part for many, as it requires a temporary reduction in lifestyle comfort. You might have to say “no” to vacations, expensive dinners, or upgraded technology for a season. Remember, this is not a permanent state; it is a tactical retreat to secure a stronger financial future.

    Communication can also be a powerful tool for debt elimination. If your interest rates are exceptionally high, reach out to your creditors. Many lenders are willing to lower interest rates if you have a history of on-time payments or if you can demonstrate genuine financial hardship. Additionally, consider looking into balance transfer options with lower introductory interest rates, provided you have the discipline to pay off the balance before the promotional period ends. However, be cautious; balance transfers are merely a tool for organization and interest savings, not a solution for overspending. If the underlying habit that led to the debt is not addressed, you will likely find yourself in the same position later.

    Once your high-interest debt is cleared, the psychological shift is palpable. You are suddenly no longer paying for past consumption, allowing you to redirect those monthly payments toward assets that grow in value. This is the moment your wealth-building journey truly shifts from defensive to offensive. You are no longer fighting the gravity of compound interest; you are now using it as your greatest ally. Keep the records of your debt-free progress—perhaps a simple chart on your wall—to remind yourself of the freedom you have earned through discipline. You are now ready to build security.

    Building an Emergency Fund for Security

    Even if you have mastered your budget and eliminated your high-interest debt, life remains unpredictable. This is why building an emergency fund is a non-negotiable step in any sound wealth creation plan. An emergency fund is a bucket of liquid cash—typically kept in a high-yield savings account—that is reserved strictly for genuine, unforeseen events. We are talking about job loss, major medical expenses, or essential home and vehicle repairs. It is not for “good deals,” birthday presents, or last-minute travel. Without this safety net, one minor catastrophe can force you back into debt, undoing months or even years of hard-won progress.

    How much do you need? While the conventional wisdom often suggests three to six months of living expenses, your specific number will depend on your risk tolerance, your job stability, and your family situation. If you are a freelancer with irregular income, you may want to aim for a larger buffer. If you have a stable job with a low cost of living, you might start with a smaller, more manageable goal. Start by aiming for a “starter emergency fund” of a fixed amount—perhaps $1,000 or one month of expenses—to handle the most likely small disasters. Once that is established, you can gradually grow the fund to your ideal, fully-funded target.

    Where you keep this money matters as much as the amount itself. Your emergency fund must be liquid and easily accessible, but it should not be in your primary checking account where it is easily “spent” by accident. A separate online high-yield savings account is ideal. These accounts typically offer a better interest rate than a traditional brick-and-mortar bank, which helps your emergency fund lose less value to inflation, while the slight friction of having to transfer the money to your main account acts as a mental deterrent against using it for non-emergencies.

    The true value of an emergency fund is not just the money; it is the peace of mind. When you know you have a buffer, you make better decisions. You are less likely to panic-sell investments when the stock market dips, and you are less likely to take a job you hate just because you need the immediate cash. This psychological security allows you to focus on long-term wealth building strategies with confidence. It allows you to take calculated risks in your career or business, knowing that you have a floor beneath your feet.

    Treat the funding of this account as a high-priority financial goal. While it might seem counterintuitive to keep cash in a low-earning account when you are eager to invest, consider the emergency fund to be the “insurance premium” on your future wealth. By prioritizing security, you ensure that you can stay the course, no matter what happens in your personal life or the broader economy. It is the final piece of the structural foundation you need to build long-term wealth from zero. Once this fund is established, you are no longer just surviving—you are ready to start thriving.

    Developing Multiple Income Streams

    The foundation of wealth creation is rarely a single source of income. While a primary salary is the starting point for most people, relying on it entirely places a cap on your potential growth. To accelerate your journey toward financial independence, you must transition from a “linear income” mindset to a “diversified income” strategy. When you build multiple streams, you create a buffer against economic downturns and job insecurity, while simultaneously increasing the velocity at which you can funnel capital into wealth-building assets.

    Diversification doesn’t mean spreading yourself thin. Instead, it means layering income sources that benefit from your existing skills or assets. Start by identifying your “secondary capacity.” This might involve freelancing, consulting, or creating digital products that leverage your professional expertise. Because these ventures often require high effort upfront but lower maintenance later, they represent the most accessible way to increase your monthly savings rate without needing to double your working hours.

    Consider the concept of “leveraged income.” This occurs when you decouple your time from your earnings. Examples include intellectual property, such as writing an e-book, developing a software tool, or creating online courses. Unlike a standard hourly wage, these streams can earn revenue while you sleep, effectively multiplying your productivity. By reinvesting the profits from these secondary streams directly into your investment portfolio, you create a flywheel effect: your work buys assets, and those assets begin to generate their own returns, further subsidizing your lifestyle.

    Furthermore, look for ways to monetize your existing assets. Many individuals overlook the potential for passive income through house hacking, renting out equipment, or earning dividends from fractional ownership in businesses. The goal is to turn “dead assets” into productive cash flow machines. When your passive income eventually covers your base expenses, you have reached the first major milestone of financial independence. From there, every additional dollar earned becomes a vehicle for pure wealth accumulation.

    The Power of Compound Interest and Investing

    If income streams are the fuel, compound interest is the engine. Albert Einstein is often credited with calling compound interest the “eighth wonder of the world,” and in the context of wealth building, this hyperbole is grounded in mathematical reality. Compound interest allows your money to grow exponentially because you earn returns not just on your initial investment, but on the accumulated interest or dividends from previous periods. Over long time horizons, the curve of wealth growth shifts from a gentle slope to a vertical climb.

    To harness this power, you must adopt a “time in the market” philosophy. Timing the market is a futile game, even for professionals. Instead, consistency—investing a set amount of capital at regular intervals regardless of market fluctuations—is the proven path to building significant net worth. By staying invested through bull and bear markets, you benefit from the long-term upward trajectory of the global economy. This is particularly effective when utilizing tax-advantaged accounts, which allow your earnings to grow without the immediate drag of annual taxation.

    Understanding asset allocation is the next step in optimizing these returns. Your portfolio should be balanced based on your risk tolerance and your “runway” until you reach your goal. Broad-market index funds and exchange-traded funds (ETFs) are often the preferred vehicles for retail investors because they offer immediate diversification and low fee structures. By owning a slice of the entire market, you eliminate the risk of picking a single losing stock and instead capture the collective growth of the world’s most innovative companies.

    Investment Vehicle Typical Growth Potential Liquidity Best For
    High-Yield Savings Low Very High Emergency funds and short-term goals
    Index Funds / ETFs Moderate to High High Long-term retirement and wealth building
    Real Estate Moderate to High Low Tax advantages and cash flow
    Individual Stocks Variable High Aggressive growth for experienced investors

    Automating Your Financial Habits

    Willpower is a finite resource. If you rely on the monthly discipline of manually transferring money to a savings account or researching investment picks, you will eventually fail. The most successful wealth builders rely on “financial automation” to remove human error and emotional decision-making from the equation. Automation turns the complex task of wealth creation into a background process that runs flawlessly without your intervention.

    The strategy is simple: pay yourself first. Configure your payroll or banking interface so that a predetermined percentage of your income is automatically deposited into a high-yield savings account or a brokerage account the moment your paycheck arrives. When you treat your savings and investments like non-negotiable bills, you adjust your lifestyle to live on what remains. This forces “lifestyle creep” to stagnate even as your income rises, allowing you to maximize your capital allocation efficiency.

    Additionally, automate your debt repayments. High-interest debt is an anchor on your net worth; by automating payments to exceed the minimum amount due, you ensure that you are aggressively chipping away at the principal. This systematic approach reduces the total interest paid over the life of the loan. Furthermore, set up automatic recurring contributions for your long-term investment accounts. By dollar-cost averaging—purchasing more shares when prices are low and fewer when they are high—you effectively smooth out the volatility of the market, reducing the stress associated with market swings.

    Finally, perform a “digital audit” of your financial life at least once per quarter. While the daily execution should be automated, the oversight must remain human. Check in on your subscription services, audit your recurring bills to ensure you aren’t paying for unused utilities, and rebalance your portfolio if your asset allocation has drifted. Automation gets you to the goal, but your strategic oversight ensures you stay on the most efficient path.

    Scaling Your Wealth Over the Long Term

    As your wealth grows, the strategies you used to get from zero to your first milestone may need to evolve. Scaling wealth is about shifting your focus from “earning” to “preserving and compounding.” This involves moving into more sophisticated vehicles, such as tax-efficient investment structures or private assets that offer different risk-return profiles compared to public markets. At this stage, your primary job shifts from working for money to managing the risk of your existing capital.

    Tax management becomes increasingly important as your assets grow. In the early stages, taxes are a minor nuisance, but as your portfolio expands, they can become a significant drag on growth. Utilize tax-loss harvesting to offset capital gains, and prioritize tax-advantaged accounts. Work toward a structure where your money is held in a variety of buckets—tax-deferred, tax-free, and taxable—to give you maximum flexibility when you decide to transition from the accumulation phase to the distribution phase.

    Scaling also involves protecting your downside. As your net worth increases, your potential exposure to liability also grows. This is the stage where you should consider umbrella insurance, estate planning, and a more robust approach to asset protection. Building wealth is a marathon, not a sprint, and protecting the capital you have already amassed is just as vital as seeking out new opportunities for gain. The ultimate goal is to reach a level of “financial velocity” where your portfolio generates sufficient returns to exceed both inflation and your desired standard of living.

    Frequently Asked Questions

    How much money do I need to start building wealth?

    You can start with as little as five or ten dollars. Many modern brokerage platforms allow for fractional share investing, meaning you don’t need a large lump sum to enter the market. The most critical factor is the habit of consistency rather than the starting balance.

    Is it possible to build wealth if I have significant debt?

    Yes, but you must change your approach. Generally, experts recommend prioritizing the repayment of high-interest debt, such as credit cards, before aggressively pursuing long-term market investments. By eliminating high-interest liabilities, you effectively achieve a guaranteed “return” on your money equal to the interest rate you are no longer paying.

    How long does it typically take to become wealthy?

    Wealth building is a long-term endeavor that typically takes years or decades, depending on your income, savings rate, and market conditions. While “get rich quick” schemes are often predatory, a disciplined approach of saving and investing regularly can lead to significant financial independence over a standard career timeframe.

    What is the most common mistake people make when starting?

    The most common mistake is attempting to time the market or trying to pick “winning” stocks instead of investing in broad, diversified funds. Additionally, many people fall into the trap of increasing their spending immediately after getting a raise, which prevents them from increasing their savings rate.

    Do I need a financial advisor to build wealth?

    Not necessarily. For many individuals, low-cost index fund investing and automating finances is sufficient to build wealth effectively. However, as your financial situation becomes more complex—such as dealing with significant tax implications, business ownership, or complicated estate planning—a professional can provide valuable guidance.

    What is the role of inflation in wealth creation?

    Inflation is a constant force that reduces the purchasing power of cash over time. If your money is sitting in a traditional checking account with little to no interest, inflation is silently eroding your wealth. Investing is the primary method of growing your capital at a rate that outpaces inflation, preserving your future buying power.

    Conclusion

    Building wealth from nothing is not a matter of luck, secret knowledge, or having a high starting salary. It is a systematic process built on the pillars of aggressive saving, consistent investing, and the patience to let time do the heavy lifting. By moving away from short-term thinking and embracing the power of compound interest, you position yourself to move beyond the limitations of your current income and into a life of genuine financial security.

    The hardest step is the first one. Whether it is opening a brokerage account, cutting your first non-essential expense, or automating your savings, taking action today is the only way to shift your financial trajectory. Your future self is waiting for you to make the commitment to long-term growth. Start today, stay the course, and watch as your small, consistent actions build a legacy of freedom.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • How to Build Wealth: 7 Proven Strategies for Beginners

    Key Takeaways

    • Building wealth is a marathon that requires consistent, long-term habits rather than get-rich-quick schemes.
    • Mastering your cash flow through strategic budgeting is the foundational step in long-term wealth creation.
    • An emergency fund serves as your financial safety net, preventing high-interest debt when life’s unexpected costs arise.
    • Compound interest acts as a multiplier for your wealth; the earlier you start, the more significant its impact becomes.
    • Effective debt management is essential to stop interest payments from cannibalizing your potential investment returns.

    Building wealth is not merely about how much money you earn, but how much you keep and how effectively you put those resources to work. Many individuals struggle to navigate the overwhelming amount of financial advice online, often falling into traps that prioritize short-term gains over sustainable growth. Whether you are starting your journey with nothing or looking to organize your existing savings, understanding the core principles of personal finance basics is the most reliable way to achieve lasting prosperity. This guide provides a structured roadmap to help you navigate your journey toward financial independence, focusing on proven, logical strategies that have stood the test of time.

    1. Defining Your Personal Wealth Goals

    Before you can successfully grow wealth, you must first define what that wealth looks like for you. Wealth is subjective, and its pursuit should be aligned with your personal values and long-term aspirations. For some, wealth means the ability to retire comfortably at a specific age; for others, it represents the freedom to change careers, start a business, or support a family without financial stress. Without a clearly defined objective, your efforts may lack direction, making it difficult to maintain the discipline required for long-term wealth creation.

    The first step in this process is to establish S.M.A.R.T. goals—Specific, Measurable, Achievable, Relevant, and Time-bound. Rather than simply stating you want to “be rich,” break your ambitions down into actionable milestones. Perhaps your goal is to save a specific amount for a down payment within three years or to reach a certain “number” in your investment portfolio that would allow you to cover your basic living expenses indefinitely. When you have a concrete goal, the trade-offs you make today—such as choosing to cook at home instead of dining out—no longer feel like a sacrifice. Instead, they become deliberate choices to move closer to your objective.

    Consider the difference between short-term, medium-term, and long-term goals. Wealth building strategies should be layered. Short-term goals might include paying off high-interest credit card debt or fully funding an emergency fund. Medium-term goals could involve saving for a home or funding a child’s education. Long-term goals are focused on retirement and the creation of generational stability. By segmenting your focus, you can better allocate your income. For instance, you might use a portion of your monthly savings for short-term liquidity while directing a consistent percentage toward long-term equity investments.

    It is also essential to periodically re-evaluate these goals as your life circumstances evolve. A salary increase, a new family member, or a change in your health status can significantly alter your financial needs. Authoritative personal finance experts often suggest conducting a quarterly “wealth check-up.” During this time, look at your progress, celebrate the small victories, and adjust your trajectory if your life goals have shifted. Remember that wealth is not just a destination; it is a lifestyle that requires intentionality. When your daily habits reflect your ultimate goals, you transition from someone who is merely “getting by” to someone who is actively engineering their financial future.

    2. Mastering the Basics of Budgeting and Cash Flow

    Budgeting is often misunderstood as a restrictive tool designed to prevent enjoyment. In reality, effective budgeting is a strategy to ensure your money is working for you, not against you. If you want to understand how to build wealth, you must treat your personal finances like a business. A business tracks its revenue, monitors its expenses, and reinvests the difference into growth-oriented assets. You should do the same by managing your personal cash flow with equal precision.

    The foundation of any wealth building plan is the ability to maintain a positive spread between what you earn and what you spend. If your expenses consistently consume your entire income, you are effectively tethered to your paycheck, leaving no room for investment or growth. To break this cycle, start by auditing your current spending. Categorize your expenses into “Needs” (housing, utilities, groceries) and “Wants” (entertainment, dining out, luxury subscriptions). Experts generally suggest the 50/30/20 rule as a starting framework: allocate 50 percent of your income to needs, 30 percent to wants, and 20 percent to savings and debt repayment.

    However, rigid formulas may not work for everyone. The most effective approach is one you can stick to consistently. There are various methodologies for managing cash flow, ranging from manual tracking to automated systems. The goal is to reach a state where you are “paying yourself first.” This means treating your savings and investments as a non-negotiable bill that must be paid as soon as your paycheck arrives. By automating these transfers to savings or investment accounts, you ensure that wealth creation happens automatically before you have the chance to spend those funds on discretionary items.

    Monitoring your cash flow also allows you to identify “leaks”—small, recurring expenses that add up significantly over a year. Streaming subscriptions, underutilized gym memberships, or excessive transaction fees can quietly erode your financial potential. By tracking your spending for at least one month, you gain clarity on where your money is actually going. This awareness is powerful; it empowers you to redirect those funds toward vehicles that actually grow wealth, such as retirement accounts or low-cost index funds. Remember that wealth is not what you spend, but what you keep. By mastering your cash flow, you create the fuel necessary for all other wealth-building strategies to succeed.

    Methodology Description Best For
    Zero-Based Budgeting Assigning every single dollar a specific job until you reach zero. Those who want maximum control and have variable income.
    50/30/20 Rule Allocating income by percentage categories (Needs/Wants/Savings). Beginners looking for a simple, sustainable system.
    Pay-Yourself-First Automating savings transfers before any discretionary spending occurs. Busy individuals who value automation and simplicity.

    3. The Importance of Building an Emergency Fund

    One of the most frequent roadblocks to long-term wealth creation is the “emergency cycle.” This occurs when an unexpected expense—such as a car repair, a sudden medical bill, or a temporary loss of income—forces an individual to rely on credit cards or high-interest loans. Once you enter the cycle of high-interest debt, your focus shifts from growing wealth to merely surviving the interest payments, which can set your progress back by years. An emergency fund is your primary shield against this scenario.

    An emergency fund is a dedicated pool of cash, typically kept in a high-yield savings account, that is intended solely for true financial surprises. The rule of thumb shared by many financial advisors is to save between three to six months of essential living expenses. While this number might seem daunting when you are just beginning your journey, the objective is not to build it overnight. Even starting with a goal of one month’s expenses provides a vital buffer. By consistently setting aside a small portion of your income, you will eventually reach a point where you can handle life’s inevitable challenges without compromising your long-term investment strategy.

    What defines an “emergency” is just as important as the fund itself. An emergency fund is for non-discretionary, unplanned, and necessary expenses. It is not meant for planned purchases like holiday gifts, new appliances, or vacations. Using your emergency fund for anything other than a genuine crisis defeats the purpose of having it. If you find yourself frequently tapping into these savings for non-emergencies, it may be a sign that you need to re-evaluate your budget to better account for irregular or annual expenses.

    The psychological benefit of an emergency fund cannot be overstated. Knowing that you have a financial safety net provides a sense of security that allows you to take calculated risks in your career and investment life. Without this cushion, you might be forced to make desperate decisions, such as liquidating investment assets during a market downturn just to pay the rent. By keeping your emergency fund in a separate, liquid account, you ensure that your long-term wealth building strategies—like stocks or real estate—remain untouched, allowing them the time and stability they need to compound effectively. In essence, the emergency fund is the bedrock upon which the rest of your financial structure is built.

    4. Understanding the Power of Compound Interest

    If you want to master how to grow wealth, you must understand compound interest. Often referred to by famous investors as the “eighth wonder of the world,” compound interest is the process where the interest you earn on an investment also begins to earn interest itself. This creates a snowball effect that turns small, consistent contributions into significant sums over long periods. The most critical factor in this equation is not necessarily how much money you invest, but how much time you give your money to compound.

    Let’s visualize this: if you invest a small amount of money and leave it to grow, the returns generated in the first few years may seem negligible. However, as the balance grows, the interest earned on that interest becomes increasingly substantial. This is why financial independence tips almost always emphasize starting as early as possible. If you start investing in your 20s, you have the benefit of decades of compounding, which allows you to reach your goals with much smaller monthly contributions than someone who waits until their 40s to begin.

    Compound interest works best with a consistent, long-term approach. Market volatility is inevitable, and there will be years where your portfolio values fluctuate. However, when you maintain a long-term perspective and avoid the temptation to time the market, you allow compounding to operate in your favor. This is why index fund investing is frequently recommended for beginners; it provides broad market exposure, which historically captures long-term growth while minimizing the risks associated with picking individual stocks. By reinvesting your dividends—the payouts companies provide to their shareholders—you accelerate the compounding process even further.

    Many beginners feel they need a large sum of money to “start” investing. This is a common misconception that keeps many people on the sidelines. In reality, modern financial tools allow you to start with very small increments. Whether you have fifty dollars or five hundred to invest each month, the consistency of your habits matters more than the initial amount. When you prioritize long-term wealth creation through compounding, you shift from being a laborer who works for money to an investor whose money works for them. Once this shift occurs, the math of compounding begins to do the heavy lifting, gradually moving you toward a future of financial independence.

    5. Effective Debt Management Techniques

    Not all debt is created equal, but all debt creates a drag on your financial progress. To effectively build wealth, you must have a clear strategy for managing and eliminating high-interest liabilities. When you owe money on credit cards or high-interest personal loans, you are paying a “tax” on your future self. The interest rates on these types of debts are often significantly higher than any reasonable return you could expect from the stock market, which is why debt repayment is often the highest-yield “investment” you can make in your early financial stages.

    The first step in debt management is to inventory all your obligations. Write down the total balance, the interest rate, and the minimum monthly payment for each debt. This creates a clear picture of your financial landscape. Once you have this list, you can choose a strategy for repayment. Two of the most common and effective methods are the “Debt Snowball” and the “Debt Avalanche.”

    The Debt Snowball method focuses on paying off the smallest balance first, regardless of the interest rate. Once that debt is cleared, you take the amount you were paying toward it and roll it into the next smallest debt. This method is highly effective for building behavioral momentum; seeing those small debts disappear quickly provides a psychological win that encourages you to keep going. On the other hand, the Debt Avalanche method prioritizes the debt with the highest interest rate. By paying off the most “expensive” debt first, you mathematically minimize the amount of total interest paid over time, which can save you significant money in the long run.

    In addition to these repayment strategies, consider whether debt consolidation or refinancing is an option. If you have several high-interest debts, transferring them to a lower-interest consolidation loan or a balance transfer card might lower your monthly burden. However, this should only be done if you are committed to not accumulating new debt in the process. Consolidating debt without addressing the underlying spending habits that caused it often leads to a cycle of repeated borrowing.

    Ultimately, the key to successful debt management is to stop the bleeding. Stop using credit cards for purchases you cannot afford to pay off at the end of the month. Use your emergency fund to cover sudden expenses so that you are never forced to lean on credit again. By systematically clearing your debt, you are not just cleaning up your ledger; you are freeing up cash flow that can finally be redirected toward long-term wealth creation. Remember that for every dollar of interest you stop paying to a lender, you keep a dollar that can be put toward your own future security.

    How to Choose the Right Investment Accounts

    Choosing the right investment account is the foundation of long-term wealth creation. Many beginners feel overwhelmed by the alphabet soup of account types, but the decision process should be driven by your specific financial goals, your current employment status, and your tax situation. Before you transfer a single dollar into the market, you must understand where that money is living.

    The first tier of account selection usually revolves around tax-advantaged retirement vehicles. In the United States, for instance, this includes 401(k) plans and Individual Retirement Accounts (IRAs). A 401(k) is typically offered through your employer. If your company provides a matching contribution, experts generally agree this is the single best investment you can make, as it represents an immediate return on your capital. When choosing between a Traditional and a Roth version of these accounts, consider your tax strategy: Traditional accounts offer a tax deduction today, while Roth accounts allow for tax-free growth and tax-free withdrawals in retirement.

    Beyond retirement-specific vehicles, taxable brokerage accounts serve as the primary tool for general wealth building. These accounts do not offer the same tax breaks as retirement accounts, but they provide the liquidity that many investors need for mid-term goals, such as buying a home or funding a business venture. Because you can access these funds at any time without the penalties associated with early retirement withdrawals, they are an essential component of a balanced financial plan.

    When selecting a brokerage or investment platform, consider the fee structure, the variety of assets available, and the user interface. High management fees can erode your long-term wealth significantly over several decades. Modern investors typically gravitate toward platforms that offer commission-free trading and low-cost index funds or Exchange Traded Funds (ETFs).

    Account Type Tax Treatment Liquidity Best for
    Employer 401(k) Tax-deferred/Tax-free Low (Penalty for early access) Securing employer match
    Roth IRA Tax-free growth Moderate (Contributions accessible) Tax-free retirement income
    Taxable Brokerage Capital gains taxed High Mid-term wealth goals
    Health Savings Account (HSA) Triple tax advantage Moderate Medical expenses and long-term investing

    Diversifying Your Assets for Long-Term Growth

    Diversification is often called the only “free lunch” in investing. It is the strategy of spreading your capital across various asset classes to minimize risk. The goal is not necessarily to maximize returns in any single year, but to ensure that your portfolio can survive market volatility while steadily growing over the long term. A well-diversified portfolio acts as a shock absorber; when one sector of the economy struggles, another may flourish, providing balance.

    For beginners, asset allocation is the primary method of diversification. This involves deciding what percentage of your portfolio should be in stocks, bonds, cash, and perhaps alternative assets like real estate or commodities. Stocks typically offer the potential for higher growth but come with higher volatility. Bonds are generally considered safer and provide regular interest payments, helping to dampen the swings of the stock market. As you grow wealth, your specific allocation should align with your risk tolerance and the timeline of your financial goals.

    Investment in broad-market index funds is one of the most effective ways to achieve instant diversification. Instead of trying to pick individual winners—a strategy that experts often warn is difficult to sustain—you can buy a single fund that holds hundreds or thousands of companies. By owning a “slice of the market,” you reduce the risk of any single company’s failure destroying your wealth. Geographic diversification is another layer to consider; holding international stocks ensures that your success is not tied solely to the economic performance of one nation.

    It is important to remember that diversification requires periodic rebalancing. If your target allocation is 70% stocks and 30% bonds, a successful year in the stock market might push your stock holdings to 80%. Rebalancing involves selling some of your winners and buying more of your underperforming assets to return your portfolio to its target percentages. This process forces you to follow a disciplined “buy low, sell high” approach without relying on emotional decision-making.

    Automating Your Financial Habits for Consistency

    The greatest barrier to wealth building is often human psychology. We are prone to spending money as soon as we see it, and we are easily swayed by market panic or excitement. Automation is the antidote to these biological impulses. By setting your financial systems on “autopilot,” you remove the need for willpower, making wealth creation a default behavior rather than a monthly struggle.

    Start by automating your savings. If your paycheck is deposited into your bank account, set up a recurring transfer that moves a predetermined percentage of that income into a separate savings or investment account the same day you get paid. This is often referred to as “paying yourself first.” If you wait until the end of the month to save what is left over, you will often find that nothing is left. When you automate the process, you adjust your spending habits to live on what remains, rather than trying to save from what is left after spending.

    Similarly, automate your debt payments and bill obligations. Missing a payment not only incurs unnecessary late fees and interest but also damages your credit score, which can be an expensive mistake when you eventually need to borrow for a mortgage or other major purchase. Modern banking apps make it simple to schedule recurring payments for fixed expenses, ensuring that you never miss a deadline.

    For long-term investing, dollar-cost averaging is the ultimate automated strategy. By investing a fixed amount of money at regular intervals—for example, every two weeks—you buy more shares when prices are low and fewer shares when prices are high. Over time, this averages out the cost of your investments and prevents you from making the disastrous mistake of trying to “time the market.” Whether the market is trending up or down, your automated contribution ensures you remain invested in your future.

    Common Wealth Building Mistakes to Avoid

    Wealth building is as much about avoiding errors as it is about making smart moves. Even with a high income, many individuals struggle to accumulate significant net worth because they fall into common behavioral traps. Recognizing these mistakes early can save you years of lost progress.

    One of the most detrimental mistakes is “lifestyle creep.” As your income increases, it is natural to want to upgrade your housing, vehicle, and lifestyle. However, if your spending increases at the same rate as your earnings, your ability to build wealth remains stagnant. True wealth is built by maintaining a consistent standard of living while allowing your investments to scale, creating a widening gap between your income and your expenses.

    Another frequent error is carrying high-interest consumer debt. Credit card debt, in particular, often carries interest rates that are significantly higher than what you might earn in the stock market. Trying to invest while holding debt at 20% interest is like trying to fill a bucket that has a massive hole in the bottom. Experts generally recommend prioritizing the elimination of high-interest debt before allocating significant capital to non-retirement investments.

    Many beginners also fall victim to the “get rich quick” mentality. Whether it is chasing speculative crypto-assets, listening to “hot tips” from social media, or engaging in day trading, these activities are often forms of gambling rather than wealth building. Long-term wealth is almost always the result of boring, consistent, and disciplined habits sustained over decades. If an investment strategy promises high returns with little risk, it is almost certainly a trap that will jeopardize your financial future.

    Finally, failing to establish an emergency fund is a critical oversight. Life is unpredictable—medical emergencies, job losses, and unexpected repairs occur. If you do not have a cash cushion in a high-yield savings account, you will be forced to raid your investment accounts or take on high-interest debt when an emergency hits. This can derail years of progress. A solid emergency fund allows you to navigate these life events without dismantling the wealth-building infrastructure you have worked so hard to establish.

    Frequently Asked Questions

    What is the minimum amount of money needed to start building wealth?

    You can start building wealth with as little as a few dollars. Modern financial technology allows for fractional share investing and low-minimum account openings. The specific dollar amount is far less important than the habit of consistency. Whether you start with $50 or $5,000, the compound interest generated over time is what ultimately builds significant wealth.

    Is it better to pay off debt or invest money?

    Generally, you should prioritize paying off high-interest debt (such as credit card debt) before focusing heavily on wealth building, because the interest you pay on debt often exceeds the average expected return from the stock market. However, if your debt has a low interest rate, such as a mortgage or certain student loans, many experts suggest a balanced approach of paying the debt as scheduled while investing in long-term assets.

    How much of my income should I save for wealth building?

    While personal circumstances vary, a common benchmark is to aim for a 20% savings rate. This means 20% of your take-home pay is allocated to debt repayment, savings, and investments. If that feels unattainable, start with a smaller percentage and gradually increase it as you optimize your budget and increase your earning capacity.

    What is the difference between saving and investing?

    Saving is the act of setting money aside for short-term needs, typically in low-risk accounts like high-yield savings or money market funds. Its primary goal is safety and liquidity. Investing is the act of purchasing assets—like stocks, bonds, or real estate—with the expectation of growing that wealth over a longer time horizon. Investing carries more risk than saving but provides the potential for higher returns to combat inflation.

    How do I stay motivated when wealth building takes so long?

    Focus on incremental progress rather than the final number. Set milestones, such as reaching your first $1,000, then your first $10,000. Automating your finances also helps keep you motivated, as you don’t have to experience the “pain” of manually transferring money. Remind yourself that wealth building is a marathon, and the most significant gains usually happen in the later stages of the compounding process.

    Should I hire a financial advisor to help me build wealth?

    For many beginners, a financial advisor is not strictly necessary, as low-cost index funds and robo-advisors offer effective strategies for most people. However, if you have a complex tax situation, significant assets, or feel that you lack the temperament to stick to a plan without guidance, a fee-only, fiduciary financial advisor can provide valuable peace of mind and personalized strategy.

    Conclusion

    Building wealth is not a secret reserved for the elite; it is a systematic process available to anyone willing to pair discipline with time. By focusing on the basics—managing your cash flow, utilizing tax-advantaged accounts, diversifying your investments, and automating your habits—you are positioning yourself for long-term financial independence. While the journey requires patience and the ability to ignore the noise of the market, the reward is the ultimate freedom to control your own time and future.

    The best time to start was yesterday, but the second-best time is right now. Take the first step today by auditing your current expenses or opening your first investment account. Your future self will thank you for the decisions you make today.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Tax-Loss vs Tax-Gain Harvesting: Which Wins in 2026?

    Tax-Loss vs Tax-Gain Harvesting: Which Wins in 2026?

    Key Takeaways

    • Tax-loss harvesting allows investors to sell underperforming assets to offset capital gains, reducing their current tax liability.
    • Tax-gain harvesting is a proactive strategy to reset the cost basis of investments, which can be highly effective in lower-income years.
    • In high-interest rate environments, the opportunity cost of capital increases, making tax-efficient investing even more critical for long-term wealth.
    • Strategic portfolio optimization requires a delicate balance between tax management and maintaining your long-term asset allocation.
    • Always be wary of the wash-sale rule, which prohibits claiming a loss if you purchase a “substantially identical” security within 30 days.

    As we navigate the complexities of 2026, the intersection of market volatility and macroeconomic shifts has placed a renewed focus on tax-efficient investing. For the modern investor, wealth is not merely about the returns a portfolio generates, but about how much of that gain remains in your pocket after accounting for the capital gains tax. Whether you are looking to mitigate your tax bill during a market downturn or strategically harvest gains to reset your basis, mastering the art of tax-loss harvesting and tax-gain harvesting is essential for anyone serious about wealth accumulation. This guide serves to clarify these strategies and help you determine which approach aligns with your broader financial trajectory in today’s high-interest rate climate.

    Understanding the Basics of Tax-Loss Harvesting

    Tax-loss harvesting is a fundamental pillar of modern portfolio optimization. At its simplest, it involves selling an investment that has lost value—a security currently trading below your original purchase price—to realize a loss for tax purposes. By doing so, you can use that loss to offset capital gains realized elsewhere in your portfolio. If your total losses exceed your total gains, you may often apply up to a specific amount of the excess loss to reduce your ordinary income, providing a multi-layered benefit to your annual tax filing.

    The true value of this strategy lies in its ability to generate “tax alpha.” In a high-interest rate environment, where traditional fixed-income investments might be delivering higher yields, the pressure on your equity portfolio to remain efficient becomes even more pronounced. When you execute a tax-loss harvesting trade, you are not simply giving up on an asset; you are maintaining your desired market exposure while simultaneously capturing a tax benefit. The classic approach involves selling the losing asset and immediately purchasing a “proxy” investment—a similar but not identical asset—to ensure you remain invested in the market while waiting for your original position to potentially recover.

    For those pursuing long-term wealth, the tax savings generated from these losses can be reinvested. This creates a compounding effect, where the money that would have otherwise been sent to the tax authorities instead stays within your brokerage account, contributing to your total portfolio growth over time. However, this strategy is not a “set it and forget it” tool. It requires consistent monitoring of your portfolio’s performance. As market conditions shift, the frequency with which you review your unrealized losses should increase. It is also important to consider the transaction costs and the potential impact of long-term vs. short-term capital gains tax rates. Expert practitioners of wealth management typically emphasize that tax-loss harvesting should never override your core investment thesis. You are harvesting losses to be more efficient, not to change your risk profile or deviate from your long-term wealth objectives. By staying disciplined and objective, investors can turn periods of market malaise into opportunities for significant tax relief.

    When Tax-Gain Harvesting Makes Strategic Sense

    While tax-loss harvesting focuses on the downside, tax-gain harvesting is a proactive maneuver designed to capitalize on lower tax brackets or periods of income fluctuation. In tax-gain harvesting, you intentionally sell an appreciated asset, realize the gain, and then immediately repurchase it. By doing so, you “reset” your cost basis to the current, higher market price. This might seem counterintuitive—why pay taxes on a gain before you have to?—but the math can be incredibly advantageous under the right circumstances.

    The primary scenario where this approach shines is during years when your taxable income is significantly lower than usual. If you find yourself in a lower tax bracket for a specific year, you might trigger capital gains at a zero or highly reduced tax rate. By resetting your cost basis today, you effectively minimize the potential capital gains tax you would owe when you eventually sell the asset for a permanent exit years down the road. It is essentially a way to “pre-pay” your tax liability at a discount, clearing the path for greater net wealth in the future.

    This strategy is particularly relevant for those in the accumulation phase of wealth building. Many experts suggest that investors view their portfolios as a long-term project where tax management is a continuous process. If you have been holding high-growth assets for many years and have built up a massive pile of unrealized gains, waiting until retirement to sell everything could push you into a much higher tax bracket, leading to a significant “tax trap.” By slowly harvesting gains in favorable tax years, you can smooth out your tax burden over a decade or more. Furthermore, if you are looking to rebalance your portfolio—perhaps moving from a growth-heavy allocation to one that is more conservative—tax-gain harvesting allows you to shift assets without the same looming threat of a massive, surprise tax bill later. This approach transforms tax strategy from a reactive, year-end scramble into a deliberate, multi-year plan that supports your overarching financial goals.

    Strategy Primary Objective Best For
    Tax-Loss Harvesting Offsetting realized gains to lower current tax liability. Investors holding losing positions during market volatility.
    Tax-Gain Harvesting Resetting cost basis to reduce future tax exposure. Investors in lower income brackets or those seeking to rebalance.

    How High Interest Rates Impact Your Harvesting Strategy

    In an economic climate defined by higher interest rates, the landscape of investment tax strategy undergoes a subtle but vital transformation. When the risk-free rate—often represented by Treasury yields—is high, the hurdle rate for every asset in your portfolio increases. You are no longer just comparing your returns to a zero-percent interest environment; you are weighing your market investments against reliable, interest-bearing assets. This macro-shift changes the calculus for both tax-loss and tax-gain harvesting.

    When interest rates are elevated, the opportunity cost of holding cash or underperforming assets becomes much more tangible. Tax-loss harvesting becomes an even more critical tool because the tax savings you generate can be deployed into high-yield instruments that are currently paying attractive returns. Essentially, the “tax alpha” you extract from your portfolio has more places to work for you. If you harvest a loss and save 15% to 20% on a capital gain that would have otherwise been paid to the government, that capital can be immediately put into high-interest money market funds or short-term notes, compounding your wealth while your core market positions recover.

    Conversely, high interest rates can dampen the appeal of tax-gain harvesting for some. Because cash and bonds are providing a meaningful return, the “cost” of paying taxes early via gain harvesting might feel more painful. You are paying tax dollars now that could have been earning interest elsewhere. However, for the long-term wealth builder, the decision remains anchored in the delta between current and future tax rates. If you believe interest rates will eventually normalize downward and equity prices will continue to appreciate, the benefit of resetting your cost basis today to avoid a potential future “tax cliff” remains high.

    Moreover, the high-interest environment often leads to increased volatility in equity markets, as investors adjust their valuation models for discounted future cash flows. This volatility is a double-edged sword: it creates more opportunities for price dips that allow for loss harvesting, but it also creates uncertainty about the timing of long-term gains. Investors must remain vigilant. In 2026, the most successful wealth builders are those who view these high-interest conditions not as a reason to panic, but as a reason to be more tactical. Portfolio optimization in this environment requires a disciplined look at the yield of your “cash” assets versus the tax-adjusted return of your “risky” assets. By integrating your tax strategy with your interest-rate exposure, you create a robust defense against the erosion of your wealth.

    Calculating the Net Benefit of Offsetting Gains

    Determining whether to harvest a loss or a gain is a mathematical exercise that requires a clear understanding of your personal financial situation. The net benefit is not just about the dollars saved in the current tax cycle; it is about the long-term preservation of your capital base. To calculate this, you must first look at your realized gains for the calendar year. If your realized gains are substantial, the immediate tax benefit of harvesting losses is obvious: you avoid writing a check to the tax authorities.

    However, many investors fail to account for the “lost growth” on those tax dollars if they had remained invested. When you sell a losing position to harvest a loss, you might be selling an asset that has intrinsic value and is merely undergoing a temporary market correction. If that asset rebounds significantly shortly after you sell it, the “cost” of the loss harvest was the opportunity to participate in that recovery. This is why the “proxy” asset selection is so critical. If you can move your capital into an asset that tracks closely with your original holding, you effectively capture the tax benefit without sacrificing the long-term growth potential.

    To properly analyze the net benefit, you should map out your estimated tax bracket for the next three to five years. If you expect your income to rise significantly, harvesting a gain now—while you are in a lower bracket—is almost always mathematically superior. The tax you pay today is effectively a “premium” you are paying to ensure you don’t pay a higher rate tomorrow. Conversely, if you are nearing retirement and expect your income to drop, your priority should be minimizing current tax bills through aggressive loss harvesting.

    Furthermore, always factor in your local and state taxes. Capital gains are often taxed at both federal and state levels, which can significantly alter the net benefit. Many investors perform the math based on federal rates alone and underestimate the total impact. When you account for the combined impact of federal, state, and potential alternative minimum tax triggers, the benefit of an effective tax strategy becomes even more pronounced. This level of granular calculation is what separates passive index investors from sophisticated wealth builders. By maintaining a spreadsheet of your cost basis across all accounts, you can quickly identify which lots are optimal for harvesting at any given moment, ensuring you never leave money on the table.

    Avoiding the Wash-Sale Rule During Market Volatility

    The wash-sale rule is perhaps the most significant hurdle in the implementation of an effective tax-loss harvesting strategy. Under current regulations, you are prohibited from claiming a loss on a security if you purchase the same or a “substantially identical” security within 30 days before or after the sale. This rule applies to your entire portfolio, including IRAs, 401(k) plans, and spousal accounts. If you sell a stock in your taxable brokerage account for a loss and your spouse immediately buys the same stock in their IRA, the IRS considers that a wash sale, and you lose the ability to claim the tax benefit.

    Market volatility often tempts investors into rapid-fire trading, which increases the likelihood of accidentally violating the wash-sale rule. When a market sector takes a hit, the urge to capture losses across multiple positions can lead to sloppy trade execution. To avoid this, you must be systematic. Many investors use the “swap” method, where they sell an ETF that tracks a specific index and simultaneously buy an ETF that tracks a different, but similar, index. For example, if you sell an S&P 500 index fund, you might move into a total stock market index fund for the 30-day window. While these two funds are not identical, they provide nearly identical market exposure, allowing you to stay in the market while safely harvesting your tax loss.

    Documentation is your best defense against tax-related headaches. Keep meticulous records of the purchase and sale dates of every transaction, especially during the year-end period when many investors are frantically trying to optimize their tax positions. Many modern brokerage platforms now have built-in wash-sale trackers that flag potentially problematic trades, but you should never rely solely on automated systems. These tools can sometimes miss complex interactions, such as those involving automated dividend reinvestment plans (DRIP). If you have DRIPs enabled, a dividend payment occurring within that 30-day window could count as a “purchase” and trigger a wash sale.

    For those serious about wealth preservation, the safest approach during highly volatile times is to disable automatic dividend reinvestment for the specific securities you are planning to harvest. Manually reinvesting those dividends after the 30-day window closes is a small administrative burden that provides significant peace of mind. By respecting the wash-sale rule and integrating these safeguards into your routine, you can execute your tax-loss harvesting strategy with confidence, knowing that your tax advantages will be fully recognized by the authorities, thereby maximizing the efficiency of your investment portfolio.

    Integrating Harvesting Into Your Long-Term Portfolio Growth

    To build lasting wealth, investors must shift their perspective from viewing tax-loss and tax-gain harvesting as isolated events to treating them as fundamental components of a broader portfolio optimization strategy. In a high-interest rate environment, the opportunity cost of capital is elevated, meaning every dollar surrendered to the tax authority is a dollar that cannot compound at today’s attractive yields. Integrating these strategies requires a disciplined, year-round approach rather than a frantic scramble during the final days of December.

    A sophisticated integration strategy begins with systematic rebalancing. As your portfolio drifts due to market fluctuations, you inherently create opportunities. When an asset class outperforms, selling a portion of it to return to your target allocation may trigger a tax-gain harvesting event. If your portfolio is in a low-income year, this becomes a strategic moment to “reset” the cost basis of your holdings. Conversely, if you are in a high-income bracket, prioritizing tax-loss harvesting during these rebalancing periods can offset the drag of capital gains taxes, keeping more capital deployed in the market.

    Furthermore, consider the implementation of “tax-aware” index tracking. Rather than holding identical funds across all accounts, investors should aim to hold high-growth, high-turnover assets in tax-advantaged accounts while keeping tax-efficient assets in taxable brokerage accounts. When you integrate harvesting, you are essentially “pruning” your portfolio. Just as a gardener trims a plant to encourage more vigorous growth, harvesting allows you to remove underperforming assets (via tax-loss harvesting) or realize gains on winners (via tax-gain harvesting) to better align your holdings with your long-term wealth goals.

    The Role of Asset Location in Tax Management

    Asset location is arguably the most overlooked pillar of tax-efficient investing. While asset allocation determines your risk-return profile, asset location determines how much of that return you actually get to keep after the government takes its share. In the context of harvesting, your choice of account type dictates whether a specific harvest is even possible or beneficial.

    Taxable brokerage accounts are the primary theater for both tax-loss and tax-gain harvesting. Because these accounts are not shielded from capital gains taxes, they provide the flexibility to realize losses to offset future income or gains. Retirement accounts like Traditional IRAs or 401(k)s operate under a completely different paradigm. In these tax-deferred environments, harvesting is irrelevant because there is no immediate capital gains tax consequence for buying or selling. Therefore, attempting to “harvest” within a tax-deferred account is a waste of time and transaction costs.

    To maximize your wealth, prioritize placing high-tax assets—such as bonds or high-turnover mutual funds—in tax-advantaged accounts. Conversely, tax-efficient assets like broad-market ETFs or municipal bonds are better suited for taxable accounts. By strategically locating assets, you create an environment where your taxable account becomes a lean, efficient engine for growth. In high-interest rate environments, where bond yields provide significant taxable interest income, this distinction becomes even more critical. Keep interest-bearing instruments in sheltered accounts to avoid “tax-drag” on your annual returns.

    Strategy Primary Account Type Main Objective Best For
    Tax-Loss Harvesting Taxable Brokerage Offsetting current/future tax liability Investors in high-income tax brackets
    Tax-Gain Harvesting Taxable Brokerage Resetting cost basis to zero-percent bracket Investors in low-income tax brackets
    Asset Location Mixed (All) Reducing overall annual tax drag Anyone seeking long-term wealth accumulation

    Common Pitfalls That Destroy Tax-Harvesting Value

    Even the most well-intentioned investors often sabotage their own success through common errors that negate the benefits of harvesting. The most pervasive danger is the “Wash Sale Rule.” In many jurisdictions, including the United States, if you sell a security at a loss and purchase a “substantially identical” security within 30 days before or after the sale, the IRS disallows the loss for tax purposes. Many investors lose track of automated dividend reinvestment plans, which can inadvertently trigger a wash sale by purchasing the same security shortly after a loss is realized.

    Another pitfall is the pursuit of tax alpha at the expense of investment quality. Investors may hold onto a fundamentally flawed asset simply because they are waiting for a better time to harvest the loss, or they may sell a winning asset too early just to harvest a gain, potentially missing out on years of compounding growth. Always remember that investment decisions should be driven by the quality of the asset and its alignment with your risk profile. Taxes are a secondary consideration to fundamental investment performance.

    Finally, transaction costs can easily erode the small percentages gained through harvesting. In an era where many brokerages offer commission-free trading, the hidden cost is often the bid-ask spread. If you are moving large positions, ensure that the potential tax savings significantly outweigh the friction costs of the trade. If the savings are marginal, the effort may not be worth the operational complexity.

    Balancing Short-Term Tax Savings Against Long-Term Compounding

    The ultimate goal of any wealth-building journey is to maximize the compounding effect. Tax-loss harvesting provides a short-term liquidity boost by reducing your tax bill, which can be reinvested immediately. This is the definition of putting your tax savings to work. However, the true danger lies in becoming overly obsessed with short-term tax minimization, which can lead to “portfolio drift.”

    Consider the difference between a temporary tax deferral and a permanent reduction in capital gains. Tax-loss harvesting is essentially a tax-deferral strategy. You are pushing the tax liability into the future by lowering your cost basis today. If you are not careful, you may find yourself with a significantly higher potential tax bill down the road when you eventually sell those replacement assets. Therefore, this strategy works best when you maintain a long-term horizon and, if possible, hold assets until you are in a lower tax bracket or can utilize them for charitable giving or legacy planning.

    Ultimately, high-interest rate environments reward patience. By maintaining a disciplined approach to harvesting, you capture incremental gains that compound over decades. Do not let the quarterly obsession with tax efficiency derail your long-term commitment to a diversified, growth-oriented portfolio. The wealthiest investors are those who can successfully navigate the tension between the immediate need to manage taxes and the long-term necessity of letting their compound growth run uninterrupted.

    Frequently Asked Questions

    Does tax-loss harvesting work the same way in a 401(k) or IRA?

    No, tax-loss harvesting is ineffective in tax-advantaged accounts like 401(k)s or IRAs. Since these accounts do not trigger capital gains taxes on trades, there is no “taxable event” to offset. You should focus your tax-management efforts exclusively on your taxable brokerage accounts.

    What exactly is a “substantially identical” security?

    While the tax authorities do not provide an exhaustive list, a substantially identical security generally refers to the same stock or a fund that tracks the same index with very similar holdings. To avoid wash sales, many investors use “proxy” assets, such as switching from one S&P 500 index fund to another fund that tracks a different, though similar, index.

    Can tax-gain harvesting actually save me money if I am in a high tax bracket?

    Typically, tax-gain harvesting is most beneficial for those in lower income tax brackets who may qualify for a 0% long-term capital gains rate. If you are in a high tax bracket, realizing gains usually results in a tax bill that exceeds the benefit of resetting your cost basis. Always calculate your expected tax hit before executing this strategy.

    How often should I review my portfolio for harvesting opportunities?

    Many investors perform a comprehensive review at the end of the calendar year. However, in volatile markets, quarterly or monthly reviews can reveal more frequent opportunities. With modern portfolio management software, you can set alerts for when specific assets fall below your cost basis, allowing for a more proactive approach.

    Do state taxes impact my harvesting strategy?

    Yes, state taxes can significantly impact the net benefit of harvesting. Depending on where you live, you may have different rules regarding how capital losses are treated compared to federal law. Always consult with a tax professional who is familiar with your specific state’s tax code to ensure you are accounting for the total tax impact.

    Is tax-loss harvesting worth it if I only have small losses to harvest?

    It depends on your personal financial situation and the effort involved. If the tax savings are minimal, the time spent managing the wash sale rules and potential transaction costs might outweigh the benefit. Focus on larger positions where the tax-alpha is meaningful enough to justify the administrative overhead.

    Conclusion

    In the evolving financial landscape of 2026, the choice between tax-loss and tax-gain harvesting is not a binary decision. It is an exercise in balancing your current income profile with your long-term wealth aspirations. By understanding the mechanisms of each, respecting the constraints of asset location, and avoiding the common pitfalls of the wash sale rule, you can turn your tax strategy into a powerful engine for portfolio growth. Remember, the goal is not merely to pay less in taxes, but to maximize the amount of capital you have working for you in the market over the long haul. Stay disciplined, keep your long-term goals in sight, and consider speaking with a tax professional to tailor these strategies to your unique financial situation.

    Are you ready to optimize your investment strategy for the years ahead? Begin by reviewing your current brokerage statements to identify potential harvesting opportunities, and ensure your asset location aligns with your overall goals. Your path to greater wealth starts with informed, proactive management.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
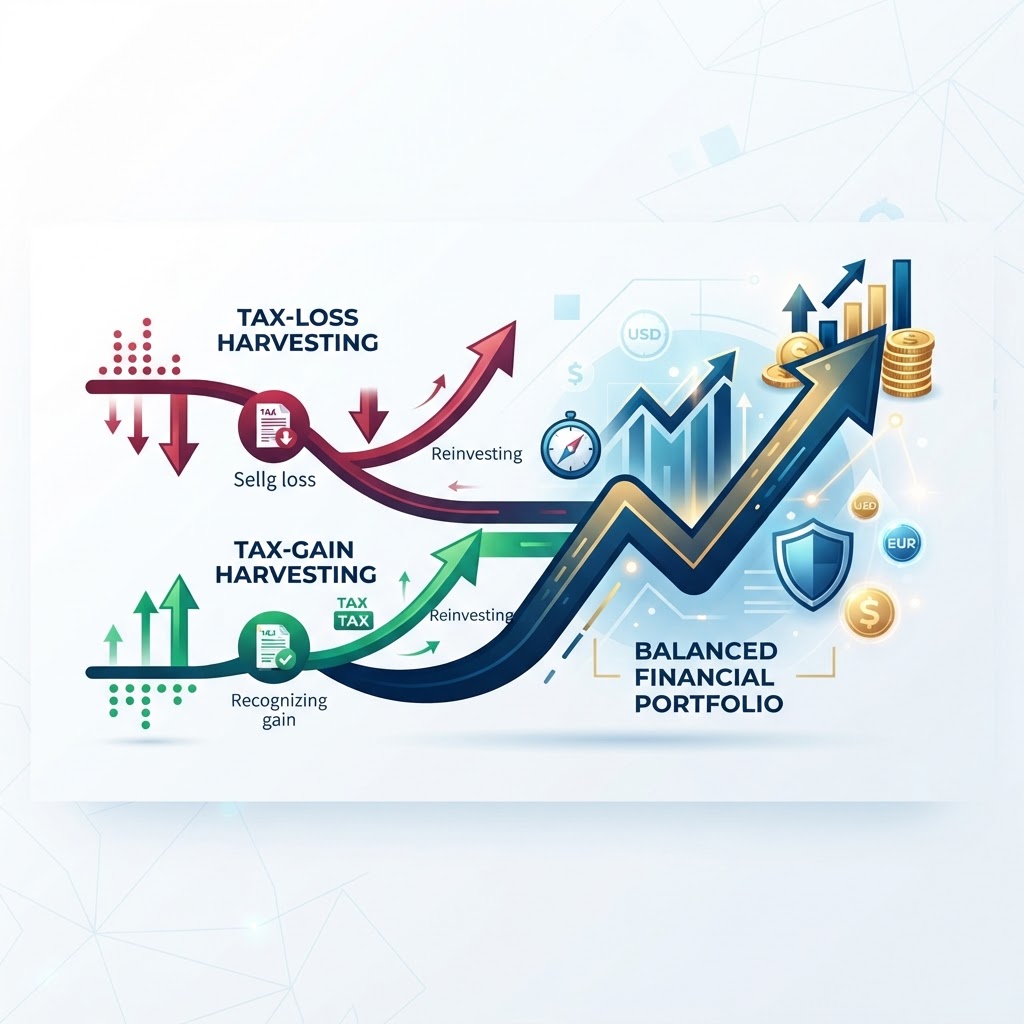
  • How to Set Financial Goals: A Proven Roadmap for Wealth

    How to Set Financial Goals: A Proven Roadmap for Wealth

    Key Takeaways

    • Wealth is not just a balance sheet figure; it is a tool for autonomy and long-term financial freedom.
    • Effective financial goal setting requires moving beyond vague intentions toward a structured, time-bound roadmap.
    • Long-term financial planning succeeds when macro visions are broken down into granular, daily habits.
    • Consistency in wealth building strategies often outweighs the impact of singular, high-risk financial decisions.
    • Successful wealth creation requires a psychological shift from consumption-based spending to asset-based accumulation.

    The journey toward prosperity is often misunderstood as a simple matter of earning more income or finding the perfect investment. However, true wealth is rarely the result of a single stroke of luck; it is the manifestation of intentional, disciplined, and strategic action over time. If you have found yourself struggling to navigate the noise of modern finance, you are not alone. Many individuals seek a reliable path to security, only to be met with conflicting advice and fragmented data. At wealthsimplyput, we believe that mastering your financial future begins with a clear, actionable framework. By understanding how to align your personal values with rigorous wealth building strategies, you can move from reactive saving to proactive wealth creation. This guide serves as your comprehensive blueprint for transforming how you view money, helping you build a sustainable, scalable, and secure financial legacy.

    Why Traditional Goal Setting Fails for Wealth Builders

    The conventional advice regarding financial goal setting often revolves around generic targets: “Save $10,000,” “Pay off debt,” or “Buy a home.” While these objectives are inherently positive, they frequently fail because they lack the necessary context of a holistic wealth creation roadmap. When goals are set in isolation, they become disconnected from the reality of your cash flow, risk tolerance, and long-term lifestyle aspirations. This disconnect is the primary reason many people abandon their plans after only a few months. Without a deep understanding of why you are saving, the discipline required to defer gratification feels like a punishment rather than a calculated step toward freedom.

    Furthermore, traditional methods often ignore the psychological aspect of money. Many people treat their finances as a rigid checklist, failing to account for life’s inevitable volatility. When an emergency or an unexpected expense arises—which is statistically likely—the rigid plan collapses. Experts generally suggest that successful wealth building requires a flexible structure that prioritizes system-building over fixed outcomes. Instead of focusing solely on a specific dollar amount, a robust approach focuses on building habits that generate wealth regardless of external market fluctuations. This means shifting your gaze from the goal itself to the process of asset acquisition, tax optimization, and the expansion of income streams.

    Another point of failure in traditional goal setting is the lack of granularity. A goal like “becoming a millionaire” is so abstract that the brain struggle to translate it into today’s actions. Because the reward is so far removed from the daily sacrifice, the motivation to keep working toward that goal diminishes over time. Effective financial planning must bridge the gap between today’s cup of coffee and tomorrow’s retirement. By failing to bridge this distance, most individuals fall into the trap of “lifestyle creep,” where their spending increases in direct proportion to their earnings. True wealth builders understand that the goal is not to have money, but to have money that works for them. By resetting your mindset to view money as a tool for autonomy rather than a scoreboard for consumption, you move from the failure of short-sighted planning into the success of structural wealth management.

    Defining Your Vision: Wealth as a Tool for Freedom

    Before you can construct a financial roadmap, you must define what wealth actually means to you. In the context of long-term financial planning, wealth is not merely an accumulation of luxury goods or a high net worth on paper; it is the ability to maintain autonomy over your time and decisions. This is the cornerstone of wealth creation—recognizing that money is the currency of freedom. If you do not define your vision, you will likely default to societal pressures, chasing investments or lifestyles that do not actually bring you satisfaction or security.

    Your vision should be deeply personal. Do you seek wealth to retire early and travel? Do you want to build a legacy for your family, start a business, or pursue philanthropy? Each of these visions requires a different approach to risk, liquidity, and time horizon. For instance, someone prioritizing early retirement may focus heavily on high-yield index funds and aggressive tax-advantaged savings, whereas someone focusing on multi-generational wealth might look toward estate planning and real estate holdings. When your goals are aligned with your internal values, the discipline required to maintain your wealth building strategies becomes significantly easier to sustain.

    Creating a vision is not a one-time exercise but an iterative process of self-discovery. We recommend writing down your “Freedom Number”—the amount of capital required to cover your living expenses through passive income alone. This number provides a tangible anchor for your financial planning. When you know your target, every financial decision becomes a binary choice: does this move me closer to my freedom, or further away? This framework helps strip away the emotional weight of spending. By shifting your perspective from “what can I buy” to “how does this impact my freedom,” you cultivate the intentionality required to build meaningful wealth. Remember, the goal is not just to be rich; the goal is to be free.

    Approach Primary Focus Best For
    Passive Indexing Low-cost broad market exposure Long-term wealth building with minimal oversight
    Active Entrepreneurship High-leverage income generation Building aggressive wealth through business equity
    Real Estate Strategy Cash flow and tax-advantaged leverage Investors seeking reliable, multi-generational returns
    Balanced Growth Diversification across multiple asset classes Those balancing risk mitigation with appreciation

    Setting Macro Goals: The 5-Year and 10-Year Wealth Vision

    Once you have defined your vision for financial freedom, you must transition into setting macro goals. A 5-year and 10-year outlook serves as the strategic framework for your wealth building journey. These macro goals prevent you from being distracted by short-term market noise or the latest trending investment. Think of these as your “North Star”—the destination you are working toward regardless of how the landscape changes. Setting these targets requires you to realistically assess your current starting position and project your trajectory based on historical patterns and consistent savings rates.

    In your 5-year outlook, focus on foundational stability and the creation of systems. This period is typically about clearing high-interest debt, building an emergency fund, and establishing a consistent habit of automatic investing. Many experts suggest that the first five years are the most critical, not because of the returns you see, but because of the behavioral patterns you establish. This is when you learn how to live on less than you earn and understand the power of compound interest. By the end of five years, your primary objective should be the stabilization of your net worth and the reduction of financial anxiety.

    Your 10-year outlook, by contrast, should shift toward aggressive growth and optimization. By this point, you should be moving from a phase of simple saving to a phase of strategic wealth creation. This might include diversification into new asset classes, tax-shielding strategies, or scaling your primary business income. In this decade, the power of compounding begins to show significant results, often leading to what is commonly referred to as the “tipping point,” where your assets begin to generate meaningful returns that can be reinvested. When planning these macro goals, always remain cognizant of the “Rule of 72,” which helps you understand the doubling time of your investments. While market conditions fluctuate, the focus of your macro plan should remain steady, ensuring that you are consistently building a portfolio that is robust, diversified, and aligned with your long-term vision of personal freedom.

    Breaking Down Milestones: Turning Big Goals Into Actionable Tasks

    A vision without a task list is just a daydream. To move from your macro 5-year and 10-year plans into reality, you must break these down into manageable, actionable milestones. The most effective wealth builders utilize a technique of reverse-engineering: start with your 10-year goal, divide it by the necessary steps in your 5-year plan, and then break those down into quarterly, monthly, and weekly habits. This process turns the intimidating task of “building wealth” into simple, daily rituals that are easy to maintain.

    For example, if your 5-year goal involves accumulating a specific level of capital, you can reverse-engineer this into a monthly contribution requirement. From there, you can identify the exact “levers” you have to pull to reach that contribution: reducing specific discretionary expenses, negotiating a raise at work, or creating a side income stream. These are your actionable tasks. If a task does not contribute to the movement of these needles, it is likely a distraction. By focusing only on the actions that have the highest impact on your wealth creation, you avoid the busywork that often masquerades as progress in the financial world.

    Consider the power of tracking. We suggest that you maintain a simple document or spreadsheet where you monitor these specific, granular tasks. When you can physically see the progress—whether it is a reduction in your debt-to-income ratio, an increase in your monthly dividend yield, or the successful completion of a tax-deduction strategy—the feedback loop reinforces your behavior. This is not about being obsessed with daily price changes, which can lead to poor decision-making; it is about being obsessed with the consistency of your inputs. As you hit these milestones, remember to reassess your trajectory periodically. Life changes, and your roadmap should be flexible enough to adapt. By mastering the art of breaking large visions into small tasks, you ensure that you are always moving forward, step by daily step, toward the life you have envisioned.

    The Psychology of Financial Consistency and Discipline

    Perhaps the most challenging aspect of long-term financial planning is not the mathematical component, but the psychological one. The desire for immediate gratification is deeply ingrained in human nature, and our modern economy is built on exploiting this impulse through targeted marketing and instant-access consumption. Developing the discipline to bypass this noise is the defining characteristic of a successful wealth builder. Consistency is the invisible engine of wealth; it is the reason why small, boring, repetitive actions often result in greater success than sporadic, high-stakes gambles.

    To cultivate this discipline, you must understand the concept of the “identity shift.” Rather than seeing yourself as someone who is “trying to save money,” begin to see yourself as someone who is an “asset allocator” or a “wealth builder.” When you change your identity, the way you interact with money changes automatically. You stop viewing an expense as a sacrifice and start viewing it as a choice between present consumption and future freedom. This mental framework makes the process of deferred gratification less of an internal battle and more of a natural reflection of your priorities.

    Managing the fear and greed cycles that often trigger impulsive financial behavior is also essential. When the market is volatile, the temptation to panic-sell or chase speculative bubbles is high. Experts often highlight that the best way to combat these impulses is through automation. When you automate your savings and investments, you remove the emotional element from the equation. Your plan continues to execute regardless of how you feel about the headlines of the day. Discipline is not about having superhuman willpower; it is about building a system that makes the right choice the default choice. By aligning your psychological state with a structured, automated system, you insulate yourself from the biggest enemy of wealth: your own impulses.

    How to Track Your Net Worth Against Your Goals

    Tracking your net worth is the ultimate scorecard for wealth building. While monthly budgeting tells you how you are spending your income, your net worth statement provides the macro view of your long-term financial health. Net worth is calculated simply as your total assets—everything you own with monetary value—minus your total liabilities, which are the debts you owe.

    To use this as an effective tool for your financial goals, you must establish a consistent cadence for reporting. Quarterly updates are typically sufficient for most individuals, as this timeframe is long enough to see the impact of market fluctuations and debt repayment, yet short enough to allow for tactical course corrections. You can use a dedicated spreadsheet, a manual ledger, or a secure personal finance aggregation tool to track these figures over time.

    When tracking, be diligent about including all assets: liquid cash, retirement accounts, brokerage portfolios, real estate equity, and even significant tangible property like vehicles, if applicable. On the liability side, list credit card balances, mortgage principals, student loans, and personal loans. Seeing these numbers side-by-side acts as a powerful motivator. When you see your assets growing while your liabilities shrink, you are effectively watching your wealth-creation roadmap materialize in real-time. If your net worth plateaus, it serves as a signal that your wealth-building strategies—such as your savings rate or investment allocation—may need to be adjusted to align back with your targets.

    Adjusting Your Strategy When Life Circumstances Change

    Financial planning is not a static exercise. A roadmap created when you are twenty-five will rarely remain relevant when you are forty-five. Life events—such as marriage, the arrival of children, career pivots, unexpected health challenges, or aging parents—will inevitably shift your financial priorities. The hallmark of successful wealth building is flexibility.

    Experts generally agree that an annual review of your financial plan is essential. During this review, ask yourself if your “Why” has shifted. If your primary goal was once aggressive accumulation for early retirement, but you have since decided you want to fund a child’s education or move to a more expensive region, your asset allocation must be recalibrated to support these new realities.

    When life throws a curveball, use the Prioritize, Pivot, or Pause method:

    • Prioritize: Re-rank your existing goals. If your income drops, shift your focus to maintaining the most critical wealth vehicles, such as your high-interest debt repayment or core retirement contributions.
    • Pivot: Change the path without abandoning the destination. For example, if you cannot reach your full investment goal due to a career transition, you might opt to extend your timeline rather than stop investing entirely.
    • Pause: Temporarily suspend lower-priority goals to protect your stability. If a major emergency arises, it is perfectly acceptable to pause non-essential savings until you have regained your footing.

    Remember, the goal of long-term financial planning is not rigid adherence to a document, but rather the creation of a system that can withstand the volatility of human experience. Adjusting your strategy is not a sign of failure; it is a demonstration of mastery over your financial destiny.

    Avoiding Common Pitfalls in Long-Term Financial Planning

    Even the best-laid plans can fall victim to behavioral biases and oversights. Recognizing these traps before they impede your progress is a crucial part of your wealth creation roadmap. One of the most common pitfalls is “lifestyle inflation”—increasing your spending every time you receive a raise or a bonus. By keeping your expenses stable as your income climbs, you create a larger “gap” that can be diverted into wealth-building assets.

    Another frequent error is chasing short-term performance. Investors often succumb to the urge to sell assets when markets drop or buy into speculative bubbles during market highs. This emotional decision-making is the enemy of compound growth. Wealth creation requires patience and a long-term horizon; focusing on consistent, boring habits usually yields better results than attempting to time the market.

    We have summarized these and other strategic considerations below to help you navigate the common hurdles of wealth building:

    Strategy Pitfall The Fix Best For
    Lifestyle Inflation Automate savings increments whenever income increases. Increasing your long-term savings rate.
    Market Timing Adopt a “set it and forget it” dollar-cost averaging plan. Reducing emotional investment stress.
    Over-Complexity Focus on low-cost, broadly diversified index funds. Beginners and busy professionals.
    Ignoring Inflation Ensure your portfolio targets returns above inflation rates. Preserving long-term purchasing power.

    Finally, never underestimate the risk of over-reliance on a single stream of income or a single asset class. Diversification is the only “free lunch” in finance. Spreading your risk across different sectors and asset types ensures that your overall wealth remains insulated even when one specific area of the economy experiences a downturn.

    Leveraging Automation to Stay on Track With Your Goals

    The greatest threat to long-term financial planning is human inconsistency. We forget to save, we rationalize spending, and we lose focus during busy periods of life. Automation is the antidote to these human limitations. By creating a system that operates in the background, you move from “trying to save” to “guaranteed progress.”

    Start by automating your primary savings and investment contributions. Set these to occur on the day your paycheck arrives. By treating your savings as a mandatory “bill” that must be paid to your future self first, you remove the temptation to spend those funds on discretionary items. Most modern banking and brokerage platforms allow you to schedule recurring transfers with ease.

    Beyond savings, consider automating your debt repayments. Setting up autopay for your fixed debt obligations not only ensures you never miss a payment—which protects your credit score—but also helps you plan your cash flow more accurately. If you have variable debt, such as credit cards, use automation to pay the full statement balance every month. This prevents interest charges from eroding your wealth-building efforts.

    Finally, set up automated alerts for your accounts. Knowing when a balance drops below a certain threshold or when a large transaction clears can help you catch potential issues before they spiral. Automation acts as a financial guardrail, ensuring that even on your most distracted days, your path to wealth continues to move forward.

    Frequently Asked Questions

    How much of my income should I be saving to build wealth?

    While financial experts often suggest a baseline of 15% to 20% of your gross income, the ideal amount depends on your specific goals and your timeline. If you are starting late or have an aggressive goal to retire early, you may need to increase that percentage. The most important factor is consistency rather than a specific target number.

    What is the difference between saving and investing?

    Saving refers to setting aside money for short-term needs, typically in low-risk accounts like a high-yield savings account where capital preservation is the priority. Investing involves purchasing assets like stocks, bonds, or real estate with the goal of achieving growth that outpaces inflation over a long period. Wealth creation generally requires a strategic mix of both.

    Is it better to pay off debt or start investing?

    This is a common debate. Most experts suggest a balanced approach. If you have high-interest debt, such as credit card debt, the interest cost is likely higher than your expected investment returns, making debt repayment the priority. However, if your debt is low-interest (like a mortgage or federal student loans), you may benefit more from investing your money in the market simultaneously.

    What if I don’t have enough money to start investing?

    You can begin with surprisingly small amounts. Many modern brokerage platforms allow you to open accounts with no minimum balance and purchase fractional shares of stocks or ETFs. The most critical component of wealth building is not the size of your initial deposit, but the habit of contributing consistently and letting compound interest work over time.

    How do I know if my investment strategy is right for me?

    A “right” investment strategy is one that aligns with your risk tolerance, your time horizon, and your financial goals. If you find yourself losing sleep over market volatility, your strategy may be too aggressive. If your portfolio is growing too slowly to reach your goals, it may be too conservative. Regular reviews will help you keep your risk profile in balance with your objectives.

    Can I build wealth if I have a low salary?

    Building wealth is more about your “savings rate”—the percentage of your income you keep—than it is about your total salary. While a high income makes it easier to save, wealth creation is fundamentally a game of controlling expenses and investing the difference. By living below your means and prioritizing long-term growth, you can build significant wealth on almost any income level over a long enough time horizon.

    Conclusion

    Setting financial goals is the foundation of every success story in personal finance. By shifting from a mindset of passive spending to active, goal-oriented wealth building, you regain control over your future. Remember that wealth is not just about the numbers in your bank account; it is about the freedom to make choices, the security to handle emergencies, and the ability to build a legacy. Use the steps outlined in this roadmap—defining your purpose, tracking your net worth, staying flexible, and leveraging automation—to begin your journey today. Success in wealth building is rarely about overnight breakthroughs; it is about the quiet, consistent discipline of taking one small step forward every single day. Start your plan, monitor your progress, and stay committed to the long-term vision of your own financial freedom.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Capital Gains Tax: How to Minimize Liability and Build Wealth

    Capital Gains Tax: How to Minimize Liability and Build Wealth

    Key Takeaways

    • Capital gains tax acts as a silent wealth-killer by eroding the compounding power of your investments over time.
    • Understanding the difference between short-term and long-term holding periods is the first step in effective tax planning.
    • Strategic asset location involves placing specific types of investments in accounts that offer the most tax efficiency.
    • Tax-loss harvesting allows investors to offset realized gains with realized losses, effectively lowering the overall tax burden.
    • Proactive wealth management requires a consistent, long-term perspective to minimize liability and maximize net returns.

    For many investors, the primary focus is on selecting the right stocks, funds, or real estate to grow their portfolios. However, the true secret to sustained wealth building lies not just in the gross returns your investments generate, but in how much of that growth you are allowed to keep. Capital gains tax is a significant factor in the trajectory of your financial journey. Without a deliberate investment tax strategy, you may find that the government claims a substantial portion of your potential compounding growth, leaving you with less capital to reinvest. By understanding how to reduce capital gains through informed decision-making, you can effectively shorten the time it takes to reach your wealth goals.

    Understanding How Capital Gains Tax Erodes Wealth

    At its core, capital gains tax is a levy on the profit realized from the sale of an asset. Whether it is stocks, bonds, precious metals, or real estate, the increase in value from the purchase price to the sale price is considered a gain. While paying taxes is a civic duty, failing to manage these obligations can significantly impair your long-term wealth. The issue is essentially one of “drag.” Every dollar that leaves your portfolio to cover a tax bill is a dollar that can no longer participate in the power of compounding interest.

    When you trigger a capital gains tax event, you reduce your principal. If you have $100,000 growing at a steady annual rate, and you are forced to pay a large tax bill out of that principal, the base amount that earns interest in the following years is smaller. Over a decade or two, the difference between a portfolio that is shielded from unnecessary taxes and one that is not can result in a disparity of tens or even hundreds of thousands of dollars. This is why wealth management experts often suggest that your tax strategy should be just as robust as your stock-picking strategy.

    Many investors mistakenly view taxes as an inevitable expense that happens at the end of the year, rather than a variable they can influence. By failing to account for the tax implications of every trade or asset transition, investors often sacrifice long-term gains for short-term liquidity or reactive decision-making. Wealth building is a marathon, not a sprint. The “drag” caused by taxes is most noticeable over long time horizons. When you realize a gain, you are effectively paying the government a portion of your future growth potential. To build significant wealth, you must shift your perspective to view tax-efficiency as a core component of your return on investment. Minimizing your tax bill is not about evasion; it is about leveraging the legal structures provided by tax codes to ensure that your money remains in your account, working harder for you, rather than being depleted by tax liabilities that could have been deferred or avoided altogether.

    Short-Term vs. Long-Term Capital Gains Tax Rates

    The distinction between short-term and long-term capital gains is fundamental to any sound tax planning effort. In most jurisdictions, tax authorities apply a significantly higher tax rate to assets held for one year or less, classifying these as short-term gains. These are typically taxed as ordinary income, meaning they are subject to your personal marginal tax bracket. Depending on your income level, this can result in a tax rate that is substantially higher than the rate applied to long-term holdings.

    Long-term capital gains, by contrast, apply to assets held for more than one year. These gains generally receive preferential tax treatment, often taxed at lower rates than ordinary income. This structure is designed to incentivize investors to commit their capital for the long haul, fostering economic stability and encouraging the growth of enterprises. For the wealth-focused individual, the difference between these two rates is often the difference between a robust retirement fund and one that barely keeps pace with inflation.

    Approach Tax Treatment Best For
    Short-Term Strategy Ordinary Income Rates Active Traders/Liquidity
    Long-Term Strategy Preferential/Reduced Rates Wealth Accumulators
    Tax-Advantaged Accounts Deferred or Tax-Free Long-Term Compounding

    When you are in the process of wealth building, your objective should be to prioritize the long-term holding period whenever possible. Frequently selling assets to “chase” market trends often leads to a higher frequency of short-term capital gains, which are immediately eroded by tax payments. By holding your positions for more than a year, you essentially grant yourself a “tax discount” on your profits. This practice aligns perfectly with the principles of value investing and long-term growth, as it encourages you to research your investments thoroughly and stick with high-quality assets rather than engaging in speculative, short-lived trades.

    Additionally, keeping an eye on your holding periods allows you to manage your tax liability proactively. If you are approaching the one-year mark on a profitable investment, it is often wise to wait until that threshold is crossed before selling, provided the fundamentals of the investment remain sound. This small behavioral adjustment can have a meaningful impact on your net after-tax return. Ultimately, the tax code is a roadmap; by following the path that rewards longer holding periods, you align your personal financial interests with the structural incentives of the broader economy, allowing your wealth to compound more efficiently over time.

    The Role of Tax-Advantaged Accounts in Avoiding Capital Gains

    If you want to build wealth effectively, you must utilize the tools that are designed to shield you from the immediate burden of capital gains tax. Tax-advantaged accounts—such as retirement plans, pension schemes, or specific savings vehicles provided by governments—are the cornerstone of a sophisticated investment tax strategy. These accounts function as a “walled garden” for your money, protecting it from the annual erosion of taxes on dividends, interest, and realized capital gains.

    In many of these accounts, capital gains tax is deferred, meaning you do not pay taxes on the profit generated within the account until you make a withdrawal. This deferral is incredibly powerful. Because you aren’t paying taxes on your gains every year, the entire amount of your profit is reinvested back into the market. This creates a “snowball effect” where your money earns returns on the tax money you would have otherwise paid. Over decades, this results in a significantly larger total accumulation than you could achieve in a standard taxable brokerage account, where the annual “tax bite” limits your reinvestment potential.

    Some accounts, such as Roth-style vehicles, take this a step further by offering tax-free growth. In these scenarios, you pay taxes on the money before it enters the account, but the future growth—and the eventual withdrawals—are entirely free from capital gains tax. These are perhaps the most effective instruments in the arsenal of a wealth builder. When choosing where to put your money, you should always maximize contributions to these tax-advantaged accounts before placing excess capital in taxable brokerage accounts. This isn’t just about retirement planning; it is about wealth management at the structural level. By prioritizing these accounts, you ensure that as much of your capital as possible is protected from the annual depletion caused by tax obligations.

    It is important to remember that tax laws can be complex and vary significantly based on your residency and specific financial situation. However, the general principle remains constant: wherever the law allows you to defer or eliminate taxes on investment growth, you should aim to utilize those structures fully. This includes employer-sponsored plans, individual retirement arrangements, and education or health savings accounts depending on your jurisdiction. By shifting your assets into these protected spaces, you move from a reactive tax state to a proactive wealth-building posture, where your focus remains on the growth of the portfolio rather than the tax consequences of your success.

    Strategic Asset Location: Keeping High-Growth Assets in the Right Accounts

    Strategic asset location is an advanced wealth-building technique that involves placing specific types of investments in the accounts where they will be most tax-efficient. Not all investments generate the same kind of tax burden. For example, dividend-paying stocks or high-yield bonds generate “income” that is taxed annually, whereas growth-oriented assets may generate large capital gains only when sold. If you hold these assets haphazardly, you are likely leaving money on the table.

    As a general rule, investments that generate significant annual taxable income, such as real estate investment trusts (REITs) or high-interest bonds, are often better suited for tax-advantaged accounts. Because these investments generate annual cash flow, they would be taxed every single year if held in a standard account. By placing them in a tax-deferred or tax-free account, you shield that cash flow from immediate taxation, allowing it to compound without interruption. This is the essence of smart tax planning: you are not just choosing *what* to buy, but *where* to put it.

    On the other hand, assets that you intend to hold for the very long term with the expectation of significant price appreciation—such as index funds or growth stocks—are often candidates for taxable brokerage accounts, provided you have a long time horizon. While you will eventually pay capital gains tax upon sale, the ability to hold these for years allows you to benefit from the lower long-term tax rates. Furthermore, if you hold these assets in a taxable account, you retain the flexibility to sell them if you need liquidity for life events without triggering the specific restrictions or penalties associated with pulling funds from a retirement-focused account.

    Implementing a strategy of asset location requires a holistic view of your entire portfolio. You shouldn’t think of your accounts as separate silos; instead, treat your global portfolio as one cohesive entity. By coordinating your holdings across all your accounts, you can ensure that you are paying the absolute minimum amount of tax legally required. This might involve rebalancing your portfolio periodically to maintain this structure. While it requires a bit more administrative effort, the long-term impact on your net wealth can be substantial. For individuals seeking to build enduring wealth, this level of attention to detail is what separates a casual investor from an efficient, strategic wealth manager.

    Utilizing Tax-Loss Harvesting to Offset Gains

    Even with the best intentions, you may occasionally find yourself in a position where you need or choose to sell an investment for a profit, thereby triggering a capital gains tax liability. This is where tax-loss harvesting becomes a critical tool for minimizing your tax impact. Tax-loss harvesting is the practice of selling an investment that has lost value to “realize” a loss. This loss can then be used to offset, or cancel out, the capital gains you have realized elsewhere in your portfolio, effectively reducing the net amount of gain that is subject to taxation.

    For instance, imagine you have realized a $5,000 gain on a high-performing tech stock you decided to sell. Ordinarily, you would owe taxes on that $5,000. However, if you also hold a lagging position in your portfolio that is down by $3,000, selling that underperforming asset allows you to report a $3,000 loss. This reduces your net taxable gain to only $2,000. You have successfully lowered your tax burden by selling an asset that was failing to meet your investment objectives anyway.

    The beauty of tax-loss harvesting is that it allows you to clean up your portfolio while simultaneously managing your tax obligations. It encourages you to regularly audit your holdings and prune the “dead wood”—those investments that have lost their investment thesis or are consistently underperforming. However, it is vital to be aware of rules like the “wash sale” rule, which prohibits you from claiming a tax deduction for a security sold at a loss if you purchase a “substantially identical” security within a short period (typically 30 days before or after the sale). Navigating these regulations is part of professional wealth management, ensuring that you optimize your outcome without violating tax laws.

    Ultimately, tax-loss harvesting provides a safety valve for your portfolio. It ensures that the bad decisions or market fluctuations you experience don’t hit you twice. Not only do you suffer the loss of value in an asset, but without harvesting, you would also be unable to utilize that loss to protect your other successful gains. By being proactive and monitoring your portfolio for opportunities to harvest losses, you keep your tax efficiency high and ensure that your wealth-building momentum remains on track, regardless of market volatility. This is a fundamental technique for anyone serious about managing their capital as efficiently as a business would manage its balance sheet.

    The Benefits of Holding Period Optimization for Tax Efficiency

    One of the most powerful levers in effective wealth management is the strategic control of your investment holding periods. In the realm of investment tax strategy, the distinction between short-term and long-term capital gains is not merely a technicality; it is a fundamental driver of net returns. By aligning your exit strategy with the tax code’s preferential treatment for assets held longer than one year, you can significantly reduce capital gains drag on your portfolio growth.

    When an investor sells an asset held for one year or less, the profit is taxed as ordinary income. Depending on your tax bracket, this could result in a substantial portion of your gains being surrendered to the government. Conversely, long-term capital gains are subject to significantly lower tax rates. This differential acts as a “tax alpha”—extra return generated simply by managing the timing of your sales rather than the underlying performance of the assets themselves.

    To maximize this benefit, investors should adopt a disciplined approach to asset location and duration. For instance, if you find yourself needing to rebalance your portfolio, consider whether an asset is approaching its one-year anniversary. Waiting a few weeks or even days to clear that one-year threshold can often result in a permanent reduction in your tax liability. This is not about market timing, which is notoriously difficult; it is about “tax timing.” By focusing on the calendar as much as the market price, you preserve more capital, which then compounds over time—a cornerstone of long-term wealth building.

    Furthermore, holding period optimization encourages a more patient investment philosophy. High-frequency trading is often the enemy of wealth creation because it triggers frequent, higher-taxed events. By committing to a longer-term horizon, you reduce your overall tax burden, minimize transaction costs, and allow your compounding returns to work without interruption. This approach transforms tax planning from a reactive end-of-year activity into a proactive, ongoing wealth management strategy.

    Charitable Gifting of Appreciated Securities to Reduce Tax Burdens

    For individuals focused on significant wealth preservation, charitable giving offers a dual advantage: supporting causes you care about while simultaneously eliminating capital gains tax exposure. When you hold securities that have appreciated substantially, selling them to donate the cash proceeds is rarely the most efficient path. The sale triggers a capital gains tax event that reduces the total amount available to donate, as well as your own net wealth.

    The smarter approach involves gifting the appreciated securities directly to a qualified charitable organization. Because the charity is tax-exempt, it can sell the securities without incurring any capital gains tax. As the donor, you typically qualify for a tax deduction based on the full fair market value of the assets at the time of the donation (provided you have held the assets for more than one year). This strategy effectively bypasses the tax collector entirely while providing the full value of your investment to the charity.

    Consider the scenario of a long-term investor holding shares of a stock that has increased significantly in value over a decade. By donating those shares directly, you avoid paying the tax that would have been due upon a private sale. You then have the option to use the cash you would have donated to “buy back” the same stock or a similar asset at a higher cost basis. This “step-up” in cost basis is an excellent way to reset your portfolio’s tax exposure, making future sales less costly from a tax perspective.

    This method requires coordination with the receiving institution to ensure they are equipped to accept non-cash assets. Many larger charities and community foundations have systems in place to process these transfers seamlessly. For those who wish to distribute their giving over several years, a Donor-Advised Fund (DAF) can serve as an ideal vehicle, allowing you to donate appreciated assets now, receive the immediate tax deduction, and grant the funds to your favorite charities at your own pace.

    Strategy Primary Benefit Best For
    Direct Security Donation Avoids capital gains tax and provides full deduction Individuals with large, concentrated positions
    Donor-Advised Fund (DAF) Immediate tax deduction, delayed distribution Those wanting to systematize philanthropic goals
    Tax-Loss Harvesting Offsets gains with realized investment losses Active portfolios experiencing market volatility
    Holding Period Optimization Qualifies for lower long-term tax rates All long-term wealth builders

    Step-Up in Basis: Leveraging Inheritance for Wealth Preservation

    Wealth building often spans generations, and the “step-up in basis” is perhaps one of the most critical tax provisions for intergenerational wealth transfer. When an individual inherits assets such as stocks, real estate, or business interests, the tax basis of those assets is generally “stepped up” to their fair market value on the date of the original owner’s passing. This is a powerful tool for reducing future capital gains tax liabilities.

    If a parent purchased a stock for $10,000 years ago, and that stock is worth $100,000 when they pass away, the heir receives the stock with a new cost basis of $100,000. If the heir decides to sell the stock immediately after inheriting it, they effectively owe zero capital gains tax because the gain since the original purchase has been erased by the step-up. This provision prevents heirs from being penalized by the tax system for the long-term appreciation achieved by the previous generation.

    Understanding this rule is essential for estate planning and wealth management. It suggests that, in many cases, it may be more tax-efficient to hold onto highly appreciated assets until they can be passed on to heirs rather than selling them during one’s lifetime. By holding these assets, you are essentially preserving the tax-free appreciation for your beneficiaries, which can substantially increase the net wealth transferred to the next generation.

    However, it is vital to keep detailed, accurate records of the date of death and the value of assets at that time. Appraisals for non-marketable assets, such as real estate or private company equity, are necessary to substantiate the new cost basis to tax authorities. Without proper documentation, heirs may find themselves facing unnecessary scrutiny or being unable to prove their stepped-up basis, which can lead to significant tax leakage.

    Evaluating the Cost of Selling Versus Holding for Long-Term Wealth

    Every decision to liquidate an investment carries an implicit tax cost. To build wealth effectively, one must treat that tax cost as a deduction from the asset’s total return. Before selling any asset, investors should perform a “Net Proceeds Analysis.” This involves calculating the projected gain, the applicable tax rate based on your holding period, and the potential impact of reinvesting the net cash.

    Sometimes, the desire to move funds into a “better” opportunity ignores the tax friction. If you sell an investment with a significant gain to move into an alternative that provides only a slightly higher projected return, the capital gains tax paid at the point of sale may actually result in lower total wealth over the long term. The “tax drag” created by the sale acts as a hurdle that the new investment must overcome just to break even with the original position.

    Consider the power of tax deferral. When you hold an asset, the full amount of your capital remains invested, allowing you to earn returns on money that would have otherwise been sent to the IRS. Over decades, this “tax-deferred compounding” is a massive driver of wealth. The decision to hold should be viewed as an intentional strategy, not just inertia. Only when the fundamental thesis for an investment changes, or when specific tax-management needs (like tax-loss harvesting) arise, should you consider disrupting this compounding process.

    Ultimately, the goal is to maintain control over your tax bill rather than allowing it to control your portfolio. By minimizing turnover, utilizing tax-advantaged accounts where appropriate, and strategically timing your exits, you build a foundation of wealth that is resilient against market fluctuations and tax erosion alike. Success in wealth management is often found in the choices you refrain from making as much as in the choices you actively pursue.

    Frequently Asked Questions

    What is the difference between short-term and long-term capital gains?

    Short-term capital gains apply to assets held for one year or less and are taxed as ordinary income at your standard tax rate. Long-term capital gains apply to assets held for more than one year and generally qualify for preferential, lower tax rates, making them a cornerstone of efficient wealth building.

    How can I reduce capital gains tax if I need to sell an investment?

    One primary strategy is tax-loss harvesting, which involves selling underperforming assets at a loss to offset the gains from successful investments. Additionally, you can time your sales to ensure they qualify for the lower long-term capital gains tax rates or donate highly appreciated assets directly to charity.

    What is a step-up in basis and how does it help with wealth preservation?

    A step-up in basis occurs upon the inheritance of an asset, where the cost basis is adjusted to the asset’s fair market value on the date of the original owner’s death. This effectively wipes out the capital gains liability for the appreciation that occurred during the owner’s lifetime, allowing heirs to inherit wealth with a higher cost basis.

    Can I use capital losses to lower my tax bill?

    Yes. If you have realized capital losses, they are first used to offset your capital gains. If your losses exceed your gains, you can typically use up to a specific amount of the excess loss to offset your ordinary income each year, with the remaining losses carried forward to future years.

    Is it ever better to pay capital gains tax instead of holding an asset?

    Yes, it may be better to pay the tax if you have a compelling reason to rebalance your portfolio, if the original investment no longer aligns with your risk tolerance or financial goals, or if you identify an investment opportunity with significantly higher growth potential that justifies the immediate tax expense.

    How does a Donor-Advised Fund help in managing capital gains?

    A Donor-Advised Fund allows you to contribute appreciated assets like stocks directly to the fund, which removes the asset from your taxable estate and allows you to claim an immediate tax deduction. The fund can then sell the assets without incurring capital gains tax, and you can distribute the proceeds to various charities over time.

    Conclusion

    Mastering the intricacies of capital gains tax is not merely about staying compliant with the law; it is about protecting the growth engine of your financial life. By integrating the strategies discussed—holding period optimization, charitable gifting, leveraging the step-up in basis, and careful exit evaluation—you move from being a passive taxpayer to an active architect of your own wealth. The difference between realizing your full financial potential and leaving significant capital on the table often comes down to the quality of your tax planning. Take the time to audit your current portfolio, understand your cost basis, and consult with a tax professional to ensure that every investment move you make is aligned with your long-term wealth building objectives. Start optimizing today, and let compounding returns work in your favor.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • Tax-Loss vs Tax-Gain Harvesting: A Wealth Building Strategy

    Tax-Loss vs Tax-Gain Harvesting: A Wealth Building Strategy

    Key Takeaways

    • Tax-loss harvesting involves selling underperforming assets to offset capital gains and lower your annual tax bill.
    • Tax-gain harvesting is a proactive strategy to reset your cost basis in investments to a higher level, potentially reducing future taxes.
    • The core difference lies in their purpose: one focuses on immediate tax relief, while the other focuses on long-term tax efficiency and future savings.
    • Wash-sale rules are a critical consideration when implementing tax-loss harvesting to ensure your trades remain compliant with tax authorities.
    • Effective wealth building requires balancing these strategies based on your current income, future tax bracket expectations, and overall financial goals.

    Managing the intersection of your portfolio performance and your annual tax bill is a hallmark of sophisticated wealth building. While many investors focus primarily on asset allocation or security selection, the most successful individuals understand that keeping more of what you earn is just as important as how much you earn. Two of the most powerful tools in an investor’s arsenal are tax-loss harvesting and tax-gain harvesting. By strategically managing when you realize gains and losses, you can improve your overall tax efficiency, mitigate the impact of market volatility, and ultimately accelerate the growth of your net worth over the long term. This guide explores how these two distinct approaches work, when to deploy them, and how to integrate them into a cohesive financial plan.

    What Is Tax-Loss Harvesting and How Does It Work

    Tax-loss harvesting is a fundamental technique used in investment strategy to reduce the amount of capital gains tax an individual owes. At its core, the process involves selling investments that have declined in value—effectively “harvesting” the loss—to offset the taxes due on assets that have been sold for a profit. If your total losses exceed your total gains in a given tax year, you can typically use the remaining net loss to offset a portion of your ordinary income, providing a dual benefit for your tax planning efforts.

    To implement this, an investor identifies securities within their taxable brokerage account that are trading below their original purchase price. By selling these positions, you create a realized loss. If you simultaneously sell an appreciated asset, the loss from the underperforming asset cancels out the gain from the profitable one, effectively lowering your taxable income for the year. This is particularly valuable during market downturns, as it allows you to turn a difficult financial period into a tax-saving opportunity.

    However, simply selling and walking away is often not the goal. If you still believe in the long-term potential of the investment you just sold, you might consider repurchasing a “substantially identical” security to maintain your exposure to that sector or asset class. This is where investors must be exceptionally careful of the “wash-sale rule.” Tax authorities generally prohibit claiming a loss if you purchase the same or a substantially identical security within 30 days before or after the sale. Violating this rule results in the loss being disallowed for immediate tax purposes, rendering the harvesting attempt ineffective.

    To avoid this, many investors use a strategy known as “tax-loss harvesting pair trading.” This involves selling a security and immediately purchasing a similar, but not identical, alternative. For example, if you sell an exchange-traded fund (ETF) that tracks a specific index, you might replace it with another ETF that tracks a different index covering the same sector. By doing this, you capture the tax benefit of the loss while keeping your market participation intact. This systematic approach to managing your portfolio creates significant tax efficiency over time, as the “tax alpha” generated by these transactions can compound just like investment returns.

    It is important to remember that tax-loss harvesting is not about locking in a permanent loss. It is about timing. By deferring taxes to a future date, you are essentially obtaining an interest-free loan from the government, allowing that capital to remain invested and working for you. Over decades, this “tax drag” reduction can significantly enhance your total wealth, especially for those in higher tax brackets who face more aggressive capital gains taxation.

    Understanding Tax-Gain Harvesting for Strategic Planning

    While tax-loss harvesting is a defensive move often triggered by market volatility, tax-gain harvesting is a proactive, strategic decision used to reset your cost basis. In many tax jurisdictions, long-term capital gains are taxed at more favorable rates than ordinary income. Tax-gain harvesting involves intentionally selling assets that have appreciated in value, realizing the gain, and then immediately repurchasing those same assets.

    The primary objective here is to increase your cost basis. By selling the asset, you pay tax on the gain you have accrued up to that point. By immediately buying the asset back, your new purchase price becomes the cost basis for that security. This is particularly useful for investors who expect their future tax rates to be higher than their current rates. If you are currently in a lower tax bracket—perhaps due to a temporary reduction in income or early retirement—you can “harvest” your gains now at a lower tax rate (or even zero percent, depending on your income level) to avoid paying a higher tax rate when you eventually sell those assets years down the road.

    This strategy is the opposite of tax-loss harvesting in terms of immediate tax impact. Instead of lowering your tax bill for the current year, you are choosing to pay a tax bill now to secure a tax advantage later. This requires careful forecasting of your future financial situation. For example, a young professional who anticipates significant career growth might realize that they will be in a much higher tax bracket in ten years. By harvesting gains during their early career, they lock in current, lower capital gains tax rates, effectively “pre-paying” the tax at a discount.

    Furthermore, tax-gain harvesting can be a powerful tool for portfolio rebalancing. When specific sectors or individual stocks perform exceptionally well, they often grow to represent a disproportionately large percentage of your portfolio, increasing your risk profile. By selling these winners to harvest the gains, you not only manage your tax basis but also return your portfolio to its target asset allocation. This dual-purpose strategy keeps your wealth building on track while ensuring your tax liability remains managed.

    Unlike the wash-sale rule, which penalizes the rapid repurchase of assets sold for a loss, there is no such restriction on repurchasing assets sold for a gain. You can sell a stock, realize the gain, and buy it back seconds later without any tax consequences regarding the “wash-sale” rule. This makes tax-gain harvesting a cleaner, albeit more tax-heavy, transaction. It is an exercise in long-term planning, requiring you to weigh the immediate cost of taxes against the projected benefit of a higher cost basis in the future.

    The Fundamental Differences Between Harvesting Gains and Losses

    To master wealth building, you must distinguish between the tactical application of these two methods. While both fall under the umbrella of tax planning, their objectives and mechanics serve different roles in your overall financial ecosystem. Tax-loss harvesting is essentially a reaction to market performance, aimed at minimizing immediate tax burdens during periods of downward price pressure. Tax-gain harvesting, by contrast, is a planned exercise in tax optimization, aimed at managing the future cost basis of your portfolio.

    Feature Tax-Loss Harvesting Tax-Gain Harvesting Best For
    Primary Goal Minimize current year taxes Optimize future tax liability Balancing portfolios
    Market Context Declining or volatile markets Periods of lower income/tax rates Long-term wealth building
    Repurchase Rules Must respect wash-sale rules No wash-sale restrictions Strategic execution

    The timing requirements are where many investors find the most difficulty. Tax-loss harvesting is most effective when the market provides opportunities to sell at a loss, which can be unpredictable. You must be nimble and ready to execute trades when your portfolio shows meaningful drops. Tax-gain harvesting, however, is often best executed on a predictable schedule—perhaps annually or during major life transitions—where you have a clear picture of your taxable income for the year. By assessing your income in November or December, you can determine if you have “room” in your current tax bracket to harvest gains without pushing yourself into a higher marginal rate.

    Another layer of complexity involves the interaction between the two. In a given tax year, you might utilize both strategies simultaneously. If you have significant losses from one part of your portfolio, you might use that opportunity to harvest gains from another part without incurring any net tax cost. This is often called “tax-neutral harvesting.” By balancing realized losses against realized gains, you keep your net tax exposure at zero while effectively raising the cost basis of your long-term winners. This is considered the “gold standard” of tax efficiency, as it cleans up your portfolio’s cost basis without the immediate hit to your cash flow caused by tax payments.

    When considering which to prioritize, look to your overall wealth building goals. If your priority is capital preservation during a market correction, tax-loss harvesting takes precedence. If your goal is to consolidate your assets before a major lifestyle change—like moving to a higher tax state or transitioning to a career with much higher compensation—tax-gain harvesting is the superior approach. Ultimately, your strategy should be dynamic. Market conditions change, tax laws evolve, and your personal financial situation will fluctuate. A rigid adherence to one strategy over the other is rarely as effective as an integrated approach that pulls from both toolkits as conditions permit.

    When to Use Tax-Loss Harvesting to Offset Gains

    The decision to trigger tax-loss harvesting should be rooted in a disciplined framework rather than panic. Many investors feel the urge to sell as soon as they see red in their portfolios. However, effective tax-loss harvesting requires you to look beyond the price drop and determine if the underlying investment thesis for that asset remains intact. If the investment is a high-quality asset that has merely suffered from short-term market fluctuation, harvesting the loss and replacing it with a similar asset allows you to maintain exposure while still securing the tax benefit.

    One of the most opportune times to harvest losses is during annual rebalancing. When you review your portfolio at the end of the year, you may find that certain assets have underperformed, throwing your allocation out of balance. By selling these underperformers to rebalance, you naturally create a “tax-loss event” that can be used to offset any capital gains realized from the sale of your overperforming assets. This turns a routine administrative task into a tax-optimizing event.

    Another strategic trigger is when your income changes dramatically. If you have experienced a year with lower-than-average income, you might find yourself in a lower tax bracket than usual. Some investors use this time to harvest not just losses, but also to balance their gains. If you have excess losses, you can apply up to a certain amount against your ordinary income, which provides an immediate cash flow benefit. This is particularly helpful for self-employed individuals or those with fluctuating bonuses who can predict when their “taxable income room” is at its maximum.

    However, you must account for state-level taxes as well. While federal capital gains rules are uniform, state taxes can vary significantly. In some regions, capital gains are taxed as ordinary income, which can be quite steep. In these instances, tax-loss harvesting becomes even more valuable. The total tax savings—the sum of federal and state benefits—can significantly exceed what you might calculate by looking at federal brackets alone. This is where wealth building moves from a generic exercise to a highly personalized, geographic-specific strategy.

    Finally, always perform a cost-benefit analysis before executing trades. Transaction costs, while lower today than in previous decades, still exist, and the time required to manage the trades and track the cost basis is not trivial. If the potential tax savings are negligible compared to the effort or the potential impact on your long-term compounding, it may be better to stay the course. The objective is to enhance long-term wealth, and excessive trading—even with tax benefits in mind—can sometimes lead to “strategy drift,” where your portfolio ends up looking nothing like your original, intended investment plan.

    Strategic Scenarios for Harvesting Long-Term Capital Gains

    Harvesting long-term capital gains is a nuanced activity that rewards the patient investor. Unlike loss harvesting, which is often done under duress, gain harvesting should be executed when you are in control of your financial calendar. One of the most effective scenarios for this is the “bracket management” strategy. Every year, tax brackets are adjusted for inflation, and your personal income will vary. If you can identify a year where your total income is low enough that a portion of your long-term capital gains could be taxed at a zero-percent rate, this is an ideal time to perform a “basis reset.”

    This does not mean you have to divest entirely. You are simply selling and buying back to reset the price at which you bought the asset. By doing this, you essentially “wash” the taxes on those gains, paying zero now to ensure that when you eventually sell the asset for good in the future, you have a much higher cost basis. This is a brilliant move for wealth building because it effectively removes a future tax liability from your books while keeping your market exposure exactly where it was before the sale.

    Another key scenario is when you are planning for a major liquidity event, such as a large purchase, tuition payments, or a business acquisition. If you have been accumulating gains over several years, selling everything in one lump sum in the future could push you into a significantly higher tax bracket, triggering the “alternative minimum tax” or simply a higher marginal rate on capital gains. By harvesting these gains incrementally over several years, you smooth out your tax impact, keeping your realized gains within lower tax bands.

    For investors nearing retirement, tax-gain harvesting becomes a vital component of wealth distribution planning. Many individuals retire with a mix of tax-deferred accounts (like traditional IRAs) and taxable brokerage accounts. During the early years of retirement, before mandatory distributions from tax-deferred accounts kick in, your taxable income may be quite low. This “gap” period is a perfect window to harvest capital gains. By realizing these gains when your tax rate is at its lowest, you are effectively shifting wealth from a taxable environment to a more tax-efficient state, ensuring that your retirement withdrawals do not unnecessarily inflate your tax bill later in life.

    Lastly, consider the scenario of estate planning. In many jurisdictions, assets held at death receive a “step-up” in basis, meaning your heirs inherit the asset at its current market value, effectively eliminating the capital gains tax on the appreciation that occurred during your lifetime. While this makes gain harvesting unnecessary for assets you intend to pass on, it changes the strategy for your lifetime spending. If you have assets that have significant built-in gains, it often makes sense to hold those for your heirs while harvesting gains on assets you intend to use for your own living expenses. This “bifurcated” approach to gain harvesting ensures that you are utilizing every available tax tool to optimize the transfer and consumption of your wealth.

    How to Avoid the Wash-Sale Rule During Tax Optimization

    One of the most critical barriers to effective tax-loss harvesting is the Internal Revenue Service (IRS) “wash-sale rule.” This regulation is designed to prevent investors from selling a security at a loss purely to claim a tax benefit, only to immediately repurchase the same or a “substantially identical” security to maintain their market position. If you violate this rule, the IRS will disallow the tax loss, effectively neutralizing your tax-planning efforts.

    The wash-sale window is defined as 30 days before and 30 days after the date of the sale that generated the loss—a total 61-day window. If you purchase a substantially identical security within this timeframe, the loss is deferred and added to the cost basis of the new position. While this doesn’t mean the loss is gone forever, it does mean you cannot claim it on your taxes for the current year, which defeats the immediate purpose of your tax-loss harvesting strategy.

    To navigate this complex landscape, investors often utilize the “substantially similar” loophole. While the IRS has not provided an exhaustive list of what qualifies as “substantially identical,” the consensus among tax experts is that buying a different fund that tracks a similar, but not identical, index is generally acceptable. For example, if you sell an ETF tracking the S&P 500 at a loss, you might consider buying an ETF that tracks a broader total market index or a different S&P 500 fund offered by a different provider. These funds are considered distinct enough that they are not typically classified as substantially identical by tax authorities.

    Another way to avoid the rule is to simply wait out the 31-day period before repurchasing. However, this carries “market risk”—the possibility that the asset will significantly appreciate in value while you are sitting on the sidelines. For long-term wealth building, the best practice is to maintain a pre-planned list of “replacement assets” that align with your broader asset allocation goals. By swapping into a similar asset, you can capture your tax benefit while keeping your portfolio fully invested in the market, ensuring that your wealth strategy remains intact even when you are aggressively pursuing tax efficiency.

    Balancing Harvesting Strategies With Your Long-Term Goals

    Tax optimization is a powerful tool, but it should never be the “tail that wags the dog.” Your primary objective in wealth building is to reach your long-term financial milestones, such as retirement or major life transitions. If you find yourself frequently triggering transactions just to capture small tax savings, you may be falling into the trap of over-trading. Transaction costs, bid-ask spreads, and the risk of deviating from your target asset allocation can quickly erode any gains achieved through tax-loss or tax-gain harvesting.

    The key is to integrate these harvesting strategies into a holistic investment policy statement. For instance, tax-gain harvesting is most effective when your income is temporarily low, potentially allowing you to trigger gains at a zero percent long-term capital gains tax rate. If you harvest gains simply because an asset has performed well, you might inadvertently push yourself into a higher tax bracket or trigger the Net Investment Income Tax (NIIT), which would negate your long-term efficiency goals.

    Furthermore, tax-loss harvesting should be viewed as a way to enhance your long-term compounding, not as a shortcut to portfolio growth. By lowering your current tax bill, you have more capital to reinvest, which creates a “tax alpha”—the extra return generated by managing taxes effectively. However, if your harvesting leads you to hold assets that no longer align with your risk tolerance or financial goals, the costs will eventually outweigh the benefits.

    Consider the following comparison table to help you decide which strategy is more appropriate for your current financial situation:

    Strategy Primary Benefit Best For Risk Factor
    Tax-Loss Harvesting Reduces current taxable income Investors with high income and unrealized losses Wash-sale rule violations
    Tax-Gain Harvesting Resets cost basis to current market value Investors in lower tax brackets or those anticipating future tax hikes Paying immediate taxes you could have deferred
    Portfolio Rebalancing Aligns risk with long-term goals All investors maintaining a target allocation Tax friction from selling winners

    Tax-Efficient Portfolio Management for Year-Round Wealth

    Building wealth through tax efficiency is not an end-of-year activity; it is a year-round discipline. Investors who treat tax planning as a constant process often experience higher net returns over the long term. This approach involves “asset location,” which refers to placing different types of investments in the accounts where they are taxed most efficiently. For example, high-dividend stocks or REITs, which generate ordinary income, are often better suited for tax-deferred accounts like IRAs, whereas tax-efficient index funds that generate primarily long-term capital gains are better suited for taxable brokerage accounts.

    Year-round management also involves monitoring your dividend reinvestment settings. When dividends are reinvested automatically, they purchase fractional shares. If you are harvesting tax losses, you must be careful that your dividend reinvestment doesn’t trigger a wash sale. Many professional investors choose to disable automatic dividend reinvestment in accounts where they are actively harvesting losses, opting instead to manually reinvest those dividends once the 31-day window has cleared.

    Finally, consider the role of tax-loss harvesting in your asset allocation. If you are selling an underperforming asset to realize a loss, you should already have a plan for how that capital will be redeployed. Having cash sitting in a settlement fund for too long can result in “cash drag,” where your overall portfolio performance lags because a portion of your capital is not exposed to market growth. Always ensure that your “tax-efficient” moves are keeping you on track to meet your wealth-building targets.

    How to Track Your Capital Gains and Losses Effectively

    One of the most common mistakes individuals make is relying solely on the tax documents provided by their brokerage firms. While these forms (such as the 1099-B) are essential, they do not always provide the full picture of your tax-planning activities, especially if you hold assets across multiple brokerage platforms. Keeping an independent, detailed ledger of your transactions is vital for ensuring accurate reporting.

    To track your capital gains and losses effectively, you should maintain a digital spreadsheet or use dedicated portfolio management software that categorizes each trade by date, amount, and the specific asset class. This ledger should be updated every time a transaction occurs. Pay close attention to your “cost basis.” The IRS generally allows you to choose your cost basis method—such as “Average Cost” for mutual funds or “Specific Identification” for individual stocks. Specific identification is often the preferred choice for sophisticated investors, as it allows you to choose which specific shares to sell, thereby maximizing your tax efficiency by realizing the specific losses or gains that benefit your current tax situation.

    Furthermore, ensure that you are tracking your “carryover losses.” If your total capital losses exceed your capital gains in a given year, you can use up to $3,000 of the excess loss to offset your ordinary income. Any remaining loss can be carried forward indefinitely into future tax years. Many investors forget about these carryover losses, failing to use them against gains in subsequent years. A robust tracking system will ensure that you never let these valuable tax assets go to waste, allowing you to systematically reduce your tax burden as you continue to build your wealth.

    Frequently Asked Questions

    Is tax-loss harvesting worth it for small portfolios?

    While the administrative effort is the same regardless of portfolio size, the benefits of tax-loss harvesting are typically magnified as the portfolio grows. However, even for smaller accounts, developing the habit of tax-aware investing early can provide significant long-term advantages. The real question is whether the time spent managing the losses outweighs the potential tax savings; for many, automation through robo-advisors has made this accessible even for modest portfolios.

    Can I harvest losses in a tax-advantaged account like an IRA or 401(k)?

    No. Tax-loss harvesting is only applicable to taxable brokerage accounts. Because investments within IRAs, 401(k)s, and other tax-advantaged accounts are not taxed on an annual basis, there is no capital gain or loss to report to the IRS. Trying to harvest a loss in these accounts provides no immediate tax benefit and is generally not possible because you cannot claim losses on your tax return for these assets.

    What is the “30-day rule” in simple terms?

    The “30-day rule” (often referred to as the wash-sale rule) dictates that if you sell a security at a loss, you cannot buy it back—or a “substantially identical” security—within 30 days before or after the date of the sale. If you do, the IRS prevents you from claiming that loss on your current tax return, and the loss is added to the cost basis of the new shares instead.

    What exactly does the IRS consider “substantially identical”?

    The IRS does not provide a strict definition of “substantially identical,” which creates some ambiguity. However, most experts agree that selling an ETF that tracks one index and buying an ETF that tracks a completely different index is safe. The rule is generally intended to stop you from selling a stock and buying the exact same stock immediately after, just to manufacture a paper loss for tax purposes.

    How does capital gains tax differ from ordinary income tax?

    Ordinary income, such as wages or interest, is typically taxed at higher progressive rates. Long-term capital gains, which apply to assets held for more than one year, are taxed at preferential, lower rates. Tax-loss harvesting is a strategy used to offset these capital gains, potentially reducing your total tax liability and allowing more of your investment returns to remain in the market to compound over time.

    Should I prioritize tax-gain harvesting over tax-loss harvesting?

    It depends on your current tax bracket. Tax-loss harvesting is almost always beneficial for investors in high tax brackets to reduce their immediate tax liability. Tax-gain harvesting is a more strategic tool typically used by those in lower tax brackets who can reset their cost basis to a higher amount, effectively paying little to no tax now to avoid higher taxes when they sell those assets in the future.

    Conclusion

    Mastering the nuances of tax-loss and tax-gain harvesting is a cornerstone of modern wealth building. By understanding the interaction between market volatility, the wash-sale rule, and your individual tax situation, you can transform your portfolio into a tax-efficient engine for growth. Remember, the goal is not merely to avoid taxes today, but to maximize your after-tax wealth over the long horizon. Stay disciplined, track your basis accurately, and ensure that every tax-planning move you make is in service of your broader financial objectives.

    Ready to take control of your financial future? Start by auditing your current portfolio for unrealized losses and gains, and speak with a qualified tax professional to create a strategy that fits your unique goals. Your path to greater wealth begins with being smarter about the taxes you pay.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
  • How to Calculate Your FIRE Number: The Guide to Financial Freedom

    How to Calculate Your FIRE Number: The Guide to Financial Freedom

    Key Takeaways

    • Your FIRE number represents the total investment capital required to sustain your lifestyle indefinitely without traditional employment.
    • The foundation of most FIRE calculations is the 4% rule, which estimates how much you can safely withdraw annually from a diversified portfolio.
    • Accurate retirement planning requires a deep understanding of your current annual expenses, adjusted for future lifestyle shifts and inflation.
    • Health insurance and medical costs often represent the most significant “hidden” variables when calculating your early retirement needs.
    • Wealth building is not just about saving; it is about optimizing your net savings rate and maximizing the power of compound investment growth over time.

    The journey toward financial independence represents one of the most transformative shifts a person can make in their relationship with money. For many, the FIRE movement—Financial Independence, Retire Early—is not merely about quitting a job; it is about reclaiming autonomy over one’s time and resources. Central to this objective is the FIRE number, a specific monetary target that acts as your personal “finish line.” By utilizing a reliable FIRE number calculator, you transition from vague hopes of “having enough” to a precise, actionable roadmap for wealth building. This guide serves as an authoritative resource for those ready to master the math behind their freedom and secure a sustainable future through deliberate, data-driven retirement planning.

    What Is the FIRE Number and Why Does It Matter?

    At its core, the FIRE number is the total amount of invested assets you need to accumulate to support your desired lifestyle without the need for active labor. It is the bridge between your current career-focused life and a future defined by choice. When you are searching for how to calculate your FIRE number, you are essentially seeking to solve a specific equation: determining the capital required to generate passive income that covers 100% of your annual living expenses. Understanding this number is the most critical step in early retirement because it removes the guesswork from your long-term strategy.

    The importance of this calculation cannot be overstated. Without a clear target, individuals often fall into the trap of over-saving—delaying their freedom unnecessarily—or under-saving, which risks portfolio exhaustion during retirement. By establishing a definitive wealth target, you gain psychological comfort and tactical clarity. It allows you to visualize exactly how much capital needs to be deployed in wealth-generating vehicles like index funds, real estate, or dividend-producing assets. Furthermore, knowing your FIRE number transforms every financial decision into an efficiency exercise. Should you spend $50 on a luxury item today, or would that $50 contribute more to your freedom if invested at a 7% annual return? This mindset is the bedrock of the FIRE movement.

    A common misconception is that the FIRE number is a static, unchanging figure. In reality, it is a living projection. As your lifestyle needs evolve or as market conditions shift, your target may fluctuate. However, having a baseline allows you to calibrate your progress. Whether you are aiming for Lean FIRE (a minimalist approach), Fat FIRE (a luxurious lifestyle), or Coast FIRE (where your investments grow to your goal without further contributions), the fundamental goal remains the same: accumulating a portfolio large enough that the withdrawal rate does not outpace the growth of the underlying assets. This authoritative clarity is what separates those who dream of early retirement from those who systematically achieve it.

    Beyond the raw math, the FIRE number matters because it fosters a sense of purpose. It turns the nebulous concept of “getting rich” into a structured project. When you know your target, you can track your progress as a percentage. Seeing that you have achieved 25%, 50%, or 75% of your total requirement provides a powerful intrinsic reward that encourages continued discipline. For many, this calculation is the most effective antidote to lifestyle creep; once you see the direct correlation between your spending and the distance to your retirement goal, you are often naturally inclined to optimize your expenditures.

    Understanding the 4% Rule for Sustainable Withdrawals

    The 4% rule is arguably the most cited principle in modern retirement planning. Emerging from decades of financial research—most notably the seminal study conducted by William Bengen—this rule suggests that you can withdraw 4% of your total portfolio in the first year of retirement, then adjust that dollar amount annually for inflation, with a high degree of confidence that your money will last for at least 30 years. To use this to find your FIRE number, the math is simple: multiply your desired annual expenses by 25. For example, if you need $50,000 per year, your FIRE number would be $1,250,000.

    While the 4% rule is an excellent starting point, experts generally advise viewing it as a guideline rather than a law. The rule was originally back-tested against historical stock and bond market data, meaning its effectiveness is contingent upon having a well-diversified portfolio that captures market growth. If your assets are sitting in low-yield vehicles or if you are overly concentrated in a single sector, the 4% withdrawal rate might be too aggressive. Conversely, if you have a flexible lifestyle, you might find that you can safely retire on even less by practicing “variable withdrawals”—reducing your spending during years when the market performs poorly.

    It is important to note that the 4% rule is typically intended for a traditional 30-year retirement window. Because the FIRE movement often involves early retirement—meaning a retirement that could span 40, 50, or even 60 years—many practitioners prefer to be more conservative. Some choose a “Safe Withdrawal Rate” (SWR) of 3% or 3.5%. This adjustment increases the size of the required nest egg but significantly lowers the risk of running out of money during a prolonged period of market volatility. Wealth building is as much about risk management as it is about total accumulation.

    Withdrawal Strategy Logic Best For
    4% Rule (Traditional) Standard multiplier of 25x annual expenses. Standard 30-year retirement planning.
    3.25% Rule (Conservative) Multiplier of ~30x annual expenses. Early retirees seeking maximum longevity.
    Flexible Withdrawal Adjusting spending based on market performance. Those with adaptable, low-stress lifestyles.

    To implement this, start by looking at your current asset allocation. A portfolio consisting of a mix of low-cost broad market index funds and fixed-income assets provides the balance necessary to withstand the ups and downs of the market. As you approach your FIRE number, you may consider a “bond tent” strategy—temporarily increasing your allocation to safer assets in the years immediately surrounding your retirement to mitigate sequence-of-returns risk. This approach ensures that your portfolio remains a resilient engine for wealth creation throughout your entire life.

    How to Estimate Your Annual Retirement Expenses

    Calculating your FIRE number is futile if your expense projection is inaccurate. Many beginners make the mistake of using their current annual income as a proxy for retirement expenses. However, your spending habits will likely change drastically once you leave the workforce. You must conduct a thorough audit of your current cash flow to establish a realistic baseline, then modify it to reflect your post-career reality. Start by categorizing expenses into “essential” (housing, food, utilities, insurance) and “discretionary” (travel, dining out, hobbies).

    To estimate your retirement budget, first list every expense from the past 12 months. Tools such as budgeting apps or spreadsheet trackers are invaluable here. Once you have a total, subtract the costs associated specifically with employment, such as commuting, professional attire, and work-related lunches. These are immediate savings you will realize upon retirement. Next, add back in the costs that might increase once you have more free time. For many, this includes travel, memberships, and increased utility usage at home. If you plan to downsize your home or pay off your mortgage before retiring, be sure to account for those significant changes in your overhead.

    Remember to consider the “phases” of early retirement. In the early years, you might be more active and spend more on experiences and travel. As you enter later stages, your lifestyle may shift toward more sedate activities. Some retirees create a “three-bucket” budget: base living expenses, “go-go” years travel funds, and a buffer for unexpected costs. This level of detail is necessary to ensure your FIRE number remains robust under various life scenarios. Furthermore, consider if your current location is where you intend to remain. If you plan to move to a location with a lower cost of living, your FIRE number will decrease significantly, potentially accelerating your timeline by several years.

    Finally, avoid the temptation to underestimate. It is better to overestimate your expenses by a comfortable margin—perhaps 10% to 15%—as a “safety buffer.” This buffer serves as your defense against unexpected economic shocks or personal emergencies. When you are determining how to calculate your FIRE number, accuracy in this estimation phase is more important than almost any other variable. Treat this data collection process with the same level of seriousness you would afford a professional business audit. After all, you are building the business of your own life, and the figures you use today will dictate the comfort of your freedom tomorrow.

    Factoring in Inflation and Healthcare Costs

    Inflation is the silent anchor that drags down the purchasing power of your wealth over time. If your FIRE number is $1,000,000 today, that same million dollars will not buy the same amount of goods and services in twenty years. To calculate a truly sustainable FIRE number, you must account for the effects of long-term inflation. While average annual inflation rates vary, experts often suggest using a conservative historical average, such as 3%, when projecting the future cost of your lifestyle. This ensures that your portfolio growth keeps pace with the rising costs of basic necessities like food, housing, and energy.

    Healthcare costs represent the most significant variable that can derail an otherwise sound retirement plan. Unlike other expenses that may decrease as you age, medical costs typically rise. If you are retiring before you are eligible for national healthcare programs or senior subsidies, you must factor in the full cost of private insurance premiums, co-pays, and out-of-pocket expenses. This is often the most expensive line item for early retirees. Research current market rates for high-deductible health plans in your region, and remember to include an annual increase for these costs, as healthcare inflation has historically outpaced general consumer price inflation.

    To mitigate these risks, many in the FIRE movement build a “healthcare bridge” into their plans—a separate, liquid fund specifically designated to cover premiums and out-of-pocket medical costs until they reach the age of government-subsidized retirement benefits. By isolating these funds, you gain a clearer picture of your retirement sustainability. You might also explore options like Health Savings Accounts (HSAs), which offer triple-tax advantages and serve as a powerful tool for building wealth specifically for medical expenses. An HSA is essentially a long-term investment vehicle that can drastically reduce the tax burden associated with your retirement healthcare needs.

    In addition to these costs, always maintain an “inflation-adjusted” mindset. As your investments grow, the dollar amount of your portfolio will rise, which helps fight the dilution of purchasing power. However, it is vital that your withdrawal strategy also incorporates inflation adjustments. When the cost of living rises by 3% in a given year, your annual withdrawal from your portfolio should ideally increase by 3% to maintain your standard of living. By failing to account for this, you risk slowly sliding into a lower quality of life as your purchasing power erodes. Integrating inflation and healthcare into your FIRE math is not just about protection; it is about building a foundation that is resilient enough to endure any economic climate.

    Calculating Your Net Savings Rate and Investment Growth

    The speed at which you reach your FIRE number is almost entirely dependent on your net savings rate. Your savings rate is defined as the percentage of your take-home pay that you invest after all expenses are covered. A savings rate of 10% might allow for a comfortable traditional retirement, but the FIRE movement typically requires a much more aggressive approach. By pushing your savings rate to 30%, 50%, or even 70%, you achieve two powerful effects simultaneously: you reduce your total annual expenses (thereby lowering your required FIRE number) and you increase the amount of capital available for wealth building (thereby reaching your number faster).

    To maximize your progress, you must master the mechanics of compound interest. When your money is invested, it generates returns, and in the following period, you earn returns on those returns. This compounding effect is the true engine of wealth. To calculate your growth, you need to estimate your expected annual rate of return. While historical stock market averages are often cited in the 7% to 10% range (before inflation), a more conservative projection of 5% to 6% is often preferred by those who want to be certain their plan remains viable during lean market years. Use an online compound interest calculator to see how different savings rates and interest rate assumptions affect the duration of your journey.

    Asset allocation is the primary driver of these returns. A portfolio heavily weighted in cash or low-interest savings accounts will struggle to keep up with inflation, let alone compound sufficiently to retire early. Most FIRE enthusiasts focus on low-cost, broad-based equity index funds. These vehicles provide exposure to the growth of the overall economy while keeping management fees to an absolute minimum. By automating your investments—setting up recurring monthly contributions that execute regardless of market conditions—you remove emotional bias from the equation and ensure that your wealth-building engine is always running.

    It is also essential to track your “net worth” rather than just your “savings.” Net worth is the total value of all your assets minus your liabilities. As you pay down debt, your net worth increases, and as your assets grow, your net worth increases. Watching this number rise provides a visual representation of your progress toward your FIRE number. Do not be discouraged by periods of market stagnation; wealth building is a marathon, not a sprint. The discipline required to maintain a high savings rate during periods of economic uncertainty is what distinguishes successful retirees from those who quit halfway. By remaining committed to your contributions and focusing on the long-term compounding of your assets, you will eventually reach the tipping point where your passive income covers your living expenses, granting you the ultimate freedom: the choice of how to spend your time.

    Accounting for Social Security and Pension Income

    When you sit down to calculate your FIRE number, the standard 4% rule provides a foundational baseline by assuming your portfolio must cover 100% of your expenses. However, for many people, retirement is not solely funded by private investments. Government-backed retirement benefits and employer-sponsored pensions play a crucial role in wealth building and can significantly reduce the pressure on your personal portfolio.

    To accurately integrate these income streams, you must first determine if you are pursuing “Lean FIRE,” “Coast FIRE,” or “Fat FIRE,” as the timing of your benefit payouts is fixed. Social Security benefits, for instance, typically cannot be claimed until you reach a specific age, often 62 or later. If you plan to retire at 40, you will have a multi-decade gap where you must rely entirely on your investments. Therefore, you should calculate two separate FIRE numbers: one for the “gap years” and one for the years following the start of your pension or Social Security benefits.

    To perform this calculation, subtract your expected annual benefit amount from your projected annual expenses. If your living costs are $50,000 and you expect $15,000 from a pension, your portfolio only needs to generate $35,000 per year. Using the 4% rule, you would multiply this $35,000 by 25 to arrive at your adjusted goal. Remember, however, that these benefits are subject to legislative changes and potential inflation adjustments. Many experts suggest treating these sources as a “margin of safety” rather than a guaranteed foundation to ensure your wealth remains resilient against unforeseen economic shifts.

    Adjusting Your FIRE Number for Different Retirement Lifestyles

    The FIRE movement is not a one-size-fits-all strategy. Your FIRE number is a reflection of your desired lifestyle, and adjusting that number requires an honest assessment of your values and future goals. A minimalist lifestyle, often associated with Lean FIRE, focuses on extreme frugality and low overhead, while Fat FIRE assumes a lifestyle that includes luxury travel, frequent dining out, and higher healthcare allocations.

    Consider the following lifestyle adjustments when refining your calculation:

    • Location-Independent Lifestyles: If you plan to engage in geo-arbitrage—living in a country with a lower cost of living—your annual expenses will drop, allowing you to reduce your FIRE number significantly.
    • Healthcare Costs: This is often the most volatile variable in retirement planning. If you retire before you are eligible for government-sponsored health programs, your annual expense calculation must include the full cost of private insurance premiums and out-of-pocket medical expenditures.
    • Geographic Variability: Moving from a high-tax state to a low-tax or no-tax jurisdiction can change your “number” by tens of thousands of dollars per year.

    The following table compares different FIRE strategies to help you align your personal wealth goals with your lifestyle expectations.

    FIRE Strategy Primary Characteristic Lifestyle Focus Best For
    Lean FIRE Extreme frugality Minimalist, low-cost living Those prioritizing speed and independence
    Fat FIRE High-budget planning Comfort, travel, and luxury Those prioritizing quality of life over speed
    Coast FIRE Partial wealth buildup Covering immediate needs only Younger earners who let time compound interest
    Barista FIRE Part-time work Active lifestyle with supplementary income Those who want to stay busy while semi-retired

    The Role of Asset Allocation in Maintaining Your FIRE Number

    Calculating your FIRE number is merely the first step; maintaining that number requires a disciplined approach to asset allocation. Your retirement is not a static event but a multi-decade journey through various market cycles. If your investments are too conservative, inflation may erode your purchasing power; if they are too aggressive, a market downturn early in your retirement—a phenomenon known as “sequence of returns risk”—could deplete your portfolio prematurely.

    To preserve your wealth, many financial experts recommend a balanced portfolio that includes a mix of equities for growth and fixed-income assets (like bonds or cash equivalents) for stability. A common strategy is to keep one to two years of living expenses in cash or highly liquid assets. This “cash cushion” ensures that if the stock market experiences a temporary dip, you are not forced to sell your investments at a loss to cover your immediate bills.

    Furthermore, asset location is just as important as asset allocation. By holding tax-inefficient assets—such as high-yield bonds—in tax-advantaged accounts and growth-oriented equities in taxable accounts, you can improve your after-tax returns. This optimization helps keep your FIRE number achievable by ensuring that you do not lose a larger-than-necessary portion of your gains to taxes.

    Common Mistakes When Calculating Your Retirement Goal

    Even the most diligent planners often fall prey to cognitive biases or mathematical oversights when calculating their FIRE number. Avoiding these pitfalls is essential for a secure transition into early retirement.

    1. Underestimating Inflation: People often calculate expenses based on current prices. However, a dollar today will not purchase the same amount of goods in 20 years. Always use inflation-adjusted figures in your projections.
    2. Ignoring Lifestyle Creep: As your income grows, your standard of living often rises alongside it. If you build your FIRE number based on your current spending but your habits change, your plan will fail.
    3. Forgetting “Lumpy” Expenses: Annual expense calculations often focus on recurring costs like rent, groceries, and utilities. They frequently miss irregular but inevitable costs like home repairs, car replacements, or major medical procedures. Build a buffer into your annual expense total to account for these.
    4. Over-reliance on Historical Returns: While the market has historically performed well, past performance does not guarantee future results. It is safer to use conservative estimates for your portfolio’s annual return rather than aggressive historical averages.

    How to Track Your Progress Toward Your FIRE Number

    Tracking your progress is perhaps the most motivating aspect of the FIRE journey. It transforms an abstract, daunting figure into a series of achievable milestones. To track effectively, you need more than just a spreadsheet; you need a system of accountability.

    Start by calculating your “Savings Rate,” which is the percentage of your take-home pay that goes toward your investments. A high savings rate is the most powerful lever you have for reaching your FIRE number quickly. Monitor this monthly, and look for opportunities to increase it by either boosting your income or optimizing your expenses.

    Next, implement a quarterly “Net Worth Review.” Unlike a monthly budget check, a net worth review looks at your total assets (cash, investments, home equity) minus your total liabilities (mortgages, student loans, consumer debt). As your net worth grows, your distance to your FIRE number decreases. Seeing that progress mapped out on a line graph can be the difference between staying the course or burning out when the work gets difficult.

    Finally, use technology to your advantage. There are many automated tools, budget tracking apps, and financial dashboards available that aggregate your accounts in one place. By reducing the friction involved in tracking your data, you are more likely to remain consistent over the long term.

    Frequently Asked Questions

    What is the 4% rule and is it still relevant today?

    The 4% rule is a guideline suggesting that you can safely withdraw 4% of your initial portfolio balance in your first year of retirement, then adjust that amount for inflation annually, without running out of money for at least 30 years. While it remains a popular starting point, many experts suggest that in today’s volatile market environment, a more conservative 3% or 3.5% withdrawal rate may provide better protection for a multi-decade early retirement.

    How do I calculate my FIRE number if I have a lot of debt?

    Generally, you should factor your debt payments into your total annual expenses until they are paid off. However, the most effective path to FIRE usually involves eliminating high-interest consumer debt before prioritizing long-term investments. Once the debt is cleared, you can redirect those monthly payments directly into your investment portfolio, which significantly accelerates your wealth-building timeline.

    Does my home equity count toward my FIRE number?

    Including home equity in your FIRE number is a personal choice, but it is often cautioned against by financial planners. Because your home is where you live, you cannot easily “withdraw” the equity to cover daily living expenses without selling the property or taking on a reverse mortgage. It is safer to consider your FIRE number based solely on liquid, income-generating assets.

    What happens if the market crashes right after I retire?

    This is known as “sequence of returns risk.” To mitigate this, many early retirees maintain a “bond tent” or a cash buffer of two to three years of living expenses. This allows you to avoid selling stocks during a market downturn, giving your portfolio the necessary time to recover without impacting your lifestyle.

    How often should I recalculate my FIRE number?

    Life circumstances change, and so should your plan. Most people find that conducting a deep-dive review of their FIRE number once a year is sufficient, or whenever a major life event occurs, such as a career change, marriage, the birth of a child, or a significant change in geographic location.

    Can I achieve FIRE on an average salary?

    Yes, achieving FIRE is possible on an average salary, though it may take longer. The speed at which you reach financial independence is primarily determined by your savings rate rather than your total income. By practicing intentional spending and investing the difference consistently over time, anyone can build a path toward financial independence.

    Conclusion

    Calculating your FIRE number is a transformative step that shifts your perspective from working for money to making your money work for you. By carefully assessing your annual expenses, accounting for future income streams, and remaining disciplined in your asset allocation, you create a roadmap to a life defined by freedom rather than obligation. Whether you choose a path of aggressive wealth building or a more balanced approach, the clarity provided by these calculations serves as your compass. Remember that the journey toward financial independence is a marathon, not a sprint—consistency and adaptability are your greatest allies. Take your first step today by auditing your current expenses, setting a preliminary target, and automating your investments. The life you envision is closer than you think.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
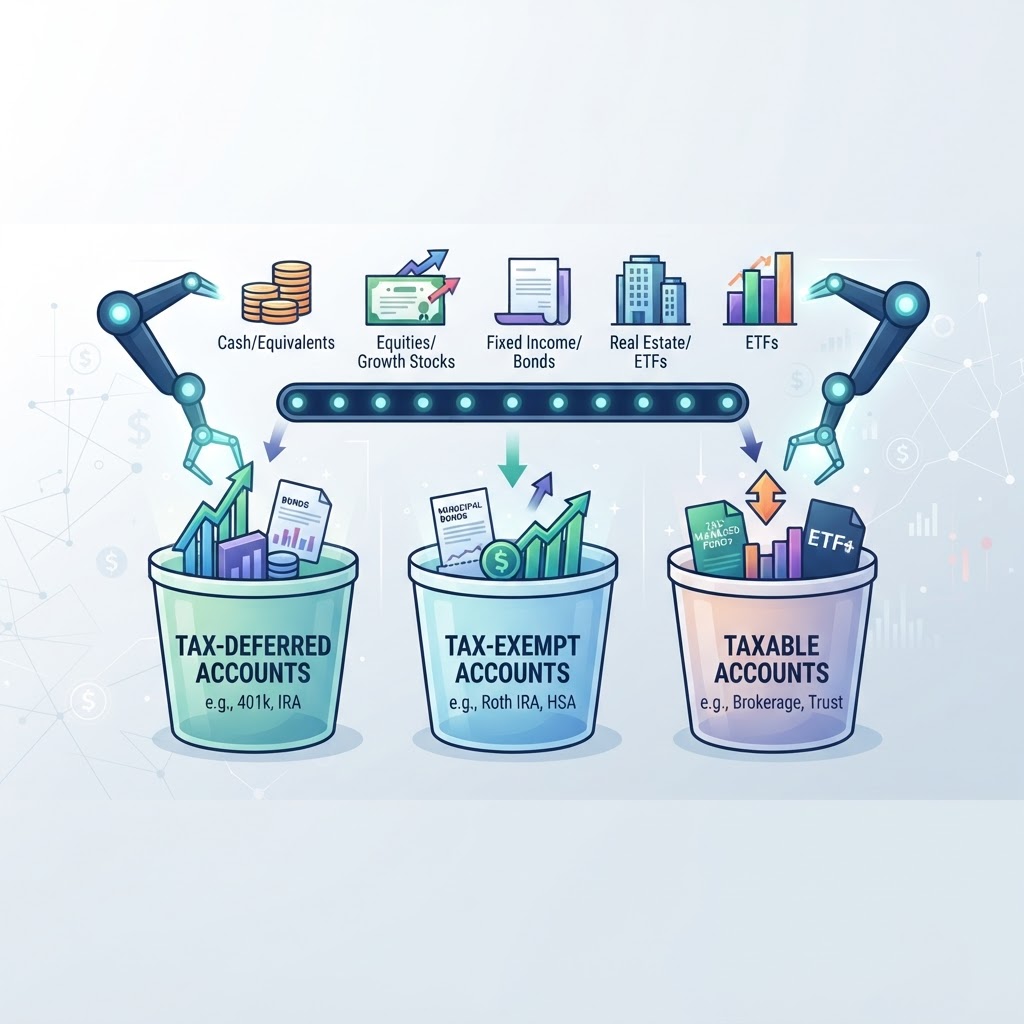
  • Tax-Gain Harvesting: When to Use It to Boost Your Wealth

    Tax-Gain Harvesting: When to Use It to Boost Your Wealth

    Key Takeaways

    • Tax-gain harvesting is a proactive strategy to reset your cost basis by selling profitable assets and immediately repurchasing them to manage future tax liabilities.
    • Unlike tax-loss harvesting, which offsets gains to lower your current bill, tax-gain harvesting focuses on utilizing low-income years to lock in preferential tax rates.
    • Understanding your specific capital gains tax bracket is essential for determining if triggering a tax event will actually save you money in the long run.
    • Resetting your cost basis can significantly reduce the wealth-eroding impact of capital gains taxes over a multi-decade investment horizon.
    • This strategy is most effective for investors in lower tax brackets who can benefit from the 0% long-term capital gains rate.

    For many investors, the word “taxes” often triggers a defensive posture, leading to a “set it and forget it” mentality that ignores the massive impact of investment tax management on long-term wealth building. While most people are familiar with the concept of harvesting losses to lower their annual tax burden, far fewer are aware of the inverse strategy: tax-gain harvesting. By intentionally triggering gains during years where your income is lower than usual, you can essentially reset your cost basis and prepare your portfolio for greater efficiency in the future. This approach is a sophisticated tool for those who view wealth creation not just as a matter of picking the right stocks, but as a discipline of structural optimization. In this guide, the wealthsimplyput editorial team explores how you can leverage these techniques to maximize your net returns and keep more of your hard-earned money working for you.

    What Is Tax-Gain Harvesting and How Does It Work?

    At its core, tax-gain harvesting is a financial planning strategy where an investor intentionally sells an investment that has appreciated in value to realize a capital gain, only to immediately repurchase the same or a substantially similar asset. On the surface, this might seem counterintuitive—why would you voluntarily create a taxable event? The answer lies in the nuance of how capital gains are taxed. In many jurisdictions, including the United States, long-term capital gains are taxed at preferential rates compared to ordinary income. Furthermore, there are often “zero percent” tax brackets for long-term capital gains for individuals with lower taxable income levels.

    The primary mechanism of tax-gain harvesting involves “stepping up” your cost basis. Imagine you purchased an asset for $10,000, and over several years, it grew to be worth $20,000. If you were to sell it later when your income has risen significantly, you might be subject to a much higher capital gains tax rate on that $10,000 profit. However, by harvesting that gain during a year where your total income is low—perhaps during a sabbatical, a period of unemployment, or early retirement—you might be able to pay 0% tax on those gains. By selling and immediately rebuying at the $20,000 mark, your new cost basis becomes $20,000. If that asset then grows to $30,000 over the next decade, you have effectively eliminated the tax liability on the first $10,000 of profit forever.

    This strategy requires a disciplined approach to portfolio monitoring. It is not about timing the market in terms of “buying low and selling high,” but rather “timing the tax code.” Investors must be mindful of the “wash-sale rule” when it comes to losses, but it is important to note that the wash-sale rule does not apply to gains. You can sell an asset for a gain and buy it back immediately without violating any tax regulations. This makes tax-gain harvesting a safe and legal way to manufacture a higher cost basis. The goal is to move as much of your portfolio’s growth as possible into a tax-advantaged state, effectively smoothing out your tax liability over a long investment horizon. For those focused on long-term wealth building, this maneuver is less about immediate cash flow and more about preventing future tax friction that could otherwise drag down your compounding returns.

    Tax-Gain Harvesting vs Tax-Loss Harvesting: Key Differences

    Distinguishing between tax-gain harvesting and tax-loss harvesting is essential for effective tax management. While both strategies fall under the umbrella of proactive tax planning, they serve fundamentally different purposes and are utilized under different economic conditions. Tax-loss harvesting is widely recognized as the practice of selling investments at a loss to offset gains realized elsewhere in your portfolio, or to offset up to a specific amount of ordinary income annually. It is a defensive maneuver used to minimize current tax liability, often during market downturns.

    In contrast, tax-gain harvesting is an offensive, opportunistic strategy. Rather than looking for ways to cover up bad investment performance, you are seeking to capitalize on good performance when the tax environment is favorable to you. Below is a comparison to help clarify when each approach might be most appropriate for your personal financial situation.

    Strategy Primary Goal Market Context Best For
    Tax-Loss Harvesting Reduce current tax burden During market corrections or declines Investors wanting to lower current-year tax bills
    Tax-Gain Harvesting Reset cost basis for future tax savings During low-income years or stagnant markets Wealth builders looking to optimize long-term tax drag

    Understanding the interplay between these two is critical. If you perform both in a single tax year, the gains and losses will naturally net out, which might be exactly what you want if you have excess capital gains from a forced sale or a merger. However, to maximize the benefits of tax-gain harvesting, you generally want to trigger the gains in years where you have little to no other capital gains to offset them, allowing you to stay within that beneficial low-tax threshold. While tax-loss harvesting is about “saving pennies today,” tax-gain harvesting is about “protecting dollars tomorrow.” By strategically alternating or combining these methods based on your evolving income level and market conditions, you create a dynamic tax management plan that evolves alongside your wealth.

    Understanding Capital Gains Tax Brackets for 2026

    To execute tax-gain harvesting effectively, one must have a granular understanding of how capital gains tax brackets operate. In the United States, federal tax law categorizes capital gains based on the length of time you have held an asset. Assets held for one year or less are subject to short-term capital gains tax, which is typically taxed at the same rate as your ordinary income—often a significantly higher rate. Long-term capital gains, which apply to assets held for more than a year, benefit from lower preferential tax rates.

    For the 2026 tax year, the brackets for long-term capital gains are indexed to income levels, typically falling into 0%, 15%, or 20% categories, potentially with an additional net investment income tax (NIIT) for higher earners. The “sweet spot” for tax-gain harvesting is almost exclusively within the 0% bracket. If your taxable income is low enough to fall into the range where long-term capital gains are taxed at 0%, any gains you harvest are essentially tax-free at the federal level. This creates a powerful window of opportunity to reset your cost basis without incurring a cash outflow for taxes.

    It is important to remember that these brackets are inclusive of all your income, not just your investment returns. When you sell an asset to harvest a gain, that gain counts as income. If you sell too much, you might inadvertently push yourself into the 15% bracket, which would turn a “tax-free” harvest into a 15% tax event. This requires careful mathematical planning. Before triggering a sale, an investor should calculate their projected total taxable income for the year, including salary, dividends, interest, and the proposed capital gain. By staying just below the threshold where the 15% rate kicks in, you can maximize the amount of gain harvested at the 0% rate. Experts often suggest reviewing these brackets annually, as tax laws and inflation adjustments can shift these thresholds, potentially narrowing or expanding your harvesting window. Staying informed about these thresholds is a hallmark of sophisticated financial planning.

    The Strategic Benefit of Resetting Your Cost Basis

    The “cost basis” of an investment is essentially its tax “starting line.” It represents the price you paid for an asset plus any relevant commissions or fees. When you sell an investment, the tax you owe is calculated based on the difference between the selling price and the cost basis. Over a lifetime of wealth building, failing to manage your cost basis can lead to a “tax bomb” when you eventually need to liquidate significant portions of your portfolio, perhaps for major purchases or retirement spending.

    Resetting your cost basis through tax-gain harvesting acts as a preventative maintenance measure for your wealth. Consider an investor who holds a significant position in a high-growth index fund. Over twenty years, the unrealized gains could be enormous. If they wait until they are in a high-income phase of their career to sell, the tax bill could consume a substantial percentage of their total returns. By systematically harvesting gains in years where they have lower taxable income, they “wash” the unrealized growth into a new, higher cost basis. This essentially means they have paid the tax (or avoided it via the 0% bracket) as they go, rather than deferring the entire liability to a future date when their tax burden might be significantly higher.

    This strategy also provides more flexibility in retirement. Many retirees find themselves in a lower tax bracket than they were in during their working years. This makes retirement an ideal time to perform tax-gain harvesting. Even if you do not need the cash immediately, “selling and buying” allows you to effectively move money from an “unrealized gain” status to a “tax-paid” status. This increases your portfolio’s after-tax liquidity, as a larger portion of your account balance becomes “basis” that can be withdrawn tax-free in the future. Furthermore, this strategy helps mitigate the risk of future changes in tax law. If you expect tax rates to rise, locking in a lower rate today—or a 0% rate—is a form of tax insurance. By controlling the timing and magnitude of your realized gains, you are taking control of your financial destiny, moving from a passive taxpayer to an active participant in your own tax management.

    When Is Tax-Gain Harvesting Actually Worth It?

    Determining whether tax-gain harvesting is worth the effort requires a candid assessment of your tax bracket, your investment horizon, and your current liquidity needs. The strategy is rarely a “one-size-fits-all” solution. It is most beneficial when there is a significant spread between your current tax rate and the tax rate you anticipate paying in the future. If you are currently in the 0% long-term capital gains bracket but anticipate being in a higher bracket in the coming years due to career advancement or the commencement of taxable pension income, the math strongly supports harvesting gains now.

    However, transaction costs and state taxes must also be factored in. While many brokerages now offer commission-free trading, you must ensure that your specific situation allows for a net positive outcome. In states with high income taxes, realized gains may be taxed at the state level even if the federal tax rate is 0%. You must calculate whether the state-level tax hit is lower than the projected future federal tax hit. If the state tax effectively wipes out the benefit of resetting your federal cost basis, the strategy loses its appeal. Additionally, consider your investment timeline. If you plan to hold an asset for only a few more months before selling for a specific goal, the tax-gain harvesting process might be unnecessary or even counterproductive if it resets a long-term holding period into a short-term one, inadvertently subjecting you to higher ordinary income tax rates.

    Finally, the most effective time to utilize this strategy is during periods of “taxable lulls.” These are periods where your ordinary income is temporarily depressed, such as years of part-time work, career breaks, or early retirement before required minimum distributions (RMDs) from retirement accounts begin. During these years, your standard deduction and lower tax brackets are often underutilized. By strategically harvesting gains during these windows, you turn what would otherwise be “wasted” tax space into a permanent, non-taxable cost basis increase. When performed consistently, this creates a “ratcheting” effect where your portfolio’s taxable sensitivity is steadily reduced over time. Ultimately, tax-gain harvesting is worth it when the cumulative future tax savings, discounted to present value, significantly exceed the immediate administrative friction and any applicable state-level taxes. It is a classic example of how minor, well-timed adjustments can lead to outsized wealth accumulation over a decades-long financial journey.

    Potential Pitfalls and Risks of Harvesting Gains

    While tax-gain harvesting can be a powerful tool for accelerating your wealth building, it is not a “set it and forget it” strategy. There are structural risks that, if ignored, could lead to suboptimal financial outcomes or, worse, an unexpected tax burden. Before moving forward, you must understand these potential friction points.

    The most significant risk involves the “opportunity cost” of capital. When you harvest a gain, you are effectively paying taxes today that you otherwise would have deferred into the future. By realizing that gain, you take money out of your brokerage account to send to the government. That capital is no longer working for you in the market, meaning you lose the potential for compounding growth on that tax payment over the coming decades. If your long-term goal is to keep as much money invested as possible, paying taxes early is technically a drag on your portfolio’s total potential, unless the tax-free basis step-up significantly outweighs this drag.

    Another danger is the disruption of your asset allocation. If you harvest gains in a particular sector or asset class to reset your basis, you might be tempted to move the proceeds into something “new” or “better.” Frequently changing your investment strategy based on tax events can lead to style drift, where your portfolio no longer reflects your original risk tolerance or long-term financial goals. Always ensure that the decision to sell is aligned with your core investment thesis, not just the tax calendar.

    Finally, keep an eye on state taxes. While federal tax-gain harvesting strategies are often well-documented, your state of residence may not mirror federal treatment of capital gains. Some states tax capital gains as ordinary income, which can be significantly higher than the preferential long-term capital gains rates at the federal level. Harvesting a gain might save you on your federal return but could trigger an unexpectedly high bill in your state, potentially negating the overall benefit of the strategy.

    How to Calculate Your Marginal Tax Rate Before Harvesting

    To successfully execute this tax strategy, you need to know exactly how much “room” you have within your current tax bracket. Your marginal tax rate is the tax percentage paid on the very last dollar you earned. In the context of tax-gain harvesting, you want to know if you can realize long-term capital gains at a 0% rate, or if you will be bumped into the 15% or 20% bracket.

    To calculate this, start by looking at your most recent tax return or your year-to-date pay stubs. Identify your Total Taxable Income. Remember, taxable income is your gross income minus all deductions (standard or itemized). Once you have this figure, you can consult current tax brackets for your filing status (Single, Married Filing Jointly, etc.).

    Here is a simplified approach to determine your capacity for harvesting:

    1. Identify your current taxable income: This is your income after all adjustments and deductions.
    2. Find your bracket limit: Locate the upper threshold for your current long-term capital gains tax bracket.
    3. Calculate the delta: Subtract your current taxable income from the upper threshold of the 0% or 15% bracket.
    4. Assess the impact: The resulting figure is the amount of capital gains you can potentially realize without “spilling over” into a higher tax bracket.

    Be careful to account for other income sources that might materialize before the end of the year, such as year-end bonuses, interest income from savings accounts, or non-qualified dividends. These sources of income “fill up” your brackets first, potentially leaving less room for your planned capital gains harvesting.

    Scenario Tax Strategy Best for
    Low-Income Year (Student/Sabbatical) Aggressive Gain Harvesting Zeroing out capital gains tax liability
    Stable/High Earning Years Strategic Loss/Gain Offsetting Managing tax bracket creep
    Retirement Transition Partial Realization Smoothing out income across years
    High Growth Portfolio Basis Management Preparing for future liquidations

    Step-by-Step Guide to Implementing a Gain Harvesting Strategy

    Implementing tax-gain harvesting requires precision. Follow these steps to ensure you remain compliant with the law and maximize your financial efficiency.

    1. Inventory Your Portfolio: Audit your brokerage accounts to identify assets with unrealized long-term capital gains. A long-term gain is defined as an asset held for more than one year. You cannot harvest a gain at the favorable long-term rate if you haven’t held the security for the required duration.

    2. Evaluate Your Tax Bracket: As discussed in the previous section, use your projected annual income to determine where your current gains will fall. If you can fit these gains into the 0% tax bracket, the strategy is mathematically superior to holding, as it resets your cost basis to market value without a tax bill.

    3. Execute the Sale: Sell the specific lots of the asset that have appreciated. Ensure your brokerage account is set to “Specific ID” (as opposed to FIFO or Average Cost) so you can control which shares are sold. This is a critical step in effective tax management.

    4. Reacquire the Position: Because you want to stay invested, you must immediately (or shortly after) repurchase the same or a substantially similar asset. *Note: Unlike tax-loss harvesting, there is no “wash sale” rule for gains. You can sell and rebuy immediately without penalty.*

    5. Update Your Records: Document the sale and the new cost basis in your financial tracker. This prevents errors when you file your taxes the following year. Your new cost basis will be the price at which you repurchased the security.

    Integrating Gain Harvesting Into Your Annual Financial Review

    Tax-gain harvesting should not be a reactive process; it should be a planned component of your annual financial housekeeping. Every November or December, set aside time to review your investment performance and tax projections.

    During this review, look at your “tax budget.” Ask yourself: “Does it make sense to realize some gains this year?” If you have had a year of lower-than-average income, it is a prime opportunity to “harvest” to fill up your lower tax brackets. This is often referred to as “bracket management.” By intentionally moving income into a year where your marginal rate is low, you reduce your future tax liability when you eventually sell those assets during your high-earning years or in retirement.

    Furthermore, combine this review with a check for tax-loss harvesting opportunities. If you have “losing” investments, you can sell them to offset the gains you just harvested. This combined “tax-efficient swap” allows you to reset your basis on profitable assets while simultaneously offsetting your tax bill with realized losses—a sophisticated tactic that is the hallmark of advanced financial planning.

    Avoiding Common Mistakes That Trigger Unnecessary Taxes

    Even with good intentions, investors often fall into traps that trigger preventable taxes. The most common error is forgetting about state taxes. As mentioned, federal planning is only half the battle. If you live in a high-tax state, harvesting a gain to pay 0% federal tax might still leave you with a hefty state tax bill that negates the entire incentive.

    Another common mistake is confusing “holding period” requirements. If you sell an asset held for 364 days, you realize a short-term capital gain, which is taxed at your ordinary income rate—usually much higher than long-term rates. Always verify your settlement dates to ensure the asset has truly crossed the one-year threshold before initiating a harvest.

    Lastly, avoid harvesting gains in assets that you might need to sell soon for other reasons, like a down payment on a house or college tuition. If you reset your cost basis and then sell the asset again for a loss shortly after, you may have wasted your efforts. Tax-gain harvesting is a long-term strategy for buy-and-hold investors; it is less effective for short-term liquidity needs.

    Frequently Asked Questions

    Is tax-gain harvesting legal?

    Yes, tax-gain harvesting is a perfectly legal and standard tax management strategy. It involves selling an appreciated asset to realize a gain and then immediately repurchasing it to reset your cost basis. It is a common part of proactive tax planning for investors who wish to minimize their future tax liability.

    Do I have to wait to buy back the stock?

    No, there is no “wash sale” rule for tax-gain harvesting. You can sell a security for a gain and repurchase the exact same security immediately. This differs from tax-loss harvesting, where you must wait 30 days to avoid the wash sale rule, which would disallow the loss for tax purposes.

    How does the 0% capital gains bracket work?

    If your total taxable income, including your long-term capital gains, stays below a certain threshold (which changes annually with inflation), your long-term capital gains are taxed at 0% federally. This provides a unique window to increase your cost basis for free, reducing the taxes you would have paid if you held the asset until a time when you were in a higher tax bracket.

    Should I harvest gains if I live in a state with high income taxes?

    You should approach this with caution. While you might avoid federal tax, your state might treat capital gains as ordinary income. Always calculate the combined federal and state tax impact before executing a harvest to ensure the strategy actually leaves you with more money in your pocket.

    Can I use tax-gain harvesting in my 401(k) or IRA?

    No, this strategy is only relevant for taxable brokerage accounts. Gains within tax-advantaged accounts like 401(k)s, IRAs, and Roth IRAs are either tax-deferred or tax-free, meaning there is no capital gains tax on transactions within the account. You cannot “harvest” a gain in an account that doesn’t track capital gains tax.

    How do I know if I have “realized” or “unrealized” gains?

    An unrealized gain (or “paper gain”) is the profit on an investment you still hold. You only realize a gain for tax purposes when you actually sell the asset. Tax-gain harvesting is the act of turning that unrealized gain into a realized gain by selling the asset to pay the tax now, rather than later.

    Conclusion

    Tax-gain harvesting is a sophisticated tool in your wealth-building arsenal. By proactively managing your cost basis, you can systematically reduce your long-term tax exposure and ensure that more of your investment returns stay in your pocket rather than flowing to the treasury. While it requires discipline, careful planning, and an understanding of your personal tax situation, the benefits of lower future tax drag are significant for long-term investors.

    Remember that wealth building is a marathon, not a sprint. Using strategies like gain harvesting ensures that you aren’t just growing your assets, but also protecting their growth from unnecessary tax erosion. Take the time during your annual financial review to assess your portfolio, check your bracket, and determine if now is the right time to harvest.

    Ready to take control of your financial future? Start by auditing your brokerage accounts today to see where you stand, and consult with a tax professional to map out a strategy that aligns with your long-term wealth goals.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.

  • HSA vs. 401(k): Which Should You Prioritize for Wealth?

    HSA vs. 401(k): Which Should You Prioritize for Wealth?

    Key Takeaways

    • The HSA is the only account offering a “triple-tax advantage,” making it an elite vehicle for long-term wealth building.
    • A 401(k) employer match provides an immediate, guaranteed return that often outweighs the tax benefits of other accounts.
    • Prioritize your 401(k) up to the company match threshold before shifting focus to other tax-advantaged accounts.
    • HSAs are increasingly viewed as “stealth IRAs” because they can be used for medical expenses in retirement or reimbursed later for past costs.
    • The optimal strategy involves balancing employer-sponsored benefits with personal health savings to maximize compound growth.

    Deciding where to allocate your hard-earned dollars is one of the most critical decisions in your journey toward financial independence. Many investors find themselves caught in a dilemma when comparing the HSA vs. 401k, wondering whether their priority should be immediate retirement saving or long-term health cost mitigation. While both are powerful tax-advantaged accounts, they serve different functions in your wealth building strategies. Understanding the nuances of these vehicles is essential for anyone looking to optimize their retirement planning and secure their future. At wealthsimplyput, we believe the best financial decisions are made when you understand the mechanics of your capital, ensuring that every dollar you earn is working as efficiently as possible.

    Understanding the Triple-Tax Advantage of HSAs

    The Health Savings Account (HSA) is widely regarded by financial experts as one of the most powerful tools in the tax code, often labeled as having a “triple-tax advantage.” To build wealth effectively, you must understand exactly how these three components function. First, contributions to your HSA are typically made pre-tax, which lowers your taxable income for the year, effectively giving you an immediate break on your income tax burden. If you contribute through your payroll, you also save on FICA taxes, which is an additional layer of savings that many other retirement vehicles do not offer.

    Second, the growth within the account is tax-deferred. When you invest your HSA funds in stocks, bonds, or mutual funds, you do not pay taxes on the dividends, interest, or capital gains that accumulate over the years. This allows your wealth to compound much faster than in a standard taxable brokerage account, where annual taxes on gains can create a “drag” on your long-term performance. This tax-free growth is the primary driver behind why many consider the HSA a cornerstone of robust health savings account investment strategies.

    Third, the distributions are tax-free, provided the money is used for qualified medical expenses. This is where the true power of the HSA reveals itself. Unlike a 401(k) or traditional IRA, where withdrawals are eventually taxed as ordinary income, your HSA withdrawals for medical costs remain entirely exempt from federal income tax. Because the list of qualified medical expenses is broad—ranging from doctor visits and prescriptions to certain dental and vision costs—the utility of these funds is significant.

    Perhaps the most compelling strategy for those who can afford it is to pay for current medical expenses out-of-pocket rather than using HSA funds. By keeping your receipts and allowing the HSA to remain invested, you effectively turn the account into a long-term investment vehicle. You can then reimburse yourself decades later, tax-free, at a time when your portfolio has potentially grown many times over. This “stealth IRA” approach allows the HSA to function not just as a health reserve, but as an additional bucket for retirement planning, providing a level of tax flexibility that is unmatched by other traditional accounts. When balancing your overall portfolio, the HSA should be viewed as a unique asset that protects you against the rising costs of healthcare while acting as a engine for long-term wealth accumulation.

    How 401(k) Employer Matching Boosts Your Returns

    When evaluating the HSA vs. 401k, the conversation must start with the “free money” provided by most employer-sponsored 401(k) plans. An employer match is essentially an immediate, guaranteed return on your investment. If your employer offers a dollar-for-dollar match up to a certain percentage of your salary, you are securing a 100% return on your contribution before the market even moves. In the world of finance, where achieving consistent double-digit returns is difficult, this match is arguably the most valuable benefit an employee can receive.

    The math behind the match is straightforward but profound. If you earn $60,000 and your company matches 3% of your salary, they are contributing $1,800 to your future. If you choose not to contribute, you are essentially leaving a $1,800 raise on the table. Over a thirty-year career, with moderate market growth, that specific match could grow into a significant portion of your total retirement nest egg. This is why financial literacy experts almost universally advise that employees secure their full employer match before considering any other investment vehicle, including the HSA.

    Furthermore, contributing to a 401(k) is often a “set it and forget it” process through automatic payroll deductions. This helps investors avoid the pitfalls of emotional decision-making, ensuring that capital is consistently directed toward wealth building without requiring constant vigilance. While the HSA is a fantastic vehicle, it does not offer this employer-guaranteed return component in most cases. When you are mapping out your financial priorities, the match should represent your “floor”—the baseline contribution level you must hit every single year to ensure you aren’t sacrificing free capital.

    Feature 401(k) HSA Best For
    Employer Match Yes (Typically) No Immediate Returns
    Tax Advantage Tax-Deferred Triple-Tax Free Long-Term Wealth
    Contribution Limits Higher Lower Capacity
    Withdrawal Penalty Strict (Age 59.5) Flexible (Medical) Accessibility

    Beyond the raw math, the psychological impact of the 401(k) match cannot be overstated. By automating your savings through your employer, you are creating a disciplined structure for wealth. Even if you are not yet maximizing your total HSA contribution limits, the discipline of contributing to your 401(k) builds the habit of investing. This foundation is crucial for long-term success, as wealth building is rarely about the single “best” investment but rather the consistency of your behavior over time. The 401(k) acts as the engine of your retirement, providing a reliable, tax-deferred path to growth that benefits directly from your employer’s participation.

    The Case for Maxing Out Your 401(k) First

    While the HSA is often cited as the “gold standard” of tax-advantaged accounts, the 401(k) typically takes precedence during the early stages of a wealth building strategy. The primary reason is simple: capacity and structure. The annual HSA contribution limits are notably lower than 401(k) contribution limits. If you have a significant amount of capital to deploy, the 401(k) allows you to shelter a much larger portion of your income from taxes, which is a major advantage for high-earners looking to reduce their taxable liability while aggressively funding their retirement.

    Another factor to consider is the ease of administration. 401(k) plans are integrated into your payroll, meaning the money is invested before it ever hits your checking account. For many individuals, this removes the temptation to spend the money elsewhere. When you are tasked with manual transfers to an HSA, there is often more room for error or procrastination. While an HSA is highly flexible, the 401(k) is specifically designed to guard your retirement assets until you reach the age of retirement. This “locked-in” nature serves a purpose: it prevents you from dipping into your nest egg prematurely, which is a common error that can derail long-term compounding.

    Furthermore, many modern 401(k) plans offer a diverse selection of low-cost, institutional-grade index funds. These funds often come with lower expense ratios than the retail-grade investments available in some HSAs. While this isn’t always the case, it is worth comparing the investment options provided by your employer’s plan versus the ones available at your preferred HSA custodian. If your 401(k) offers access to ultra-low-cost, broad-market index funds, the administrative savings may add up to thousands of dollars over the course of your career.

    We should also address the “catch-up” contribution potential. For individuals approaching their peak earning years, 401(k) plans often allow for higher catch-up contributions compared to HSAs. This allows investors to significantly pad their retirement accounts as they move closer to their target retirement date. By prioritizing the 401(k) early on, you leverage the power of compound interest for a larger principal amount, which is mathematically superior to trying to catch up later in life with smaller, limited account types. The strategy is clear: reach for the employer match, then utilize the 401(k) to aggressively capture tax-deferred growth, keeping the HSA as a vital supplementary tool for health-related costs and tax-efficient wealth management.

    When the HSA Should Take Priority in Your Strategy

    There are specific scenarios where the HSA should leapfrog the 401(k) in your hierarchy of funding. Once you have secured your employer match in your 401(k), the HSA often becomes the next most efficient vehicle for your remaining investable dollars. This shift is particularly advantageous for individuals who have a high-deductible health plan (HDHP) and expect to have significant out-of-pocket medical costs in the near future. By contributing to the HSA, you ensure that you are covering these inevitable expenses with pre-tax dollars rather than post-tax income, which is an immediate savings of your marginal tax rate.

    Beyond current medical needs, the HSA takes priority for those who are “maxing out” their other tax-advantaged options. Once you have filled your 401(k) to the annual limit, you are left with the choice between a taxable brokerage account and an HSA. In this scenario, the HSA wins handily because of its triple-tax advantage. Even if you do not have current medical expenses, the ability to invest the funds for the long term makes it superior to a brokerage account where you must pay taxes on dividends and capital gains every year. It effectively acts as a “super-IRA” for those who have already exhausted their retirement plan limits.

    Another compelling reason to prioritize the HSA is the flexibility regarding withdrawal timing. Unlike a 401(k), which carries penalties for early withdrawal before age 59.5, an HSA can be utilized for qualified medical expenses at any time without penalty. While we strongly encourage investors to let their HSA assets grow for the long haul, the fact that you have a “safety valve” in case of a true emergency provides a layer of liquidity that a traditional retirement account lacks. This is particularly valuable for individuals who are still building their emergency funds or who have unpredictable income streams.

    Furthermore, if you view your HSA as a vehicle to cover future retirement healthcare costs—which are historically one of the largest expenses retirees face—prioritizing it makes strategic sense. By the time you reach retirement, you will likely have significant medical expenses, and having a dedicated, tax-free pot of money to cover them will preserve your other retirement accounts. By allocating funds to your HSA now, you are essentially “pre-funding” your future health, which allows you to spend your 401(k) and Social Security income on lifestyle and travel. It is a strategic move that protects your standard of living in your later years, making the HSA a vital pillar in your overall wealth building strategies.

    Impact of Withdrawal Rules on Long-Term Wealth

    The rules governing how you access your money are just as important as the rules governing how you contribute. When looking at the HSA vs. 401k, the withdrawal phase reveals a stark difference in flexibility and tax treatment. The 401(k) is governed by the Internal Revenue Code’s strict age-based triggers. Generally, taking distributions before age 59.5 results in a 10% penalty on top of ordinary income taxes. This, combined with the fact that all distributions are taxed at your ordinary income tax rate, makes the 401(k) a relatively rigid asset class designed for the specific stage of life where you are no longer earning a primary income.

    In contrast, the HSA offers a degree of freedom that is rare in the tax-advantaged world. Because the account is designed to bridge the gap between healthcare needs and long-term saving, it allows for tax-free withdrawals at any time, provided they are for qualified medical expenses. This is the “loophole” that financial planners have long championed: you can pay for health costs throughout your life, or you can track your spending and reimburse yourself years or even decades later. There is no requirement that you withdraw the money in the same year the expense occurred, so long as the expense was incurred after the HSA was established.

    This allows for a sophisticated wealth strategy where the HSA serves as a flexible buffer. If you encounter a market downturn during your retirement years, you might prefer not to sell your 401(k) assets while they are depressed. In that scenario, you can dip into your HSA to cover your medical costs, allowing your retirement account more time to recover. By having two distinct pools of money with different withdrawal rules, you gain a tactical advantage in managing your tax bracket in retirement. You can control your “taxable income” by pulling strategically from your 401(k) while filling in the gaps with the tax-free distributions from your HSA.

    Additionally, it is worth noting that after age 65, the penalty for non-medical withdrawals from an HSA disappears. While you will still pay ordinary income tax on these non-medical withdrawals (making it function like a traditional IRA), the ability to access the funds without a penalty after 65 provides a significant “safety net” if you find yourself overfunded in the HSA and underfunded elsewhere. This flexibility is a powerful tool for long-term wealth management, allowing you to adapt your strategy to the realities of your retirement years. When viewed through the lens of withdrawal rules, the HSA provides a level of versatility that ensures your assets are always serving you, regardless of whether you encounter a health crisis or simply a shift in your retirement goals.

    Balancing Both Accounts for Optimal Growth

    When you have access to both a Health Savings Account (HSA) and a 401(k), you are essentially holding two of the most powerful engines for wealth building currently available. Rather than viewing this as a binary choice—one or the other—the most sophisticated investors view these accounts as interlocking gears within a single wealth machine. The key to long-term prosperity often lies in a tiered contribution strategy.

    The standard industry recommendation, which many experts support, is to prioritize your 401(k) first only up to the point of securing the full employer match. This is, in effect, a guaranteed return on investment. If your employer offers a dollar-for-dollar match up to 5%, failing to contribute that 5% is essentially walking away from a portion of your total compensation. Until you have captured every cent of that match, your capital is arguably better placed in the 401(k) than anywhere else.

    Once the employer match is secured, the pendulum of efficiency often swings back to the HSA. Because an HSA offers a “triple tax advantage”—contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free—it is arguably the most tax-efficient vehicle in the American retirement landscape. By filling your HSA to the annual contribution limit, you are sheltering a significant portion of your income from taxes twice: once at the point of deposit and once at the point of spending.

    After you have maxed out your HSA, you can then pivot back to the 401(k) to utilize the remaining contribution room. This strategy ensures that you capture free money from your employer while simultaneously maximizing the unique tax shielding that the HSA provides. By oscillating between these two accounts based on your specific financial milestones, you create a diversified tax footprint that prepares you for almost any regulatory or economic environment in the future.

    Common Mistakes When Choosing Between HSA and 401(k)

    Wealth building is often as much about avoiding errors as it is about making smart moves. Many individuals fall into traps that limit their long-term potential. Here are the most prevalent mistakes to avoid.

    1. Treating the HSA as a Checking Account: Many users make the mistake of using their HSA as a pass-through vehicle for daily medical bills. By liquidating the account as soon as a co-pay arrives, you forfeit the power of compound interest. If you can afford to pay for healthcare costs out-of-pocket, keep your HSA funds invested in the market and save your receipts. You can reimburse yourself tax-free years or even decades later.
    2. Ignoring Investment Fees: Not all 401(k) and HSA providers are created equal. Some HSAs charge exorbitant monthly maintenance fees or administrative costs if your balance is below a certain threshold. Similarly, 401(k) plans can be laden with high-expense-ratio mutual funds. Always review the fee schedule; high fees can erode the wealth-building benefits of these tax-advantaged accounts over time.
    3. Failing to Adjust for Inflation: Contribution limits for both accounts typically rise over time. A common mistake is to set your payroll deductions once and never touch them again. Review your contribution levels annually to ensure you are maximizing your tax-advantaged space as limits increase.
    4. Neglecting Beneficiary Designations: These accounts are a critical component of estate planning. Failing to name a beneficiary—or failing to update one after life events like marriage or the birth of a child—can lead to unintended tax consequences for your heirs.
    Account Type Primary Wealth Mechanism Best For
    401(k) Employer Matching Retirement income & long-term savings
    HSA Triple Tax Benefit Healthcare costs & supplemental tax-free retirement fund

    The Role of Tax Brackets in Your Decision-Making Process

    Your marginal tax bracket serves as the ultimate litmus test for how much value you derive from these accounts. Because both 401(k) and HSA contributions are made on a pre-tax basis, their immediate value is tied directly to the taxes you would have otherwise paid on that income. For high-income earners, the benefit of these deductions is magnified.

    If you are in a higher tax bracket, the “savings” you receive from contributing to a 401(k) or HSA are substantial. For instance, if you are in a 32% marginal tax bracket, a $1,000 contribution to an HSA essentially “costs” you far less in terms of actual take-home pay because the government is subsidizing a large portion of it through lower income tax liability. Conversely, if you are in a lower tax bracket, the immediate tax benefit is smaller, though the long-term wealth-building power of the accounts remains unchanged.

    It is important to understand that your tax bracket may fluctuate throughout your career. If you expect your income to rise significantly, it may be prudent to prioritize accounts that offer immediate deductions now. Conversely, if you are early in your career and in a lower bracket, some might consider a Roth 401(k) option if it is available, as paying taxes now might be cheaper than paying them in retirement. However, the HSA remains superior in nearly all scenarios because it never requires you to pay tax on the growth or the withdrawal, regardless of your bracket at the time of retirement.

    How to Adjust Your Strategy as Your Income Increases

    As your career progresses and your salary increases, your strategy should evolve from “saving for the match” to “maximizing total tax efficiency.” When you reach a point where you can comfortably max out both your HSA and your 401(k), look toward other vehicles like an IRA or a taxable brokerage account.

    As income rises, focus on these three phases of wealth building:

    • Phase One: The Match and the Floor. Contribute enough to your 401(k) to get the match. Simultaneously, contribute as much as possible to your HSA to cover your estimated annual out-of-pocket medical costs.
    • Phase Two: The Ceiling. As your discretionary income grows, push toward the annual IRS contribution limits for both the HSA and the 401(k). At this stage, treat your HSA as an investment vehicle rather than a medical expense fund. Let the money grow untouched.
    • Phase Three: The Overflow. Once your tax-advantaged space is fully utilized, begin investing in taxable brokerage accounts. Maintain a diversified portfolio that complements the holdings within your 401(k) and HSA, being mindful of tax-efficient fund placement.

    Additionally, as your income increases, consider the “catch-up” contributions allowed by the IRS once you reach age 50. These provisions allow older workers to accelerate their savings, providing a vital opportunity to bolster your nest egg during your peak earning years.

    Frequently Asked Questions

    Can I use my HSA to pay for my spouse’s medical expenses?

    Yes. You can generally use your HSA funds to cover the qualified medical expenses of your spouse and any dependents, even if they are not covered under your specific high-deductible health plan. This makes the HSA an excellent tool for family wealth management.

    What happens to my HSA if I change jobs?

    Unlike a 401(k), which you may be forced to roll over to an IRA or new employer plan, your HSA is owned entirely by you. It is portable. If you change jobs, you keep the account, the balance, and the investments regardless of your new employment status or health insurance coverage.

    Is it better to take the 401(k) match or max out my HSA?

    You should almost always prioritize the 401(k) match first. The match represents an immediate, risk-free return on your money—often 50% or 100% depending on the employer’s policy. No other investment vehicle can guarantee that level of instant growth. Once the match is captured, the HSA becomes a superior secondary priority.

    Are HSA investments taxed when I withdraw them for retirement?

    If you withdraw funds for qualified medical expenses, they are never taxed. If you withdraw funds for non-medical reasons after age 65, the withdrawal is treated like a standard 401(k) distribution and is taxed as ordinary income. However, the unique benefit is that you have the flexibility to use it for medical needs tax-free at any time.

    Can I have both an HSA and a standard 401(k)?

    Yes, you can hold both simultaneously. They operate independently of each other. The HSA is tied to your health insurance plan, while the 401(k) is tied to your employment. Contributing to one does not reduce your contribution limits for the other.

    Do I have to invest the money in my HSA?

    You are not required to invest the money in your HSA. Most accounts start as a cash savings balance. However, to build significant wealth, most providers allow you to move your cash balance into a brokerage investment account. Investing is the only way to allow your HSA to grow significantly over time.

    Conclusion

    The journey toward wealth is rarely defined by a single decision, but rather by the consistent application of sound financial principles. By understanding the distinct roles of the HSA and the 401(k), you can construct a robust defense against inflation, taxes, and unexpected costs. Remember that the 401(k) is your primary engine for retirement security through employer contributions, while the HSA acts as a sophisticated tax-free growth vehicle for both health and future lifestyle goals. Start by securing your match, then leverage the triple-tax advantage of the HSA, and finally, look to max out your contributions as your income allows. Take control of your financial destiny today by auditing your current contributions and ensuring your strategy aligns with your long-term wealth goals.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.

  • Tax-Efficient Asset Location: Where to Keep Your Investments

    Tax-Efficient Asset Location: Where to Keep Your Investments

    Key Takeaways

    • Asset location is the deliberate strategy of placing specific investments into specific accounts to minimize tax drag.
    • While asset allocation defines your risk profile, asset location optimizes the tax treatment of your returns to preserve more wealth.
    • Tax-inefficient assets, such as high-yield bonds or actively managed funds, often perform best in tax-advantaged accounts like IRAs or 401(k)s.
    • Taxable brokerage accounts are ideal for tax-efficient assets like index funds or ETFs that benefit from favorable long-term capital gains tax rates.
    • Mastering asset location is a foundational wealth-building strategy that can significantly enhance your net after-tax returns over a long-term investment horizon.

    Most investors spend the vast majority of their time choosing which stocks or funds to buy, often ignoring where those investments actually live. However, for those focused on serious wealth building, the question of where to keep your investments is just as vital as what you own. Taxes are often the single largest expense an investor faces, yet many people inadvertently leave money on the table by holding high-tax assets in the wrong account types. By utilizing a strategic approach to asset location, you can legally and systematically reduce your tax burden, ensuring that more of your money stays invested and compounding over time. This guide explores how to structure your portfolio to ensure your hard-earned wealth is working as efficiently as possible, regardless of market conditions.

    What Is Asset Location and Why Does It Matter for Wealth?

    Asset location is the strategic process of deciding which types of investments should be placed in which types of accounts—tax-advantaged (like a 401(k) or IRA) versus taxable brokerage accounts—to minimize your total tax liability. While many investors are familiar with “asset allocation” (the mix of stocks, bonds, and cash), asset location is the invisible engine that powers a tax-efficient portfolio. It is not about avoiding taxes permanently, but rather about deferring, reducing, or optimizing them to enhance your net after-tax returns.

    The core philosophy behind this strategy is simple: not all investments are taxed the same way. Some investments generate high annual tax bills, while others are structured to grow with minimal interference from the IRS. If you place a “tax-heavy” investment in a taxable account, you are effectively choosing to pay a portion of your wealth to the government every single year. Over decades, this annual tax drag acts like a slow leak in a boat, significantly hindering your ability to accumulate wealth. Conversely, by strategically placing your assets, you can keep more money invested, allowing the power of compounding to work on the entirety of your principal rather than a diminished amount.

    For high-net-worth individuals or those planning for a long-term retirement, asset location is a foundational element of wealth management. It requires an understanding of how dividends, interest, and capital gains are taxed. For example, interest income is typically taxed as ordinary income, which is often higher than the tax rate on qualified dividends or long-term capital gains. By understanding these nuances, an investor can “place” these assets where they will do the least amount of “damage” to the portfolio’s growth.

    Furthermore, asset location is not a “set it and forget it” strategy; it evolves as your wealth grows and your tax situation changes. As you transition from the accumulation phase of your career to the distribution phase of retirement, your needs regarding account liquidity and tax efficiency may shift. However, the fundamental goal remains the same: to create a portfolio structure where the internal mechanics of your accounts work in harmony with your tax obligations. Ultimately, mastering asset location is about taking control of your financial ecosystem. It is an internal wealth-building strategy that requires no change to your underlying risk tolerance or market expectations, yet it can result in substantially higher wealth retention over the course of a lifetime.

    Asset Location vs Asset Allocation: Understanding the Difference

    It is a common point of confusion for new and experienced investors alike: how do asset allocation and asset location differ? While the terms sound nearly identical, they serve distinct purposes in your financial journey. Think of asset allocation as your “what” and asset location as your “where.”

    Asset allocation is the process of dividing your portfolio among different asset categories, such as stocks, bonds, and cash. This is the primary driver of your risk and return. If you want a portfolio that can weather a stock market downturn, you might allocate 60% to stocks and 40% to bonds. This decision is based on your time horizon, financial goals, and personal risk tolerance. Asset allocation is about building a portfolio that aligns with your personality and your objectives; it determines the volatility you are willing to endure for a specific expected return.

    Asset location, by contrast, is the tactical execution of that allocation. Once you decide you need 40% bonds, the question becomes: which account should those bonds live in? If you put all your bonds in a taxable brokerage account, you might be subjected to high annual taxes on the interest payments. If you instead move those bonds into a tax-advantaged account like a Traditional IRA, you can defer those taxes until you actually begin withdrawing the funds in retirement. Asset location does not change your overall exposure to stocks or bonds; it changes the tax environment in which those assets operate.

    To put this into perspective, consider the following comparison table which helps illustrate how these concepts differ and where they fit into a broader tax-efficient investing strategy:

    Feature Asset Allocation Asset Location Best For
    Primary Focus Risk and return profile Tax efficiency of returns Holistic wealth planning
    Core Question What do I own? Where do I keep it? Optimizing net wealth
    Impact Volatility management Tax leakage reduction Long-term growth

    The magic happens when you integrate these two strategies. You determine your ideal asset allocation first, and then you apply asset location principles to execute that allocation in the most tax-friendly manner possible. If you ignore asset location, you might have the perfect risk profile, but you will be paying higher costs than necessary in the form of taxes. If you focus only on asset location but lack an asset allocation strategy, you may end up with a tax-efficient portfolio that is far too risky or far too conservative for your actual needs. For the wealth-conscious investor, these two concepts must work in tandem to ensure that you are maximizing returns while maintaining the appropriate level of comfort with market fluctuations.

    How Taxes Impact Your Investment Returns

    To understand the necessity of asset location, one must first confront the reality of how taxes erode wealth. When you earn money in a taxable investment account, the IRS essentially becomes a silent, involuntary partner in your portfolio. Taxes on investments typically come in three primary forms: taxes on interest income, taxes on dividends, and taxes on capital gains.

    Interest income, such as that generated by bonds, bank savings, or high-yield money market funds, is generally taxed as ordinary income. In many jurisdictions, this can be the highest rate you pay—the same rate applied to your regular salary. Because this interest is taxed in the year it is earned, you are forced to pay the tax bill immediately, which removes a portion of the interest from your account. This effectively lowers the compound interest rate you receive, as you have less capital remaining in the account to earn interest the following year. Over a 20- or 30-year period, this “tax drag” can reduce the final value of your portfolio by a significant margin.

    Dividends also represent a common tax friction. Qualified dividends are taxed at more favorable long-term capital gains rates, which is better than the ordinary income tax bracket. However, non-qualified dividends are taxed as ordinary income. If you hold a high-dividend-paying investment in a taxable account, you will receive a 1099-DIV form every year, and you will be required to settle your tax liability annually. This is a recurring drain on your portfolio’s growth potential.

    Capital gains occur when you sell an asset for more than you paid for it. The beauty of capital gains tax is that it is typically deferred until you decide to sell the asset. This allows you to control exactly when you trigger the tax event. By holding onto appreciating assets in a taxable account, you are effectively allowing the government’s share of your growth to continue growing for your benefit until the moment of sale. This is why many long-term wealth builders prefer assets that appreciate in value (like growth stocks or broad market index funds) rather than assets that produce high annual cash flows (like bonds or high-yield funds) in their taxable brokerage accounts.

    The impact of taxes is often invisible because it happens behind the scenes. You rarely see a line item labeled “wealth reduction due to taxes” on your brokerage statement, but it is there, embedded in the difference between your gross returns and your net-of-tax returns. Even a small tax drag—say, 1% per year—can compound into a significant loss of wealth over time. By becoming intentional about tax-efficient investing, you are essentially giving yourself a raise. Every dollar you save on taxes through smart asset location is a dollar that stays invested and contributes to your total wealth.

    Where to Hold Tax-Inefficient Investments Like Bonds

    Now that we have established that taxes are a major hurdle to wealth accumulation, we must address the “where” of your specific holdings. Some assets are inherently “tax-inefficient,” meaning they produce a steady stream of income that triggers tax events on a frequent basis. Bonds and fixed-income securities are the most common examples. Because bonds pay interest (coupon payments) on a regular schedule, and because that interest is typically taxed as ordinary income, they are rarely the best candidates for a taxable brokerage account.

    If you hold a significant allocation of bonds, the most logical place for them is a tax-advantaged account, such as a 401(k), 403(b), or Traditional IRA. In these accounts, interest payments accumulate without triggering an immediate tax bill. You do not pay taxes on the interest in the year it is earned; you only pay taxes when you withdraw the money during retirement. This allows your bond holdings to compound at their full, pre-tax rate, which can lead to a much larger end balance over long periods.

    For those who have reached the limits of their tax-advantaged accounts and must hold bonds in a taxable account, there are alternative strategies. One such option is to use municipal bonds. In many regions, interest earned from municipal bonds is exempt from federal income tax and, in some cases, state and local taxes as well. While the nominal interest rate on municipal bonds might be lower than that of corporate or government bonds, the “tax-equivalent yield” can often be much higher for investors in high tax brackets.

    Actively managed funds are another category of investment that can be quite tax-inefficient. These funds often engage in frequent buying and selling of securities, which can trigger capital gains distributions that you are forced to pay taxes on, even if you haven’t sold a single share of the fund yourself. If you are determined to hold actively managed strategies, doing so within a tax-advantaged structure is usually the preferred method. This shields you from the “phantom” taxes caused by the internal turnover of the fund manager’s portfolio.

    In short, if an investment produces “tax noise”—recurring interest, frequent capital gains distributions, or ordinary income payouts—it should be prioritized for your tax-sheltered accounts. By creating this separation, you keep your taxable account clean, focused on long-term appreciation, and relatively easy to manage during tax season. This approach requires some coordination, especially when you have multiple accounts, but it is one of the most effective ways to preserve wealth against the erosion caused by annual taxation.

    The Best Assets to Keep in Your Taxable Brokerage Accounts

    If tax-inefficient assets belong in tax-advantaged accounts, then the inverse is true for your taxable brokerage accounts. Your taxable account should be a “sanctuary” for assets that are tax-efficient—those that minimize annual tax events and allow you to take full advantage of long-term capital gains rates. This is where you want to keep the core of your wealth-building engine: tax-efficient index funds, exchange-traded funds (ETFs), and individual stocks held for the long haul.

    Broad market index funds and ETFs are excellent candidates for taxable accounts. Because they are designed to track an index, their internal turnover is typically very low. They do not frequently sell underlying stocks, which means they rarely distribute capital gains. They simply hold the basket of companies and grow in value over time. When you eventually decide to sell your position, you will be taxed at the long-term capital gains rate—which is almost always lower than the ordinary income tax rate—and only on the profit you have made. This gives you significant control over your tax bill.

    Individual growth stocks are another prime example of assets that belong in taxable accounts. Many growth-oriented companies do not pay dividends, choosing instead to reinvest their profits into the business to fuel further expansion. Because there is no dividend payment, there is no taxable income generated. You own the asset, it grows in value, and you pay zero taxes until you choose to liquidate. This is the definition of a tax-deferred wealth builder. By holding these stocks in a taxable brokerage account, you are effectively using the account as a tax-deferral vehicle, mirroring the benefits of a retirement account without the strict withdrawal constraints.

    Tax-managed funds are also an option for taxable accounts. These are specialized funds specifically designed by investment firms to minimize the tax impact on the investor. They may use techniques like tax-loss harvesting—selling losing positions to offset capital gains elsewhere in the portfolio—to keep your tax bill as close to zero as possible. If you are a high-income earner, a tax-managed fund can be a powerful tool for maintaining a growth-oriented portfolio while minimizing the friction caused by taxes.

    As you build your taxable brokerage account, keep it simple. Avoid assets that churn out constant interest or high-turnover dividends. Your goal for this account is to participate in the growth of the economy with as little “leaking” of your gains to the tax collector as possible. When you hold these assets for years or even decades, you aren’t just earning returns on your money; you are earning returns on the money that would have otherwise been sent to the IRS in the form of annual taxes. This is the essence of compounding at its most powerful, and it is the standard by which all serious wealth builders should structure their taxable accounts.

    Maximizing Tax-Advantaged Space for High-Growth Assets

    When curating a tax-efficient portfolio, the ultimate goal is to minimize the “tax drag” on your wealth-building strategies. A critical component of this is identifying which assets have the highest potential for long-term appreciation and ensuring they are housed in accounts that shelter them from annual tax reporting. High-growth assets, such as small-cap stocks or aggressive equity index funds, are prime candidates for your tax-advantaged space, such as Roth IRAs or 401(k)s.

    Why prioritize high-growth assets in tax-sheltered environments? Because compounding is the engine of wealth, but taxes act as a friction-inducing brake. If you hold an asset that is expected to double or triple in value over the next two decades, the tax-free growth provided by a Roth account ensures that 100% of that expansion remains in your pocket. Conversely, if that same asset were in a taxable brokerage account, you would eventually face capital gains taxes upon selling, which can meaningfully erode the final result of your long-term compounding.

    To maximize this space, investors should audit their current holdings to determine which percentage of their portfolio consists of high-growth vehicles. If your tax-advantaged accounts are limited in size, prioritize the assets that you believe will have the highest total return. This strategy, often referred to as “tax-aware growth allocation,” forces you to be disciplined about where you place your most aggressive bets. By keeping these assets in IRAs or 401(k)s, you effectively shield the largest portion of your future wealth from the IRS.

    Handling REITs and Commodities in Your Portfolio

    Real Estate Investment Trusts (REITs) and commodity-linked assets present unique challenges for tax-efficient investing. Unlike standard stocks that provide qualified dividends, REITs typically pay out distributions that are classified as ordinary income. Because ordinary income is often taxed at your highest marginal tax rate, placing REITs in a taxable account can be inefficient. For many investors, sheltering REITs in a tax-deferred account is a standard best practice to prevent that high annual tax bill from undermining your broader wealth goals.

    Commodities, on the other hand, are often held through Exchange-Traded Funds (ETFs) or Exchange-Traded Notes (ETNs) that may utilize complex structures. Some commodity-linked investments issue K-1 tax forms, which add a layer of complexity to your annual tax filings. Furthermore, certain commodity futures-based funds are taxed according to the “60/40 rule” in the United States, where a portion of the gains are taxed at long-term rates and others at short-term rates, regardless of holding period. Due to this complexity and the potential for unfavorable tax treatment, these assets are frequently better suited for tax-advantaged accounts where the internal tax reporting is simplified or deferred until withdrawal.

    Asset Class Tax Profile Best For
    Equity Index Funds Qualified dividends/Long-term gains Taxable Accounts
    REITs Ordinary income (high tax burden) Tax-Advantaged (IRA/401k)
    Municipal Bonds Generally tax-exempt Taxable Accounts
    Commodities/Futures Complex (often 60/40 rule) Tax-Advantaged (IRA/401k)
    High-Yield Corporate Bonds Ordinary income Tax-Advantaged (IRA/401k)

    How to Transition Your Portfolio Without Triggering Capital Gains

    Transitioning an existing, tax-inefficient portfolio to a more optimized structure can feel daunting. Many investors fear that the process of moving assets—selling them in a taxable account to re-purchase them elsewhere—will trigger a massive tax bill that negates the benefits of the move. However, you can manage this transition strategically using several common techniques.

    First, utilize the “drift” method. Instead of selling all your current holdings at once, simply direct all new contributions to the assets you want to hold in your taxable account. If you need to rebalance, use your dividends or new cash injections to buy the desired tax-efficient assets, rather than selling the ones you already own. Over time, your asset location will align with your goals through organic growth and new capital rather than forced liquidations.

    Second, consider the concept of “tax-loss harvesting.” If you have assets that have depreciated, you can sell them to realize a loss, which can then be used to offset capital gains from other sales. This creates a “tax-neutral” window to reorganize your portfolio. Finally, prioritize moves within your tax-advantaged accounts. You can trade as often as you like inside an IRA or 401(k) without any immediate tax consequences. Start by optimizing the assets within those accounts first, and leave the taxable account transition for when you have enough harvested losses to cover the exit costs.

    Common Asset Location Mistakes That Drain Your Returns

    Even seasoned investors fall prey to common pitfalls that can quietly diminish their wealth over time. The most frequent error is “mental accounting,” where an investor treats all accounts as having equal tax weight. This leads them to hold high-turnover, tax-inefficient mutual funds in a standard brokerage account, resulting in high annual tax bills that significantly lower their net-of-tax return.

    Another common mistake is failing to account for the impact of dividends. Investors often focus on price appreciation but forget that dividends are taxable events in brokerage accounts. Holding high-dividend stocks or bond funds in a taxable account creates a “tax leak” every single year, preventing that money from compounding. Conversely, some investors try to be “too perfect” and move assets around so frequently that they trigger short-term capital gains taxes, which are taxed at higher rates than long-term gains. Tax-efficient investing is a long game; over-optimization can be just as damaging as under-optimization.

    Finally, there is the mistake of ignoring state taxes. While many people focus on federal brackets, high-state-income-tax residents often benefit from using municipal bonds or other state-specific tax shelters. Ignoring the state-level impact of your asset location choices can mean missing out on significant, year-over-year savings that would otherwise contribute to your long-term wealth.

    Frequently Asked Questions

    Is tax-efficient asset location more important than asset allocation?

    Asset allocation—the mix of stocks, bonds, and cash—is generally considered the primary driver of portfolio risk and return. Asset location is a secondary strategy used to improve the efficiency of that allocation. While location can add value by reducing tax drag, it should never come at the expense of your fundamental risk profile or investment strategy.

    Can I achieve tax-efficient investing without a financial advisor?

    Yes, many self-directed investors successfully manage their own asset location by following clear, consistent rules. By keeping tax-inefficient investments in sheltered accounts and low-turnover, tax-efficient assets in brokerage accounts, you can replicate professional-level efficiency. However, if your tax situation is complex due to business ownership, stock options, or multi-state residency, consulting a professional may be warranted.

    What is the “tax drag” and how does it impact wealth?

    Tax drag refers to the reduction in an investment’s annual return due to the taxes paid on dividends, interest, or capital gains. Over decades, even a small amount of tax drag can have a significant negative impact on the power of compounding. Minimizing this drag is a fundamental pillar of long-term wealth building.

    Do I need to rebalance my portfolio annually for tax reasons?

    You should rebalance when your asset allocation deviates from your target, but you should do so tax-consciously. Rather than selling assets in taxable accounts, try to rebalance by adjusting where you direct new contributions or by exchanging funds within your tax-advantaged accounts. This allows you to maintain your target risk level without creating unnecessary taxable events.

    Are ETFs always more tax-efficient than mutual funds?

    Generally, ETFs are more tax-efficient than traditional mutual funds due to their unique “in-kind” creation and redemption process, which often minimizes capital gains distributions to shareholders. However, this is not a hard-and-fast rule; some mutual funds are highly tax-efficient, and some ETFs are not. Always review the tax distribution history of a specific fund before investing.

    Should I prioritize paying off debt or optimizing asset location?

    This depends on your interest rates and expected investment returns. If your debt has a very high interest rate, paying it off usually provides a guaranteed “return” that beats most market investments. Once high-interest debt is managed, you can focus on optimizing your asset location to accelerate wealth accumulation through tax efficiency.

    Conclusion

    Mastering tax-efficient asset location is one of the most effective ways to tip the scales in your favor when building long-term wealth. By recognizing the unique tax profiles of your investments and mapping them to the most appropriate account types, you transform your portfolio from a taxable burden into a streamlined machine designed for compound growth. While the nuances of REITs, commodities, and capital gains may seem complex, the principles of keeping tax-inefficient assets sheltered and tax-friendly assets in taxable accounts remain the gold standard for savvy investors.

    Do not let the complexity of taxes paralyze your progress. Start by auditing your current holdings, move toward your target location gradually, and remain consistent with your strategy. Your future self will thank you for the extra wealth captured simply by paying attention to where your money lives. If you are ready to take control of your financial destiny, start by reviewing your brokerage and retirement statements today to ensure your assets are positioned for maximum efficiency.

    By wealthsimplyput Editorial Team

    This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.