- Wealth creation is primarily a mindset shift that prioritizes long-term outcomes over immediate consumption.
- Establishing a clear financial baseline is the essential first step to measuring progress toward your goals.
- A sustainable budget functions as a tool for intentional spending rather than a mechanism for restriction.
- Aggressive debt elimination acts as a guaranteed return on investment by stopping interest accumulation.
- An emergency fund provides the psychological and financial buffer necessary to avoid dipping into long-term investments during life’s inevitable setbacks.
The journey to financial independence often feels like an insurmountable mountain when you are standing at the base with nothing but your ambitions. Many people believe that wealth is the byproduct of luck, inheritance, or high-level insider connections, but the reality is far more accessible. Learning how to build wealth from nothing requires a departure from traditional consumer habits and an embrace of intentional, compounding behaviors. Whether you are currently staring at a negative net worth or simply looking to organize your finances for the first time, the path forward is paved with consistent, repeatable actions. By mastering the fundamentals of personal finance—budgeting, debt management, and proactive saving—you can transform your financial trajectory. This guide serves as your roadmap, designed to strip away the confusion and provide clear, actionable wealth building strategies that work for anyone, regardless of their starting point.
The Psychology of Wealth Creation
Before you calculate a single dollar, you must first address the internal machinery that drives your financial decisions. The psychology of wealth creation is the bedrock upon which all successful wealth building strategies are constructed. Most individuals view money through the lens of scarcity or immediate gratification, viewing every paycheck as a resource to be depleted. To change your financial reality, you must pivot toward a mindset of abundance and long-term utility. This shift is not about depriving yourself of the joy of living; it is about recognizing that every dollar spent today is a dollar that cannot work for you in the future.
One of the most significant psychological barriers to starting from zero is the “all-or-nothing” fallacy. People often feel that if they cannot save a large sum of money, the effort is not worth making. However, building wealth is not an event; it is a series of small, mundane decisions repeated over thousands of days. Wealth creation is essentially the art of delaying gratification. When you choose to invest in your future rather than consume a non-essential luxury, you are actively re-wiring your brain to value your future self as much as your present self. This requires self-awareness. You must identify your “financial triggers”—those moments when you are most likely to spend impulsively—and develop systems to mitigate them.
Furthermore, understanding the difference between “active” and “passive” financial mindsets is crucial. An active mindset focuses on the immediate paycheck and the next purchase. A passive, or compounding, mindset focuses on assets and cash flow. Experts generally agree that the greatest obstacle to personal finance success is not a lack of income, but the “lifestyle creep” that occurs when income increases. As you begin to earn more, the temptation to expand your lifestyle to match your salary is immense. The wealthy, however, keep their expenses steady while their income rises, directing the surplus toward wealth-generating assets. This is the core psychological shift required to grow wealth fast in relative terms, as it maximizes the delta between your income and your outgoings.
Developing resilience is also a critical part of this psychological journey. There will be market downturns, unexpected car repairs, and economic shifts that feel personal. If your mindset is tied strictly to market performance or the number in your bank account, you will likely panic and make poor decisions. Instead, anchor your psychology to your habits. If you can focus on the consistency of your savings rate and the wisdom of your spending choices, the macro-level fluctuations become noise. Wealth is ultimately a reflection of your character—your discipline, your foresight, and your ability to value long-term independence over the fleeting comfort of immediate status. By committing to this change in perspective, you move from being a passenger in your financial life to becoming the pilot.
Assessing Your Current Financial Baseline
You cannot reach a destination if you do not know your starting point. Assessing your current financial baseline is a sobering but necessary exercise in radical honesty. To begin, you must construct a comprehensive net worth statement. A net worth statement is simply a snapshot of everything you own (assets) minus everything you owe (liabilities). This is the only true scorecard of your financial health. When you start from zero, your net worth might be negative, and that is perfectly okay. Many people are intimidated by this number, but acknowledging it is the precise moment when you stop being a victim of your financial situation and start being a manager of it.
To calculate your baseline, list your assets in one column: cash in savings and checking accounts, retirement fund balances, equity in real estate, and the estimated resale value of significant personal property. In the second column, list your liabilities: credit card balances, student loans, car loans, and any personal debts. The difference between these two totals is your net worth. This figure provides the objective data required to set realistic goals. Without this number, any advice regarding how to build wealth is purely speculative. You need to see exactly where your capital is currently held—or where it is being drained.
Once your net worth is calculated, examine your cash flow statement. While your net worth tells you where you are, your cash flow tells you how you got there. Review your last three months of bank statements and credit card bills. Categorize every expense into two groups: “Fixed” and “Variable.” Fixed expenses are the non-negotiables that remain relatively steady, such as rent or mortgage payments, insurance premiums, and minimum debt payments. Variable expenses are where your wealth building potential is hidden—dining out, entertainment, subscriptions, and impulse shopping. This audit often reveals “financial leaks”—recurring charges for services you no longer use or habits that provide little genuine value to your life.
Comparing your current strategies is a useful exercise to determine which methods might best suit your temperament and income level. See the table below for a quick breakdown of how different approaches to baseline tracking can impact your focus.
| Approach | Focus Area | Best For |
|---|---|---|
| Manual Spreadsheets | Deep granularity and total control | Those who want to understand every cent |
| Automated Apps | Convenience and real-time alerts | Those who struggle with manual tracking |
| The “Envelope” Method | Strict physical cash management | Those prone to overspending on credit |
| Simplified Net Worth | High-level quarterly check-ins | Those who prefer big-picture growth |
After reviewing these figures, set your initial targets. These should be S.M.A.R.T. (Specific, Measurable, Achievable, Relevant, and Time-bound). For example, rather than saying “I want to save more,” commit to “I will increase my net worth by $500 this month through a combination of debt reduction and savings.” By documenting your baseline, you create a feedback loop that rewards progress. As you see your liabilities drop and your assets grow, the psychological momentum builds, making the next step significantly easier. Remember, this baseline is not a judgment on your past; it is the foundation upon which you will build your future financial independence.
Creating a Sustainable Monthly Budget
The term “budget” often evokes feelings of restriction, anxiety, and punishment. However, a sustainable budget is the most powerful tool in your arsenal. When you are looking to build wealth from nothing, a budget is not a cage; it is a permission slip to spend your money on the things that truly matter while systematically cutting out the waste. A well-designed budget provides the surplus income necessary to fuel your investments. Without one, your money tends to evaporate into small, unmemorable expenses. The goal is to reach a state of financial mindfulness where you are no longer wondering where your money went, but rather telling it exactly where to go.
There are several frameworks you can employ to create a budget that doesn’t feel like a chore. One popular method is the “50/30/20” rule, which suggests allocating 50% of your net income to needs, 30% to wants, and 20% to savings and debt repayment. While this is a helpful starting point, when you are in the aggressive wealth creation phase, you may find that you need to be more aggressive with your savings rate. If you are serious about fast-tracking your financial independence, you might choose to flip these ratios, aiming for a 50/10/40 split or something similar. The key is sustainability. If your budget is so restrictive that you burn out after two weeks, it will fail.
When drafting your budget, start with your “non-negotiables.” These are the costs required to maintain your living situation and your health. If these expenses consume too large a portion of your income, your first wealth-building strategy is to lower your cost of living. This might mean downsizing your apartment, refinancing high-interest debt, or canceling unnecessary subscription services. Often, the fastest way to increase your wealth-building capacity is not by increasing your income—which takes time—but by decreasing your fixed overhead, which can be done immediately.
Once your needs are covered, allocate your “wants” with intention. Wealth building is a marathon, and you need to incorporate rewards to stay consistent. If your budget includes a small, set amount for dining out or hobbies, you are less likely to experience the “binge-spending” cycle that occurs after long periods of extreme austerity. Transparency is also vital. Whether you share finances with a partner or are managing your budget alone, make the process visible. Use digital tools or a simple ledger to track your progress against your plan throughout the month. This constant visibility prevents the “head-in-the-sand” approach that leads to financial disarray.
Finally, treat your savings and investments as “bills.” When your paycheck hits your account, immediately transfer the designated amount toward your debt or your savings before you spend a single dollar on discretionary items. This is often called “paying yourself first.” By prioritizing this transfer, you ensure that wealth creation happens regardless of how the rest of the month unfolds. A sustainable budget is essentially a set of guardrails. It keeps you on the road toward financial independence even when life attempts to push you toward impulsive, wealth-eroding decisions. Over time, this practice becomes a habit, and you will find that managing your money becomes less of a mental burden and more of a source of confidence.
Prioritizing High-Interest Debt Elimination
High-interest debt is the silent killer of wealth. It is a mathematical anchor that prevents you from gaining any traction, regardless of how much money you earn. When you pay double-digit interest rates on credit cards or high-interest personal loans, you are effectively working to pay someone else’s wealth instead of building your own. In the hierarchy of personal finance tips, eliminating this type of debt should almost always take precedence over investing. Why? Because paying off a debt with an interest rate of 20% is mathematically equivalent to receiving a guaranteed, tax-free 20% return on your money. No investment in the public markets can reliably offer that kind of return, making debt destruction your highest-impact financial move.
To tackle debt effectively, you must first organize your liabilities by interest rate rather than by balance. This is known as the “Avalanche Method.” By focusing your surplus income on the debt with the highest interest rate while paying minimums on others, you save the most money over time and shorten the total time you spend in debt. Alternatively, some individuals find more motivation in the “Snowball Method,” where you pay off the smallest balance first to build momentum. While mathematically less efficient, the psychological win of clearing a debt entirely can provide the motivation needed to stay the course. Choose the method that best aligns with your psychology, but stay committed to the goal of debt elimination.
While you are aggressively paying down debt, you must also stop the bleeding. This means freezing your credit cards and, if necessary, switching to a debit or cash-only system. It is impossible to dig yourself out of a hole while you are still digging. You must commit to living on less than you earn. This is the hardest part for many, as it requires a temporary reduction in lifestyle comfort. You might have to say “no” to vacations, expensive dinners, or upgraded technology for a season. Remember, this is not a permanent state; it is a tactical retreat to secure a stronger financial future.
Communication can also be a powerful tool for debt elimination. If your interest rates are exceptionally high, reach out to your creditors. Many lenders are willing to lower interest rates if you have a history of on-time payments or if you can demonstrate genuine financial hardship. Additionally, consider looking into balance transfer options with lower introductory interest rates, provided you have the discipline to pay off the balance before the promotional period ends. However, be cautious; balance transfers are merely a tool for organization and interest savings, not a solution for overspending. If the underlying habit that led to the debt is not addressed, you will likely find yourself in the same position later.
Once your high-interest debt is cleared, the psychological shift is palpable. You are suddenly no longer paying for past consumption, allowing you to redirect those monthly payments toward assets that grow in value. This is the moment your wealth-building journey truly shifts from defensive to offensive. You are no longer fighting the gravity of compound interest; you are now using it as your greatest ally. Keep the records of your debt-free progress—perhaps a simple chart on your wall—to remind yourself of the freedom you have earned through discipline. You are now ready to build security.
Building an Emergency Fund for Security
Even if you have mastered your budget and eliminated your high-interest debt, life remains unpredictable. This is why building an emergency fund is a non-negotiable step in any sound wealth creation plan. An emergency fund is a bucket of liquid cash—typically kept in a high-yield savings account—that is reserved strictly for genuine, unforeseen events. We are talking about job loss, major medical expenses, or essential home and vehicle repairs. It is not for “good deals,” birthday presents, or last-minute travel. Without this safety net, one minor catastrophe can force you back into debt, undoing months or even years of hard-won progress.
How much do you need? While the conventional wisdom often suggests three to six months of living expenses, your specific number will depend on your risk tolerance, your job stability, and your family situation. If you are a freelancer with irregular income, you may want to aim for a larger buffer. If you have a stable job with a low cost of living, you might start with a smaller, more manageable goal. Start by aiming for a “starter emergency fund” of a fixed amount—perhaps $1,000 or one month of expenses—to handle the most likely small disasters. Once that is established, you can gradually grow the fund to your ideal, fully-funded target.
Where you keep this money matters as much as the amount itself. Your emergency fund must be liquid and easily accessible, but it should not be in your primary checking account where it is easily “spent” by accident. A separate online high-yield savings account is ideal. These accounts typically offer a better interest rate than a traditional brick-and-mortar bank, which helps your emergency fund lose less value to inflation, while the slight friction of having to transfer the money to your main account acts as a mental deterrent against using it for non-emergencies.
The true value of an emergency fund is not just the money; it is the peace of mind. When you know you have a buffer, you make better decisions. You are less likely to panic-sell investments when the stock market dips, and you are less likely to take a job you hate just because you need the immediate cash. This psychological security allows you to focus on long-term wealth building strategies with confidence. It allows you to take calculated risks in your career or business, knowing that you have a floor beneath your feet.
Treat the funding of this account as a high-priority financial goal. While it might seem counterintuitive to keep cash in a low-earning account when you are eager to invest, consider the emergency fund to be the “insurance premium” on your future wealth. By prioritizing security, you ensure that you can stay the course, no matter what happens in your personal life or the broader economy. It is the final piece of the structural foundation you need to build long-term wealth from zero. Once this fund is established, you are no longer just surviving—you are ready to start thriving.
Developing Multiple Income Streams
The foundation of wealth creation is rarely a single source of income. While a primary salary is the starting point for most people, relying on it entirely places a cap on your potential growth. To accelerate your journey toward financial independence, you must transition from a “linear income” mindset to a “diversified income” strategy. When you build multiple streams, you create a buffer against economic downturns and job insecurity, while simultaneously increasing the velocity at which you can funnel capital into wealth-building assets.
Diversification doesn’t mean spreading yourself thin. Instead, it means layering income sources that benefit from your existing skills or assets. Start by identifying your “secondary capacity.” This might involve freelancing, consulting, or creating digital products that leverage your professional expertise. Because these ventures often require high effort upfront but lower maintenance later, they represent the most accessible way to increase your monthly savings rate without needing to double your working hours.
Consider the concept of “leveraged income.” This occurs when you decouple your time from your earnings. Examples include intellectual property, such as writing an e-book, developing a software tool, or creating online courses. Unlike a standard hourly wage, these streams can earn revenue while you sleep, effectively multiplying your productivity. By reinvesting the profits from these secondary streams directly into your investment portfolio, you create a flywheel effect: your work buys assets, and those assets begin to generate their own returns, further subsidizing your lifestyle.
Furthermore, look for ways to monetize your existing assets. Many individuals overlook the potential for passive income through house hacking, renting out equipment, or earning dividends from fractional ownership in businesses. The goal is to turn “dead assets” into productive cash flow machines. When your passive income eventually covers your base expenses, you have reached the first major milestone of financial independence. From there, every additional dollar earned becomes a vehicle for pure wealth accumulation.
The Power of Compound Interest and Investing
If income streams are the fuel, compound interest is the engine. Albert Einstein is often credited with calling compound interest the “eighth wonder of the world,” and in the context of wealth building, this hyperbole is grounded in mathematical reality. Compound interest allows your money to grow exponentially because you earn returns not just on your initial investment, but on the accumulated interest or dividends from previous periods. Over long time horizons, the curve of wealth growth shifts from a gentle slope to a vertical climb.
To harness this power, you must adopt a “time in the market” philosophy. Timing the market is a futile game, even for professionals. Instead, consistency—investing a set amount of capital at regular intervals regardless of market fluctuations—is the proven path to building significant net worth. By staying invested through bull and bear markets, you benefit from the long-term upward trajectory of the global economy. This is particularly effective when utilizing tax-advantaged accounts, which allow your earnings to grow without the immediate drag of annual taxation.
Understanding asset allocation is the next step in optimizing these returns. Your portfolio should be balanced based on your risk tolerance and your “runway” until you reach your goal. Broad-market index funds and exchange-traded funds (ETFs) are often the preferred vehicles for retail investors because they offer immediate diversification and low fee structures. By owning a slice of the entire market, you eliminate the risk of picking a single losing stock and instead capture the collective growth of the world’s most innovative companies.
| Investment Vehicle | Typical Growth Potential | Liquidity | Best For |
|---|---|---|---|
| High-Yield Savings | Low | Very High | Emergency funds and short-term goals |
| Index Funds / ETFs | Moderate to High | High | Long-term retirement and wealth building |
| Real Estate | Moderate to High | Low | Tax advantages and cash flow |
| Individual Stocks | Variable | High | Aggressive growth for experienced investors |
Automating Your Financial Habits
Willpower is a finite resource. If you rely on the monthly discipline of manually transferring money to a savings account or researching investment picks, you will eventually fail. The most successful wealth builders rely on “financial automation” to remove human error and emotional decision-making from the equation. Automation turns the complex task of wealth creation into a background process that runs flawlessly without your intervention.
The strategy is simple: pay yourself first. Configure your payroll or banking interface so that a predetermined percentage of your income is automatically deposited into a high-yield savings account or a brokerage account the moment your paycheck arrives. When you treat your savings and investments like non-negotiable bills, you adjust your lifestyle to live on what remains. This forces “lifestyle creep” to stagnate even as your income rises, allowing you to maximize your capital allocation efficiency.
Additionally, automate your debt repayments. High-interest debt is an anchor on your net worth; by automating payments to exceed the minimum amount due, you ensure that you are aggressively chipping away at the principal. This systematic approach reduces the total interest paid over the life of the loan. Furthermore, set up automatic recurring contributions for your long-term investment accounts. By dollar-cost averaging—purchasing more shares when prices are low and fewer when they are high—you effectively smooth out the volatility of the market, reducing the stress associated with market swings.
Finally, perform a “digital audit” of your financial life at least once per quarter. While the daily execution should be automated, the oversight must remain human. Check in on your subscription services, audit your recurring bills to ensure you aren’t paying for unused utilities, and rebalance your portfolio if your asset allocation has drifted. Automation gets you to the goal, but your strategic oversight ensures you stay on the most efficient path.
Scaling Your Wealth Over the Long Term
As your wealth grows, the strategies you used to get from zero to your first milestone may need to evolve. Scaling wealth is about shifting your focus from “earning” to “preserving and compounding.” This involves moving into more sophisticated vehicles, such as tax-efficient investment structures or private assets that offer different risk-return profiles compared to public markets. At this stage, your primary job shifts from working for money to managing the risk of your existing capital.
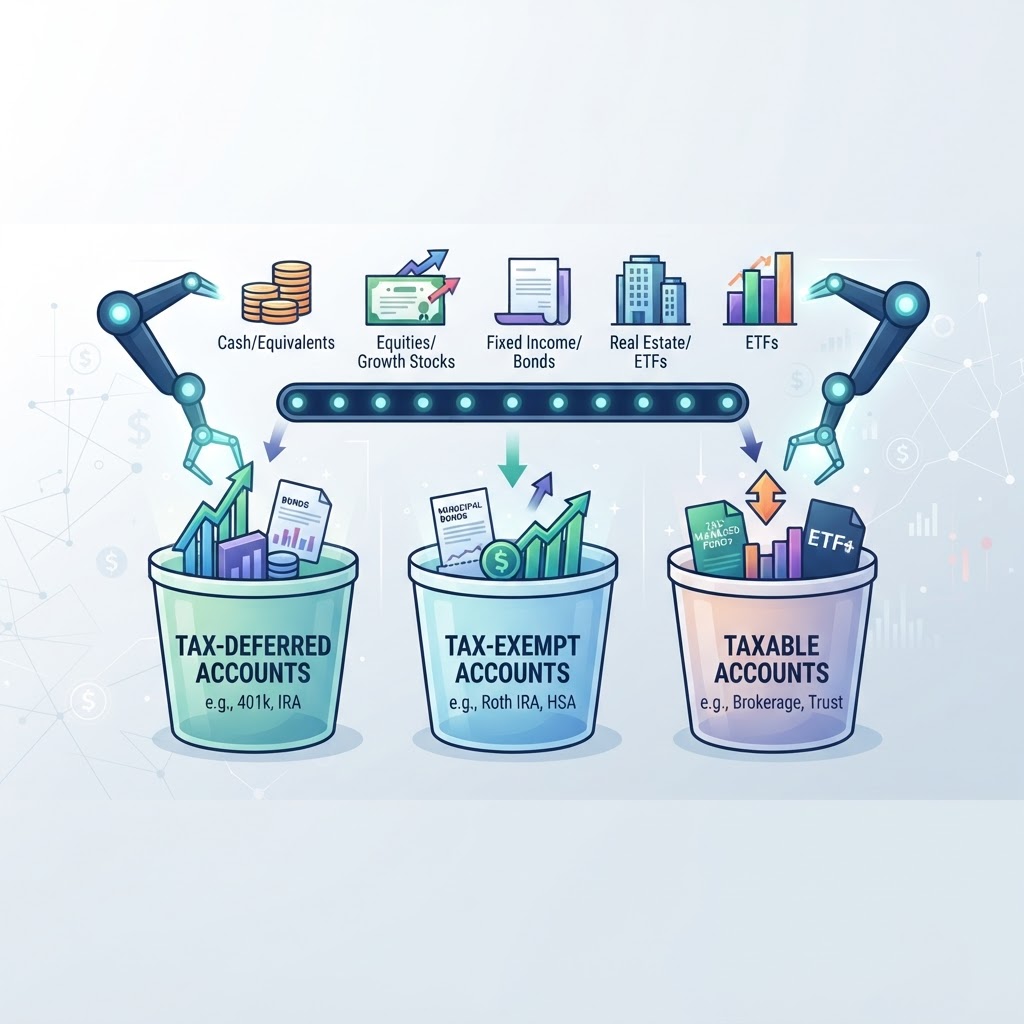
Tax management becomes increasingly important as your assets grow. In the early stages, taxes are a minor nuisance, but as your portfolio expands, they can become a significant drag on growth. Utilize tax-loss harvesting to offset capital gains, and prioritize tax-advantaged accounts. Work toward a structure where your money is held in a variety of buckets—tax-deferred, tax-free, and taxable—to give you maximum flexibility when you decide to transition from the accumulation phase to the distribution phase.
Scaling also involves protecting your downside. As your net worth increases, your potential exposure to liability also grows. This is the stage where you should consider umbrella insurance, estate planning, and a more robust approach to asset protection. Building wealth is a marathon, not a sprint, and protecting the capital you have already amassed is just as vital as seeking out new opportunities for gain. The ultimate goal is to reach a level of “financial velocity” where your portfolio generates sufficient returns to exceed both inflation and your desired standard of living.
Frequently Asked Questions
How much money do I need to start building wealth?
You can start with as little as five or ten dollars. Many modern brokerage platforms allow for fractional share investing, meaning you don’t need a large lump sum to enter the market. The most critical factor is the habit of consistency rather than the starting balance.
Is it possible to build wealth if I have significant debt?
Yes, but you must change your approach. Generally, experts recommend prioritizing the repayment of high-interest debt, such as credit cards, before aggressively pursuing long-term market investments. By eliminating high-interest liabilities, you effectively achieve a guaranteed “return” on your money equal to the interest rate you are no longer paying.
How long does it typically take to become wealthy?
Wealth building is a long-term endeavor that typically takes years or decades, depending on your income, savings rate, and market conditions. While “get rich quick” schemes are often predatory, a disciplined approach of saving and investing regularly can lead to significant financial independence over a standard career timeframe.
What is the most common mistake people make when starting?
The most common mistake is attempting to time the market or trying to pick “winning” stocks instead of investing in broad, diversified funds. Additionally, many people fall into the trap of increasing their spending immediately after getting a raise, which prevents them from increasing their savings rate.
Do I need a financial advisor to build wealth?
Not necessarily. For many individuals, low-cost index fund investing and automating finances is sufficient to build wealth effectively. However, as your financial situation becomes more complex—such as dealing with significant tax implications, business ownership, or complicated estate planning—a professional can provide valuable guidance.
What is the role of inflation in wealth creation?
Inflation is a constant force that reduces the purchasing power of cash over time. If your money is sitting in a traditional checking account with little to no interest, inflation is silently eroding your wealth. Investing is the primary method of growing your capital at a rate that outpaces inflation, preserving your future buying power.
Conclusion
Building wealth from nothing is not a matter of luck, secret knowledge, or having a high starting salary. It is a systematic process built on the pillars of aggressive saving, consistent investing, and the patience to let time do the heavy lifting. By moving away from short-term thinking and embracing the power of compound interest, you position yourself to move beyond the limitations of your current income and into a life of genuine financial security.
The hardest step is the first one. Whether it is opening a brokerage account, cutting your first non-essential expense, or automating your savings, taking action today is the only way to shift your financial trajectory. Your future self is waiting for you to make the commitment to long-term growth. Start today, stay the course, and watch as your small, consistent actions build a legacy of freedom.
By wealthsimplyput Editorial Team
This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.