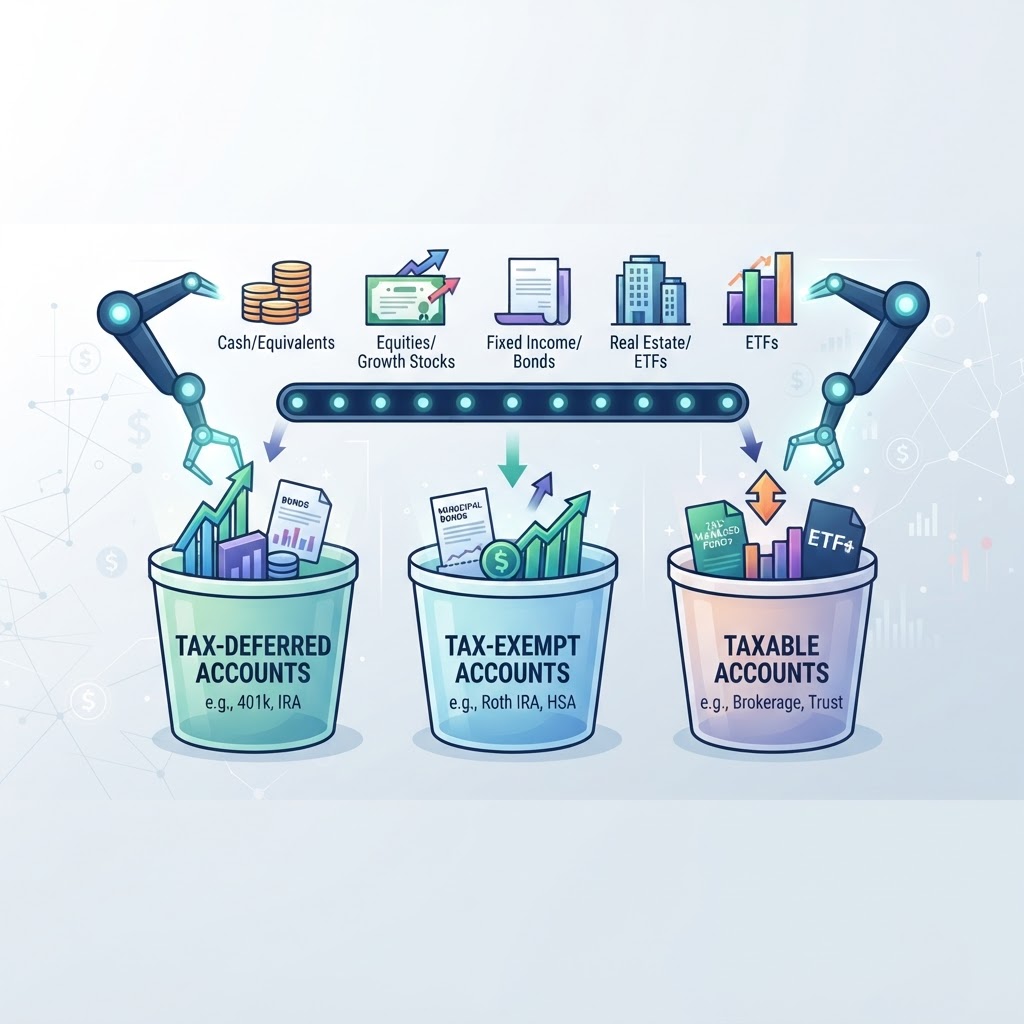
- Asset location is the deliberate strategy of placing specific investments into specific accounts to minimize tax drag.
- While asset allocation defines your risk profile, asset location optimizes the tax treatment of your returns to preserve more wealth.
- Tax-inefficient assets, such as high-yield bonds or actively managed funds, often perform best in tax-advantaged accounts like IRAs or 401(k)s.
- Taxable brokerage accounts are ideal for tax-efficient assets like index funds or ETFs that benefit from favorable long-term capital gains tax rates.
- Mastering asset location is a foundational wealth-building strategy that can significantly enhance your net after-tax returns over a long-term investment horizon.
Most investors spend the vast majority of their time choosing which stocks or funds to buy, often ignoring where those investments actually live. However, for those focused on serious wealth building, the question of where to keep your investments is just as vital as what you own. Taxes are often the single largest expense an investor faces, yet many people inadvertently leave money on the table by holding high-tax assets in the wrong account types. By utilizing a strategic approach to asset location, you can legally and systematically reduce your tax burden, ensuring that more of your money stays invested and compounding over time. This guide explores how to structure your portfolio to ensure your hard-earned wealth is working as efficiently as possible, regardless of market conditions.
What Is Asset Location and Why Does It Matter for Wealth?
Asset location is the strategic process of deciding which types of investments should be placed in which types of accounts—tax-advantaged (like a 401(k) or IRA) versus taxable brokerage accounts—to minimize your total tax liability. While many investors are familiar with “asset allocation” (the mix of stocks, bonds, and cash), asset location is the invisible engine that powers a tax-efficient portfolio. It is not about avoiding taxes permanently, but rather about deferring, reducing, or optimizing them to enhance your net after-tax returns.
The core philosophy behind this strategy is simple: not all investments are taxed the same way. Some investments generate high annual tax bills, while others are structured to grow with minimal interference from the IRS. If you place a “tax-heavy” investment in a taxable account, you are effectively choosing to pay a portion of your wealth to the government every single year. Over decades, this annual tax drag acts like a slow leak in a boat, significantly hindering your ability to accumulate wealth. Conversely, by strategically placing your assets, you can keep more money invested, allowing the power of compounding to work on the entirety of your principal rather than a diminished amount.
For high-net-worth individuals or those planning for a long-term retirement, asset location is a foundational element of wealth management. It requires an understanding of how dividends, interest, and capital gains are taxed. For example, interest income is typically taxed as ordinary income, which is often higher than the tax rate on qualified dividends or long-term capital gains. By understanding these nuances, an investor can “place” these assets where they will do the least amount of “damage” to the portfolio’s growth.
Furthermore, asset location is not a “set it and forget it” strategy; it evolves as your wealth grows and your tax situation changes. As you transition from the accumulation phase of your career to the distribution phase of retirement, your needs regarding account liquidity and tax efficiency may shift. However, the fundamental goal remains the same: to create a portfolio structure where the internal mechanics of your accounts work in harmony with your tax obligations. Ultimately, mastering asset location is about taking control of your financial ecosystem. It is an internal wealth-building strategy that requires no change to your underlying risk tolerance or market expectations, yet it can result in substantially higher wealth retention over the course of a lifetime.
Asset Location vs Asset Allocation: Understanding the Difference
It is a common point of confusion for new and experienced investors alike: how do asset allocation and asset location differ? While the terms sound nearly identical, they serve distinct purposes in your financial journey. Think of asset allocation as your “what” and asset location as your “where.”
Asset allocation is the process of dividing your portfolio among different asset categories, such as stocks, bonds, and cash. This is the primary driver of your risk and return. If you want a portfolio that can weather a stock market downturn, you might allocate 60% to stocks and 40% to bonds. This decision is based on your time horizon, financial goals, and personal risk tolerance. Asset allocation is about building a portfolio that aligns with your personality and your objectives; it determines the volatility you are willing to endure for a specific expected return.
Asset location, by contrast, is the tactical execution of that allocation. Once you decide you need 40% bonds, the question becomes: which account should those bonds live in? If you put all your bonds in a taxable brokerage account, you might be subjected to high annual taxes on the interest payments. If you instead move those bonds into a tax-advantaged account like a Traditional IRA, you can defer those taxes until you actually begin withdrawing the funds in retirement. Asset location does not change your overall exposure to stocks or bonds; it changes the tax environment in which those assets operate.
To put this into perspective, consider the following comparison table which helps illustrate how these concepts differ and where they fit into a broader tax-efficient investing strategy:
| Feature | Asset Allocation | Asset Location | Best For |
|---|---|---|---|
| Primary Focus | Risk and return profile | Tax efficiency of returns | Holistic wealth planning |
| Core Question | What do I own? | Where do I keep it? | Optimizing net wealth |
| Impact | Volatility management | Tax leakage reduction | Long-term growth |
The magic happens when you integrate these two strategies. You determine your ideal asset allocation first, and then you apply asset location principles to execute that allocation in the most tax-friendly manner possible. If you ignore asset location, you might have the perfect risk profile, but you will be paying higher costs than necessary in the form of taxes. If you focus only on asset location but lack an asset allocation strategy, you may end up with a tax-efficient portfolio that is far too risky or far too conservative for your actual needs. For the wealth-conscious investor, these two concepts must work in tandem to ensure that you are maximizing returns while maintaining the appropriate level of comfort with market fluctuations.
How Taxes Impact Your Investment Returns
To understand the necessity of asset location, one must first confront the reality of how taxes erode wealth. When you earn money in a taxable investment account, the IRS essentially becomes a silent, involuntary partner in your portfolio. Taxes on investments typically come in three primary forms: taxes on interest income, taxes on dividends, and taxes on capital gains.
Interest income, such as that generated by bonds, bank savings, or high-yield money market funds, is generally taxed as ordinary income. In many jurisdictions, this can be the highest rate you pay—the same rate applied to your regular salary. Because this interest is taxed in the year it is earned, you are forced to pay the tax bill immediately, which removes a portion of the interest from your account. This effectively lowers the compound interest rate you receive, as you have less capital remaining in the account to earn interest the following year. Over a 20- or 30-year period, this “tax drag” can reduce the final value of your portfolio by a significant margin.
Dividends also represent a common tax friction. Qualified dividends are taxed at more favorable long-term capital gains rates, which is better than the ordinary income tax bracket. However, non-qualified dividends are taxed as ordinary income. If you hold a high-dividend-paying investment in a taxable account, you will receive a 1099-DIV form every year, and you will be required to settle your tax liability annually. This is a recurring drain on your portfolio’s growth potential.
Capital gains occur when you sell an asset for more than you paid for it. The beauty of capital gains tax is that it is typically deferred until you decide to sell the asset. This allows you to control exactly when you trigger the tax event. By holding onto appreciating assets in a taxable account, you are effectively allowing the government’s share of your growth to continue growing for your benefit until the moment of sale. This is why many long-term wealth builders prefer assets that appreciate in value (like growth stocks or broad market index funds) rather than assets that produce high annual cash flows (like bonds or high-yield funds) in their taxable brokerage accounts.
The impact of taxes is often invisible because it happens behind the scenes. You rarely see a line item labeled “wealth reduction due to taxes” on your brokerage statement, but it is there, embedded in the difference between your gross returns and your net-of-tax returns. Even a small tax drag—say, 1% per year—can compound into a significant loss of wealth over time. By becoming intentional about tax-efficient investing, you are essentially giving yourself a raise. Every dollar you save on taxes through smart asset location is a dollar that stays invested and contributes to your total wealth.
Where to Hold Tax-Inefficient Investments Like Bonds
Now that we have established that taxes are a major hurdle to wealth accumulation, we must address the “where” of your specific holdings. Some assets are inherently “tax-inefficient,” meaning they produce a steady stream of income that triggers tax events on a frequent basis. Bonds and fixed-income securities are the most common examples. Because bonds pay interest (coupon payments) on a regular schedule, and because that interest is typically taxed as ordinary income, they are rarely the best candidates for a taxable brokerage account.
If you hold a significant allocation of bonds, the most logical place for them is a tax-advantaged account, such as a 401(k), 403(b), or Traditional IRA. In these accounts, interest payments accumulate without triggering an immediate tax bill. You do not pay taxes on the interest in the year it is earned; you only pay taxes when you withdraw the money during retirement. This allows your bond holdings to compound at their full, pre-tax rate, which can lead to a much larger end balance over long periods.
For those who have reached the limits of their tax-advantaged accounts and must hold bonds in a taxable account, there are alternative strategies. One such option is to use municipal bonds. In many regions, interest earned from municipal bonds is exempt from federal income tax and, in some cases, state and local taxes as well. While the nominal interest rate on municipal bonds might be lower than that of corporate or government bonds, the “tax-equivalent yield” can often be much higher for investors in high tax brackets.
Actively managed funds are another category of investment that can be quite tax-inefficient. These funds often engage in frequent buying and selling of securities, which can trigger capital gains distributions that you are forced to pay taxes on, even if you haven’t sold a single share of the fund yourself. If you are determined to hold actively managed strategies, doing so within a tax-advantaged structure is usually the preferred method. This shields you from the “phantom” taxes caused by the internal turnover of the fund manager’s portfolio.
In short, if an investment produces “tax noise”—recurring interest, frequent capital gains distributions, or ordinary income payouts—it should be prioritized for your tax-sheltered accounts. By creating this separation, you keep your taxable account clean, focused on long-term appreciation, and relatively easy to manage during tax season. This approach requires some coordination, especially when you have multiple accounts, but it is one of the most effective ways to preserve wealth against the erosion caused by annual taxation.
The Best Assets to Keep in Your Taxable Brokerage Accounts
If tax-inefficient assets belong in tax-advantaged accounts, then the inverse is true for your taxable brokerage accounts. Your taxable account should be a “sanctuary” for assets that are tax-efficient—those that minimize annual tax events and allow you to take full advantage of long-term capital gains rates. This is where you want to keep the core of your wealth-building engine: tax-efficient index funds, exchange-traded funds (ETFs), and individual stocks held for the long haul.
Broad market index funds and ETFs are excellent candidates for taxable accounts. Because they are designed to track an index, their internal turnover is typically very low. They do not frequently sell underlying stocks, which means they rarely distribute capital gains. They simply hold the basket of companies and grow in value over time. When you eventually decide to sell your position, you will be taxed at the long-term capital gains rate—which is almost always lower than the ordinary income tax rate—and only on the profit you have made. This gives you significant control over your tax bill.
Individual growth stocks are another prime example of assets that belong in taxable accounts. Many growth-oriented companies do not pay dividends, choosing instead to reinvest their profits into the business to fuel further expansion. Because there is no dividend payment, there is no taxable income generated. You own the asset, it grows in value, and you pay zero taxes until you choose to liquidate. This is the definition of a tax-deferred wealth builder. By holding these stocks in a taxable brokerage account, you are effectively using the account as a tax-deferral vehicle, mirroring the benefits of a retirement account without the strict withdrawal constraints.
Tax-managed funds are also an option for taxable accounts. These are specialized funds specifically designed by investment firms to minimize the tax impact on the investor. They may use techniques like tax-loss harvesting—selling losing positions to offset capital gains elsewhere in the portfolio—to keep your tax bill as close to zero as possible. If you are a high-income earner, a tax-managed fund can be a powerful tool for maintaining a growth-oriented portfolio while minimizing the friction caused by taxes.
As you build your taxable brokerage account, keep it simple. Avoid assets that churn out constant interest or high-turnover dividends. Your goal for this account is to participate in the growth of the economy with as little “leaking” of your gains to the tax collector as possible. When you hold these assets for years or even decades, you aren’t just earning returns on your money; you are earning returns on the money that would have otherwise been sent to the IRS in the form of annual taxes. This is the essence of compounding at its most powerful, and it is the standard by which all serious wealth builders should structure their taxable accounts.
Maximizing Tax-Advantaged Space for High-Growth Assets
When curating a tax-efficient portfolio, the ultimate goal is to minimize the “tax drag” on your wealth-building strategies. A critical component of this is identifying which assets have the highest potential for long-term appreciation and ensuring they are housed in accounts that shelter them from annual tax reporting. High-growth assets, such as small-cap stocks or aggressive equity index funds, are prime candidates for your tax-advantaged space, such as Roth IRAs or 401(k)s.
Why prioritize high-growth assets in tax-sheltered environments? Because compounding is the engine of wealth, but taxes act as a friction-inducing brake. If you hold an asset that is expected to double or triple in value over the next two decades, the tax-free growth provided by a Roth account ensures that 100% of that expansion remains in your pocket. Conversely, if that same asset were in a taxable brokerage account, you would eventually face capital gains taxes upon selling, which can meaningfully erode the final result of your long-term compounding.
To maximize this space, investors should audit their current holdings to determine which percentage of their portfolio consists of high-growth vehicles. If your tax-advantaged accounts are limited in size, prioritize the assets that you believe will have the highest total return. This strategy, often referred to as “tax-aware growth allocation,” forces you to be disciplined about where you place your most aggressive bets. By keeping these assets in IRAs or 401(k)s, you effectively shield the largest portion of your future wealth from the IRS.
Handling REITs and Commodities in Your Portfolio
Real Estate Investment Trusts (REITs) and commodity-linked assets present unique challenges for tax-efficient investing. Unlike standard stocks that provide qualified dividends, REITs typically pay out distributions that are classified as ordinary income. Because ordinary income is often taxed at your highest marginal tax rate, placing REITs in a taxable account can be inefficient. For many investors, sheltering REITs in a tax-deferred account is a standard best practice to prevent that high annual tax bill from undermining your broader wealth goals.
Commodities, on the other hand, are often held through Exchange-Traded Funds (ETFs) or Exchange-Traded Notes (ETNs) that may utilize complex structures. Some commodity-linked investments issue K-1 tax forms, which add a layer of complexity to your annual tax filings. Furthermore, certain commodity futures-based funds are taxed according to the “60/40 rule” in the United States, where a portion of the gains are taxed at long-term rates and others at short-term rates, regardless of holding period. Due to this complexity and the potential for unfavorable tax treatment, these assets are frequently better suited for tax-advantaged accounts where the internal tax reporting is simplified or deferred until withdrawal.
| Asset Class | Tax Profile | Best For |
|---|---|---|
| Equity Index Funds | Qualified dividends/Long-term gains | Taxable Accounts |
| REITs | Ordinary income (high tax burden) | Tax-Advantaged (IRA/401k) |
| Municipal Bonds | Generally tax-exempt | Taxable Accounts |
| Commodities/Futures | Complex (often 60/40 rule) | Tax-Advantaged (IRA/401k) |
| High-Yield Corporate Bonds | Ordinary income | Tax-Advantaged (IRA/401k) |
How to Transition Your Portfolio Without Triggering Capital Gains
Transitioning an existing, tax-inefficient portfolio to a more optimized structure can feel daunting. Many investors fear that the process of moving assets—selling them in a taxable account to re-purchase them elsewhere—will trigger a massive tax bill that negates the benefits of the move. However, you can manage this transition strategically using several common techniques.
First, utilize the “drift” method. Instead of selling all your current holdings at once, simply direct all new contributions to the assets you want to hold in your taxable account. If you need to rebalance, use your dividends or new cash injections to buy the desired tax-efficient assets, rather than selling the ones you already own. Over time, your asset location will align with your goals through organic growth and new capital rather than forced liquidations.
Second, consider the concept of “tax-loss harvesting.” If you have assets that have depreciated, you can sell them to realize a loss, which can then be used to offset capital gains from other sales. This creates a “tax-neutral” window to reorganize your portfolio. Finally, prioritize moves within your tax-advantaged accounts. You can trade as often as you like inside an IRA or 401(k) without any immediate tax consequences. Start by optimizing the assets within those accounts first, and leave the taxable account transition for when you have enough harvested losses to cover the exit costs.
Common Asset Location Mistakes That Drain Your Returns
Even seasoned investors fall prey to common pitfalls that can quietly diminish their wealth over time. The most frequent error is “mental accounting,” where an investor treats all accounts as having equal tax weight. This leads them to hold high-turnover, tax-inefficient mutual funds in a standard brokerage account, resulting in high annual tax bills that significantly lower their net-of-tax return.
Another common mistake is failing to account for the impact of dividends. Investors often focus on price appreciation but forget that dividends are taxable events in brokerage accounts. Holding high-dividend stocks or bond funds in a taxable account creates a “tax leak” every single year, preventing that money from compounding. Conversely, some investors try to be “too perfect” and move assets around so frequently that they trigger short-term capital gains taxes, which are taxed at higher rates than long-term gains. Tax-efficient investing is a long game; over-optimization can be just as damaging as under-optimization.
Finally, there is the mistake of ignoring state taxes. While many people focus on federal brackets, high-state-income-tax residents often benefit from using municipal bonds or other state-specific tax shelters. Ignoring the state-level impact of your asset location choices can mean missing out on significant, year-over-year savings that would otherwise contribute to your long-term wealth.
Frequently Asked Questions
Is tax-efficient asset location more important than asset allocation?
Asset allocation—the mix of stocks, bonds, and cash—is generally considered the primary driver of portfolio risk and return. Asset location is a secondary strategy used to improve the efficiency of that allocation. While location can add value by reducing tax drag, it should never come at the expense of your fundamental risk profile or investment strategy.
Can I achieve tax-efficient investing without a financial advisor?
Yes, many self-directed investors successfully manage their own asset location by following clear, consistent rules. By keeping tax-inefficient investments in sheltered accounts and low-turnover, tax-efficient assets in brokerage accounts, you can replicate professional-level efficiency. However, if your tax situation is complex due to business ownership, stock options, or multi-state residency, consulting a professional may be warranted.
What is the “tax drag” and how does it impact wealth?
Tax drag refers to the reduction in an investment’s annual return due to the taxes paid on dividends, interest, or capital gains. Over decades, even a small amount of tax drag can have a significant negative impact on the power of compounding. Minimizing this drag is a fundamental pillar of long-term wealth building.
Do I need to rebalance my portfolio annually for tax reasons?
You should rebalance when your asset allocation deviates from your target, but you should do so tax-consciously. Rather than selling assets in taxable accounts, try to rebalance by adjusting where you direct new contributions or by exchanging funds within your tax-advantaged accounts. This allows you to maintain your target risk level without creating unnecessary taxable events.
Are ETFs always more tax-efficient than mutual funds?
Generally, ETFs are more tax-efficient than traditional mutual funds due to their unique “in-kind” creation and redemption process, which often minimizes capital gains distributions to shareholders. However, this is not a hard-and-fast rule; some mutual funds are highly tax-efficient, and some ETFs are not. Always review the tax distribution history of a specific fund before investing.
Should I prioritize paying off debt or optimizing asset location?
This depends on your interest rates and expected investment returns. If your debt has a very high interest rate, paying it off usually provides a guaranteed “return” that beats most market investments. Once high-interest debt is managed, you can focus on optimizing your asset location to accelerate wealth accumulation through tax efficiency.
Conclusion
Mastering tax-efficient asset location is one of the most effective ways to tip the scales in your favor when building long-term wealth. By recognizing the unique tax profiles of your investments and mapping them to the most appropriate account types, you transform your portfolio from a taxable burden into a streamlined machine designed for compound growth. While the nuances of REITs, commodities, and capital gains may seem complex, the principles of keeping tax-inefficient assets sheltered and tax-friendly assets in taxable accounts remain the gold standard for savvy investors.
Do not let the complexity of taxes paralyze your progress. Start by auditing your current holdings, move toward your target location gradually, and remain consistent with your strategy. Your future self will thank you for the extra wealth captured simply by paying attention to where your money lives. If you are ready to take control of your financial destiny, start by reviewing your brokerage and retirement statements today to ensure your assets are positioned for maximum efficiency.
By wealthsimplyput Editorial Team
This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
Leave a Reply