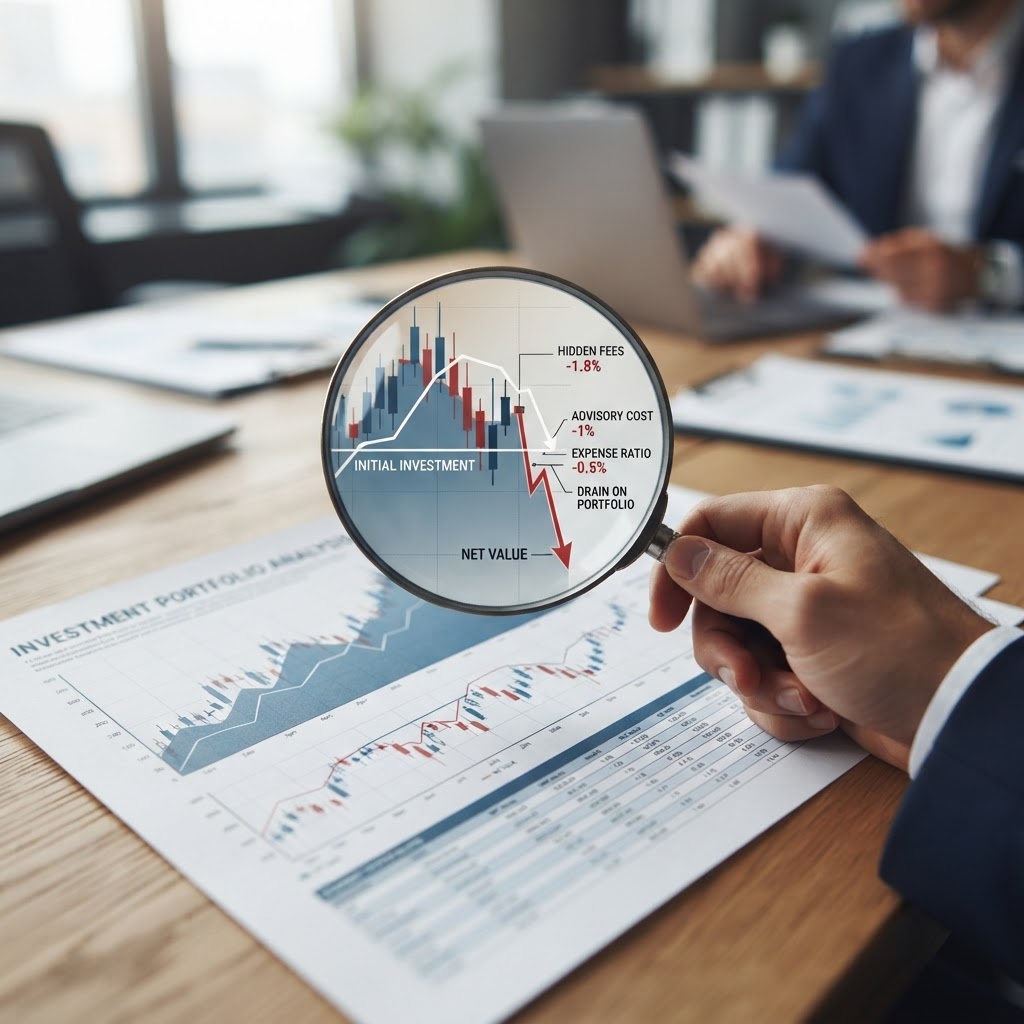
- Investment fees act as a silent drag on your returns, potentially eroding a significant portion of your lifetime wealth.
- Expense ratios represent the annual operational cost of a fund and are directly deducted from your investment performance.
- Passive index investing generally offers lower investment costs compared to actively managed portfolios.
- Small differences in percentage fees, when compounded over decades, can result in tens or even hundreds of thousands of dollars in lost gains.
- Understanding how to audit and minimize your portfolio costs is one of the most effective ways to accelerate your wealth building journey.
When you start your journey toward financial independence, you likely focus on the big-picture variables: which stocks to pick, how much to save each month, and when to retire. Yet, there is a quiet, persistent force working against your efforts every single day. Investment fees are not merely a minor nuisance; they are a structural component of the financial industry that can quietly decimate your wealth if left unchecked. Many investors view these costs as inevitable, a simple “cost of doing business” in the market. However, those who treat these expenses as avoidable barriers to success often find themselves with significantly more capital when they reach their goals. To truly master the art of wealth building, one must look past the flashy promises of high-performing funds and confront the math of drag. By minimizing your investment costs, you ensure that more of your money stays in the market, working for you rather than for the intermediaries managing your assets.
Understanding the Impact of Investment Fees on Long-Term Wealth
The impact of investment fees on long-term wealth is one of the most underappreciated aspects of personal finance. Because these fees are rarely charged as a separate bill—they are typically deducted directly from the net asset value of a fund—most investors never “see” the money leaving their accounts. This invisibility makes them dangerous. When you pay a mortgage or a car payment, you feel the cash leave your bank account, which triggers a natural desire to keep those costs low. With investment costs, the loss is realized as a slightly lower performance figure, which can easily be mistaken for poor market conditions rather than the silent consumption of your principal.
Consider the compounding effect of time. Wealth building is essentially a game of exponential growth. When you pay a fee today, you aren’t just losing that specific dollar amount; you are losing the future growth that dollar would have generated over the next twenty, thirty, or forty years. If a portfolio grows at a certain rate, a seemingly small fee percentage can actually siphon off a large chunk of your final nest egg. For example, over a forty-year career, the difference between a low-cost portfolio and a high-cost portfolio can result in a final balance that is vastly different, despite both portfolios theoretically starting with the same contributions and underlying market exposure.
Many investors mistakenly assume that higher fees correlate with better performance, believing that if they pay a premium, a professional manager will “beat the market” for them. However, historical data often suggests that high fees are more reflective of overhead, marketing, and profit margins than they are of superior investment skill. Wealth management firms must balance their own profitability with the needs of the client, and unfortunately, fees are a primary lever for their revenue. As a result, the burden of proof is on the investor to be vigilant. By prioritizing lower investment costs, you effectively give yourself an immediate “raise” on your returns. This isn’t about being stingy; it is about being efficient. A rational investor understands that they cannot control market volatility, but they can exert total control over the costs they pay to access that market. Taking this control is the first step toward reclaiming your future wealth.
What Are Expense Ratios and Why Do They Matter?
At the heart of the fee structure lies the expense ratio. This figure represents the percentage of your total investment that is deducted annually to cover the fund’s operating expenses. These expenses include management fees, administrative costs, legal fees, and marketing costs—often referred to as 12b-1 fees in the context of mutual fund expenses. If you hold $10,000 in a fund with an expense ratio of 1.00%, you are essentially paying $100 per year for the privilege of holding that investment. While $100 may seem trivial, it is a recurring charge that persists regardless of whether the market goes up or down. If the market is flat for a year, your account balance will still drop by that 1% fee.
Expense ratios are critical because they are the most transparent and comparable metric available to retail investors. While other fees might be obscured in the fine print of a prospectus, the expense ratio is required to be clearly disclosed. It acts as the “unit price” of the investment management services you are receiving. Understanding this ratio allows you to make apples-to-apples comparisons between competing products. For instance, if you are choosing between two funds that track the exact same index, the only meaningful difference in your net outcome will often be the expense ratio. In this scenario, the fund with the lower expense ratio will always outperform the other over time, provided the tracking error is similar.
Why does a seemingly small percentage matter so much? Because wealth building is a marathon. A fund charging 1.5% annually might seem reasonable compared to one charging 2%, but over a long horizon, that 0.5% difference can equate to thousands of dollars in foregone compound interest. Investors must move away from the idea that they are paying for “service” and recognize that they are paying for a commodity—market exposure. In the modern era, high-quality, low-cost index funds have commoditized the process of asset allocation. Paying more for that commodity rarely yields better long-term results. By focusing on expense ratios, you are effectively filtering out inefficient products that act as a drag on your performance. The best investors treat every basis point of their expense ratio as a variable they can manage, aiming to keep these costs as low as possible to maximize the growth of their invested capital.
Hidden Costs: Transaction Fees, Loads, and Account Management Fees
While the expense ratio is the most visible cost, it is far from the only one. Many investors are surprised by the variety of “hidden” costs that can permeate their brokerage or retirement accounts. These costs act as additional layers of friction, siphoning away potential wealth before it has a chance to compound. One of the most outdated yet still prevalent costs is the “load.” A load is a sales commission paid to the broker or advisor who sells the fund. A “front-end load” is deducted from your investment the moment you buy, meaning if you invest $1,000 with a 5% load, only $950 actually enters the market. You are immediately in a hole of $50, which you then have to earn back just to get to break-even.
Transaction fees are another area where costs can sneak up on you. Many brokerage platforms charge a fee every time you buy or sell a specific stock or fund, especially if those funds are outside of the broker’s “no-transaction-fee” network. If you are a habitual rebalancer or a frequent trader, these individual transaction fees can add up to a significant percentage of your annual contributions. Furthermore, there are often account maintenance or administrative fees charged by plan providers, particularly within 401(k) plans or managed portfolios. These fees might be presented as a flat annual rate or a tiered percentage of total assets, which can feel less significant to a new investor but can be substantial as your total wealth grows over time.
Then there is the concept of “soft dollars” and execution costs. When a fund manager trades assets, they pay commissions to brokers to execute those trades. These costs are often embedded in the turnover of the fund. High turnover funds—those that buy and sell assets frequently—incur higher trading costs, which are ultimately borne by you, the investor. This is often not reflected in the published expense ratio, creating a discrepancy between the stated fee and the real-world impact on your returns. To navigate this, savvy investors look for low-turnover, buy-and-hold strategies that minimize these underlying trading frictions. The goal is to maximize transparency. When you understand exactly where your money is going—whether it’s a direct fee, a load, or a hidden commission—you can make informed decisions about whether the cost is truly providing you with commensurate value or if it’s simply eroding your potential wealth.
| Investment Approach | Cost Profile | Best For |
|---|---|---|
| Passive Index Funds | Very Low | Long-term wealth builders seeking simplicity and efficiency. |
| Actively Managed Funds | High | Niche investors with specific, non-market-cap goals. |
| Robo-Advisors | Low to Moderate | Beginners wanting automation and tax-loss harvesting. |
| Full-Service Financial Advisors | High (AUM-based) | High-net-worth individuals needing complex estate planning. |
The True Cost of Active Management vs Passive Index Investing
The debate between active management and passive index investing is essentially a debate over whether the added costs of “expert” intervention are worth the potential for outperformance. Active management involves hiring a portfolio manager to hand-select stocks or time the market, hoping to achieve returns that exceed a benchmark index like the S&P 500. This approach requires extensive research teams, high turnover of securities, and significant marketing budgets. These costs must be passed on to the investor, typically resulting in expense ratios that are significantly higher than those found in passive index funds.
Passive index investing, by contrast, seeks to replicate the performance of a market index as cheaply as possible. Because there is no need for high-salaried stock pickers or frequent, costly trading, these funds can operate with razor-thin margins. The philosophy here is that the market is largely efficient, and over the long term, it is statistically improbable for the majority of active managers to outperform the market after accounting for their higher fees and taxes. Wealth building becomes a game of capturing the “market return” rather than chasing a “manager alpha” that may not actually exist or persist.
When you weigh these two approaches, the “true cost” is not just the expense ratio; it is the opportunity cost of underperformance. If an active fund charges 1.2% per year and underperforms the market by 0.5% due to poor selection, your total annual “wealth drag” is 1.7%. Over thirty years, that drag can reduce your final portfolio size by a staggering percentage. Many proponents of active management point to periods of market volatility where a human manager might “protect” the downside, but data consistently shows that human emotions often lead to the same errors that passive investors avoid—selling low during panics or chasing trends at the top. Passive index funds eliminate the risk of manager error, ensuring that your investment costs remain low and predictable regardless of market conditions. For the vast majority of investors, minimizing investment costs through passive vehicles is not just a strategy for saving money—it is the most reliable strategy for actually reaching their long-term wealth goals.
How to Calculate the Real Annual Cost of Your Investment Portfolio
To truly take control of your financial future, you must be able to calculate the real annual cost of your investment portfolio. Many people look at their brokerage statements and see a “gain” or “loss,” but they fail to look at the “internal” performance of the investments themselves. Calculating your total cost requires more than just noting your expense ratios. You need a comprehensive view of how much you are losing to the friction of the financial industry. The first step is to create an itemized list of all your holdings, their current values, and their individual expense ratios. Multiply the value of each holding by its expense ratio to get the dollar amount you are paying for that specific asset annually.
Next, account for the non-fee costs that we discussed earlier. If you pay a flat annual fee to a robo-advisor or a percentage-based fee to a wealth management firm, that must be added to your total. Don’t forget to estimate your annual transaction costs. If you know how many trades you executed over the past year and the commission rate per trade, add that total to your tally. If your 401(k) provider charges a fixed administrative fee per month, include that as well. Once you have a total dollar amount, divide it by your total account balance. This gives you your “all-in” annual cost percentage.
You may be shocked by the result. If your all-in cost is 1.5% or higher, you are effectively working a significant portion of your year just to pay the financial services industry. Compare this number to a benchmark of, say, 0.20% or less, which is easily achievable today using broad-market, low-cost index funds. The difference between your current cost and this efficient benchmark is the “wealth gap” you are losing every year. Once you have this number in front of you, the path forward becomes clear. It is time to audit your portfolio. Are there lower-cost alternatives that track the same indices? Are there unnecessary accounts that carry maintenance fees? By rigorously calculating your costs, you transform from a passive consumer of financial products into an active manager of your own wealth. This awareness is the final barrier between those who struggle to build wealth and those who systematically secure it.
Common Investment Fee Mistakes That Cost Investors Thousands
Many investors mistakenly believe that higher fees correlate with superior investment performance. This psychological trap, often fueled by aggressive marketing from high-cost fund managers, leads to common errors that erode long-term wealth. Understanding these pitfalls is the first step toward reclaiming your financial future.
One of the most damaging mistakes is the “Set It and Forget It” syndrome regarding legacy investments. An investor might purchase a mutual fund twenty years ago that seemed appropriate at the time but has since become bloated with excessive management fees. Because these costs are deducted directly from the fund’s net asset value, they are invisible to the investor. You do not receive a monthly invoice for these fees, so it is easy to assume they are non-existent. This complacency allows high expense ratios to silently strip away a significant portion of your portfolio’s annual gains.
Another frequent error is failing to account for “hidden” costs, such as 12b-1 fees and high portfolio turnover. Many actively managed funds incur significant transaction costs as managers frequently buy and sell assets. While the fund’s prospectus might highlight a modest expense ratio, the hidden trading costs and tax inefficiencies often result in a much higher “all-in” cost. When you add the impact of these transaction costs to the base management fee, the total drag on your performance can be substantial.
Additionally, many investors fall victim to the “churning” of their accounts. This occurs when an advisor recommends moving money between different funds frequently. While this might be masked as “rebalancing” or “strategic shifting,” it often triggers unnecessary transaction fees and capital gains taxes. The cumulative effect of these small, recurring costs is a massive reduction in the compounding potential of your wealth.
How to Find and Evaluate Expense Ratios Before You Buy
The expense ratio is perhaps the most important metric when evaluating a fund. It represents the annual percentage of your assets that the fund management team keeps for operating expenses. Fortunately, these are disclosed in mandatory documents that are publicly available.
To find the expense ratio, you should always consult the fund’s official **Prospectus** or the **Summary Prospectus**. These documents are easily accessible through your brokerage platform or the fund company’s website. Look for a section explicitly titled “Fees and Expenses.” It will typically break down management fees, distribution fees (12b-1), and other administrative costs.
Evaluating these costs requires context. A fund that charges 0.50% might seem cheap compared to a fund charging 1.50%, but if that 0.50% fund is a standard index fund, it may actually be overpriced by industry standards. Today, many broad-market index funds and exchange-traded funds (ETFs) carry expense ratios in the very low double-digit basis points. When comparing, always categorize the fund’s objective first—do not compare the expenses of an actively managed specialty sector fund against a passive total stock market index fund, as their operational requirements differ.
Consider using an “all-in” cost calculator. Many online financial platforms provide tools that allow you to input the ticker symbol and your investment amount to estimate exactly how much you will pay in fees over a 10 or 20-year horizon. Visualizing the dollar amount—rather than just a small percentage—is often the catalyst investors need to prioritize cost-efficiency.
| Investment Vehicle | Typical Fee Structure | Operational Efficiency | Best for |
|---|---|---|---|
| Passive Index Fund | Very Low | High | Long-term wealth building |
| Active Mutual Fund | High | Variable/Low | Niche sector exposure |
| Exchange-Traded Fund (ETF) | Low | High | Tax-efficient, intraday trading |
| Robo-Advisor | Moderate | High | Hands-off automated investing |
Strategies for Negotiating or Avoiding Unnecessary Financial Advisor Fees
Financial advice can be a tremendous asset, but it must be structured in a way that aligns the advisor’s interests with your own. Many investors unknowingly pay a percentage of their assets under management (AUM) indefinitely, even if they only need one-time planning services.
One strategy is to shift toward a “fee-only” advisor who charges an hourly rate or a flat project-based fee. By paying for specific services—such as a comprehensive portfolio review, tax strategy, or retirement income planning—you avoid the ongoing “drag” of a percentage-based fee that grows as your wealth grows. A percentage fee might seem small, but as your portfolio scales into the hundreds of thousands or millions, the dollar amount paid annually can become excessive for the actual work being performed.
If you prefer an advisor to manage your investments, ask for transparency regarding “hidden” fees. Some advisors use “wrap fee” programs where the fee covers both management and trading costs. While convenient, these are often more expensive than a simple commission-based or fee-only arrangement. Always ask your advisor: “What is the total cost I am paying including all fund-level expense ratios and platform fees?” If they cannot provide a clear answer, it is a significant red flag.
Finally, consider a hybrid approach. You may handle the core of your investment portfolio yourself using low-cost index funds, while paying an advisor a flat fee for periodic check-ins or complex tax and estate planning. This ensures you keep the vast majority of your investment growth while still benefiting from professional guidance on high-level financial strategy.
Compounding Losses: How High Fees Delay Your Financial Independence
The relationship between investment fees and time is one of the most cruel mathematical realities in finance. Compound interest is often called the “eighth wonder of the world” because it allows your wealth to grow exponentially. However, high fees act as a negative compounder. They do not just take a small cut of your balance each year; they take away the *growth* that money would have generated in all subsequent years.
Imagine you have a portfolio growing at an average annual rate of 7%. If you pay a 1% fee, your net return is 6%. If you pay a 2% fee, your net return is 5%. Over the course of 30 years, that 1% difference in fees can result in a portfolio balance that is tens of thousands—or even hundreds of thousands—of dollars smaller than it would have been otherwise. This is not just lost profit; it is lost time. It means you must work longer, save more aggressively, or settle for a smaller retirement lifestyle.
The “cost of delay” is effectively a tax on your future self. Every dollar paid in unnecessary fees is a dollar that cannot be reinvested to earn its own returns. When you minimize investment costs, you are not just saving money today; you are accelerating the timeline to your financial independence. By reducing your expense ratios, you keep more capital inside the market, allowing the engine of compound interest to work at its maximum capacity.
Building a Fee-Efficient Portfolio for Maximum Wealth Growth
Building a fee-efficient portfolio starts with a commitment to simplicity. The more complex an investment strategy becomes, the higher the likelihood of layering on unnecessary costs. A portfolio built on broad-market, low-cost index funds or ETFs is typically the most efficient path for the majority of long-term investors.
Start by identifying your asset allocation—the percentage of stocks and bonds that aligns with your risk tolerance. Once this is set, search for the lowest-cost vehicles to fill those “buckets.” For example, if you need total US stock market exposure, look for funds with expense ratios that are as close to zero as possible. There is rarely a compelling reason for an average investor to pay a high premium for passive beta exposure.
Minimize “portfolio drift” by rebalancing once or twice a year, rather than constantly tweaking your holdings. Constant trading leads to transaction costs, bid-ask spreads, and potential capital gains tax events. Tax-loss harvesting can also be a powerful tool for those managing taxable accounts; by offsetting gains with losses, you can lower your total tax bill, which is another form of “fee” that destroys wealth.
Finally, consolidate your accounts where possible. Having accounts scattered across multiple brokerages often leads to duplicate fees, disjointed strategy, and administrative headaches. By centralizing your assets, you can better monitor total costs and ensure your portfolio remains aligned with your long-term goals.
Frequently Asked Questions
What is a “good” expense ratio for an index fund?
While this varies depending on the asset class, many broad-market index funds now offer expense ratios below 0.10%. Some of the largest, most competitive providers offer index funds with ratios as low as 0.03% to 0.05%. Anything significantly higher than 0.20% for a standard index fund is generally considered expensive in today’s market.
Are higher fees always a sign of a bad investment?
Not necessarily, but they are a sign of a lower net return. While high fees might be associated with specialized, actively managed products that aim to outperform, studies frequently show that the majority of these funds struggle to beat their benchmark after fees are accounted for. High fees are almost guaranteed to lower your net outcome, whereas performance is never guaranteed.
How do 12b-1 fees work?
12b-1 fees are annual marketing and distribution fees charged by some mutual funds. They are included in the fund’s total expense ratio and are used to pay for marketing expenses or commissions to brokers. These fees effectively reduce the amount of money actually invested in the market and are often considered an unnecessary drag on performance by passive investors.
Can I see how much I have paid in fees on my statement?
Unfortunately, most brokerage statements do not clearly label the dollar amount paid in internal fund fees. Because these fees are deducted from the fund’s share price, they are “invisible.” You usually have to calculate the dollar impact yourself by multiplying your average account balance by the expense ratio percentage found in the fund prospectus.
Is it worth paying a financial advisor to manage my portfolio?
For individuals with complex tax situations, significant wealth, or those who struggle with emotional decision-making, an advisor can provide immense value that outweighs their cost. However, you should ensure that the value they provide—such as tax planning, estate coordination, or behavior coaching—justifies the fee. If they are simply picking stocks, you may find better value in a self-managed, low-cost portfolio.
How often should I review my portfolio for hidden fees?
At a minimum, you should conduct a “fee audit” once every year. During this review, check the current expense ratios of every fund in your portfolio. If a fund’s fees have increased or if a newer, cheaper equivalent has become available, it may be time to reallocate your assets to ensure you are not losing money unnecessarily.
Conclusion
Wealth building is not just about the returns you achieve; it is about how much of those returns you get to keep. Investment fees are the silent architects of wealth destruction, slowly chipping away at your capital and the compounding potential of your future. By auditing your current holdings, prioritizing low-cost passive instruments, and carefully evaluating the value of any financial advice you receive, you take control of your financial destiny.
The journey to wealth is a marathon, not a sprint. Every basis point you save is a step closer to your financial independence. Start by reviewing your most expensive accounts today, and look for opportunities to simplify your strategy. Your future self will thank you for the extra capital that was saved from the erosion of unnecessary fees.
Are you ready to take control of your wealth? Subscribe to our newsletter for more actionable strategies on maximizing your investments and securing your financial future.
By wealthsimplyput Editorial Team
This article is for informational purposes only and does not constitute financial advice. Consult a qualified financial professional before making financial decisions.
Leave a Reply